
Q3 Results Preview Might Change The Case For Investing In PrairieSky Royalty Stock
- PrairieSky Royalty is in focus after a fresh DCF review suggested its intrinsic value sits well above the current share price, putting recent performance and cash generation capacity under the microscope as investors assess the implications of the Q3 2026 results.
- The tension between PrairieSky Royalty’s capital light royalty model and the cash flow required to support that DCF valuation spotlight puts leasing activity, drilling intensity on its lands, and operating cost discipline at the center of the debate.
- The discussion will look at how PrairieSky Royalty's investment narrative lines up with the recent DCF based undervaluation signal.
PrairieSky Royalty Investment Narrative Recap
To own PrairieSky Royalty, you need to be comfortable with a capital light model that relies on third party operators to keep drilling on its fee lands and royalty acreage. Higher crude prices give those operators more incentive to keep rigs running, which supports near term royalty volumes, leasing activity and bonus payments.
The key short term catalyst is how Q3 2026 results update the cash flow picture behind that recent DCF work. The main near term risk is a slowdown in Clearwater, Mannville and Duvernay activity, since management already flagged that recent step change efficiency gains are unlikely to repeat in 2026 and 2027.
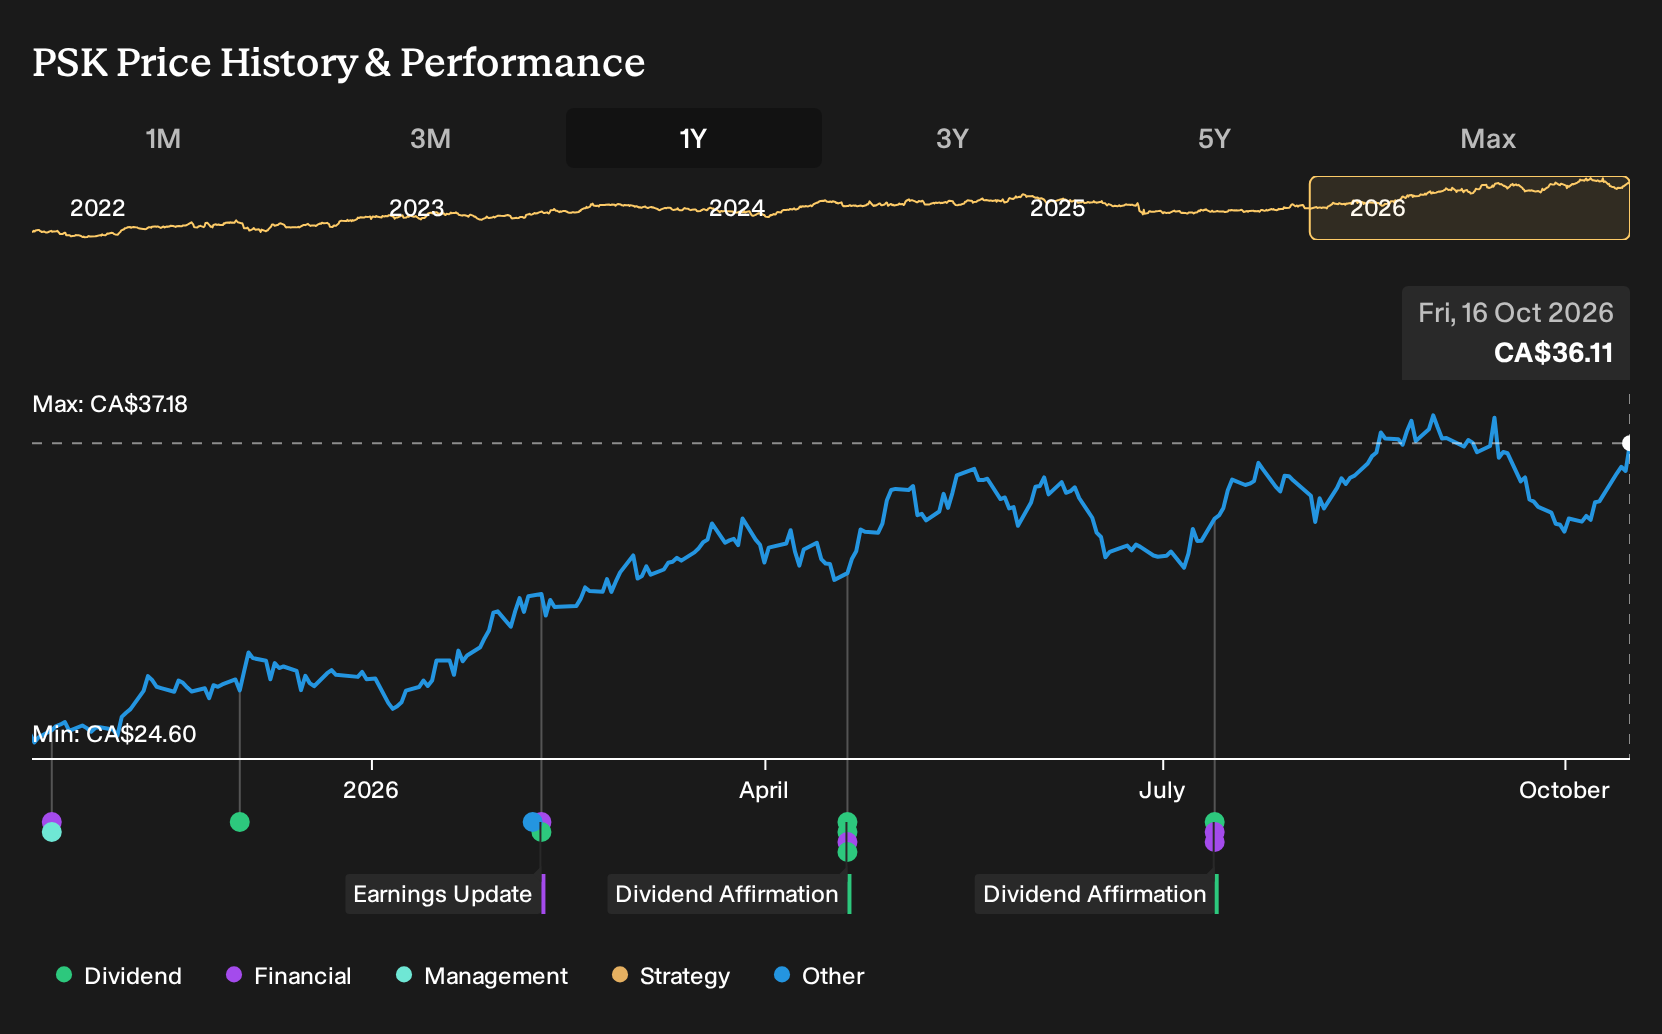
The most relevant data point right now is the DCF estimate that PrairieSky Royalty trades about 37.9% below an intrinsic value of roughly CA$58.19 per share. That signal only really matters if upcoming results show royalty cash flow holding up against a backdrop of higher crude prices and a still active drilling slate on its acreage.
On the flip side, the current P/E of 34.8x, which sits above both Canadian oil and gas peers and analyst target multiples for 2028, keeps execution risk front and center. If operators temper activity or bonus and leasing income soften, the gap between DCF value and market pricing could narrow without any share price move, purely through revised cash flow expectations.
PrairieSky Royalty Forecasts Behind The DCF Signal
Analyst assumptions put some clear numbers behind PrairieSky Royalty's cash flow story. Revenue is projected to expand by 6.9% a year over the next three years. Profit margins are expected to move from 48.0% today to 50.2% by 2028, which points to a bigger share of each royalty dollar dropping to the bottom line if those estimates prove accurate.
On earnings, the current profit pool of CA$220.8 million is expected to reach CA$282.3 million by 2028. That implies an increase of about CA$61.5 million over the forecast period, with consensus also calling for earnings per share of CA$0.92 as the share count edges down by 2.61% a year. For investors tracking the DCF work, the key question is whether leasing trends and drilling on Clearwater, Mannville and Duvernay acreage can sustain that kind of earnings profile through to the forecast horizon.
Those same projections feed directly into how the equity is being valued. The analyst group is working off 2028 revenue expectations of CA$562.7 million and earnings of CA$282.3 million. This ties back to the DCF intrinsic value signal flagged earlier. To line up with the consensus target, you would need to be comfortable with PrairieSky Royalty trading on a 28.0x P/E multiple on those 2028 earnings, compared with 28.8x today and an industry P/E of 15.0x, while applying a discount rate around 6.1% to bring those future cash flows back to today.
PrairieSky Royalty's narrative projects 2028 revenue of CA$562.7 million and earnings of CA$282.3 million. This requires 6.9% yearly revenue growth and an earnings increase of about CA$61.5 million from CA$220.8 million today.
Uncover why PrairieSky Royalty's fair value indicates a 15% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community range from about CA$30.82 to CA$58.19 per share, which gives PrairieSky Royalty a wide valuation band to consider. Set that against the risk that activity in Clearwater, Mannville and the Duvernay cools, and it becomes clearer why opinions differ sharply. Use that spread as a prompt to explore several competing viewpoints before you settle on any single narrative.
Explore 2 other PrairieSky Royalty fair value estimates, including one that suggests as much as 15% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis.
- A great starting point for your PrairieSky Royalty research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PrairieSky Royalty. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate PrairieSky Royalty's overall financial health at a glance.
Looking For More Investment Ideas Beyond PrairieSky Royalty?
If PrairieSky Royalty has sharpened your focus on cash generation, balance sheet strength and valuation, it can help to line it up against a broader watchlist of candidates that fit similar themes.
- For investors who want to focus on quality first and valuation second, scan a curated set of financially resilient companies through a list of solid balance sheet and fundamentals (8 results) that combine sturdy finances with fundamental support.
- If downside protection is front of mind, filter for steadier profiles by running through a 8 resilient stocks with low risk scores that screens for businesses with more resilient risk scores.
- Those hunting for under-the-radar ideas can cast a wider net by reviewing a 10 high quality undiscovered gems that highlight lesser known stocks with stronger fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com