
3 UK Growth Stocks Retail Investors Are Watching As Tax Rules Pressure Small Caps
ICAEW’s warning that the UK tax system is “damaging growth” has pushed an old worry back into the spotlight. Smaller domestically focused stocks often feel every extra form and threshold in their margins and share prices, which can create mispricing when sentiment sours first and facts arrive later. This article walks through three UK small and mid-cap growth stocks exposed to these tax debates and why they might matter for a diversified portfolio today.
The three stocks below are just a starting sample. The full screen surfaced 23 more UK small and mid-cap companies with equally compelling narratives that are not covered in this article.
If you want to identify, compare, and analyse those extra opportunities side by side, head straight to the UK Small and Mid-Cap Domestic Growth Stocks screener.
Marks Electrical Group (AIM:MRK)
Marks Electrical Group is a pure-play UK retailer of domestic appliances and consumer electronics, selling and installing products nationwide from an online platform. All recent revenue of about £108 million comes from online retail in the UK, and the business currently carries a market value of roughly £51 million.
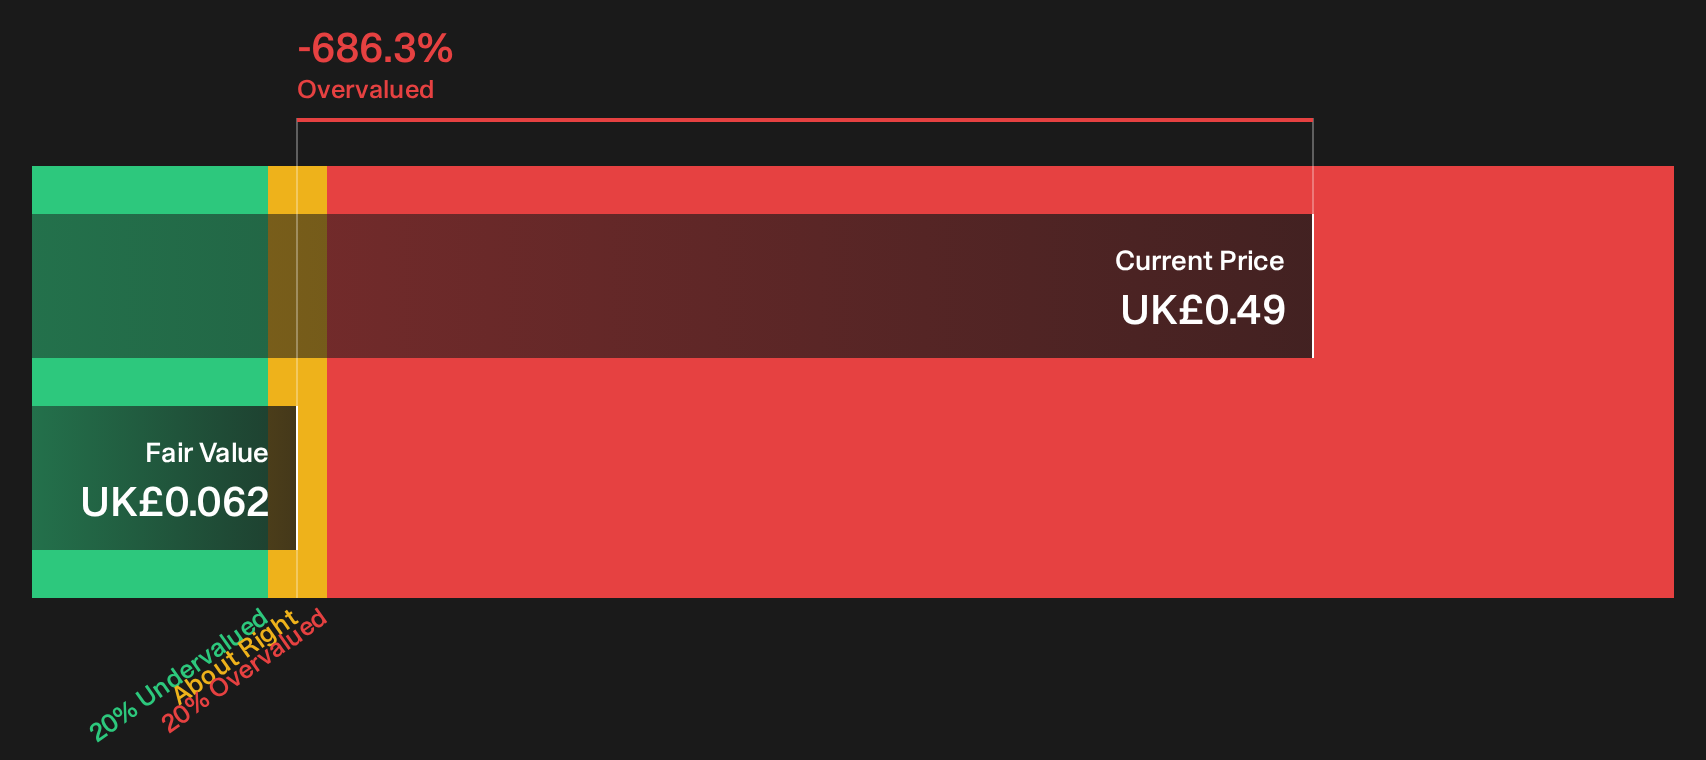
This is a small UK-focused retailer, fully tied to local household spending and VAT rules. It is priced on a premium P/S multiple while still loss making. Earnings are forecast to grow quickly, so sentiment around UK tax reform and consumer taxes could matter a lot if a single unseen pressure shifts how investors think about those future margins.
If that future margin story is what you care about, go straight to the DCF valuation analysis for Marks Electrical Group to see how those assumptions could be shaping sentiment.
Tracsis (AIM:TRCS)
Tracsis fits this UK domestic growth screen as a Leeds based transport software and data specialist, plugged directly into rail and infrastructure spending where tax and investment rules often shape project timing and appetite for digital upgrades.
Tracsis provides transport focused software, hardware, and analytics for operators and infrastructure owners, with around £39 million from Rail Technology & Services and £45 million from Data, Analytics, Consultancy & Events, and a current market value close to £94 million.
"Nationwide smart ticketing contracts that currently feed roughly one-third of Tracsis revenue through recurring and transactional streams could see a second phase as integrated rail reforms and PAYG adoption expand usage, supporting a higher mix of software revenue and potentially lifting group EBITDA margins."
The real swing factor is how one unresolved shift in rail funding and digital adoption shapes those future margins investors are banking on.
That funding hinge is exactly what the full narrative for Tracsis unpacks, separating stalled contract risk from areas where Tracsis earnings power could be quietly accelerating.

Quartix Technologies (AIM:QTX)
Quartix Technologies offers GPS tracking and fleet management tools to UK-based fleets and SMEs, which ties it closely to this domestic growth theme. It generates about £20.7 million of revenue from the UK, with France, the US and other European markets adding roughly £17.1 million combined, and carries a market cap near £111 million.
Quartix Technologies sits squarely in the screener’s sweet spot because its telematics subscribers are rooted in UK fleets whose investment budgets are highly sensitive to tax rules and cash incentives.
"The redesigned and cost-reduced telematics hardware, along with planned software updates, aims to bolster performance while reducing costs. This is expected to support margin improvements and enhance competitiveness in the market."
What happens when that operational progress meets a shift in how smaller fleets are taxed could be the quiet driver of future profitability.
When that tax sensitive fleet spend starts decoupling from old assumptions, the full narrative for Quartix Technologies shows where Quartix Technologies growth ambitions and risk factors really intersect.

Seeking Alternatives Before Others Catch On
Fresh ideas move first. The strongest stories often gain momentum quietly, then start breaking out while latecomers get caught chasing. Scan what is still under the radar for now and act now.
- Spot resilient balance sheets before momentum chasers arrive by running the list of solid balance sheet and fundamentals (9 results) while the strongest fundamentals are still priced like afterthoughts.
- Track potential yield workhorses as prices move by using the 2 dividend fortresses to focus on payouts strong enough to matter if markets turn choppy.
- Follow the AI build out while infrastructure demand is still forming by filtering for enablers of that spend through the 55 AI infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com