
Is UBS Group (SWX:UBSG) A Bargain Following Its Rate Call And HQ Move?
UBS Group (SWX:UBSG) is in the spotlight after two big decisions: a revised forecast calling for three US interest rate hikes by March 2027, and a plan to shift its headquarters out of Switzerland.
Recent headlines around UBS Group's rate call and potential headquarters move arrive after a mixed run in the market, with the share price at CHF39.63, a modest year to date rise and a much stronger 1 year total shareholder return of 34.25% signaling momentum that has cooled in recent months as investors reassess both growth prospects and regulatory risk.
Scan how other large financial institutions are reacting to the same rate and regulatory pressures by reviewing the hand picked list of solid balance sheet and fundamentals (203 results) alongside UBS Group.
UBS Group has already delivered a strong 1 year total return at CHF39.63, yet the sharper gains sit in the rearview. The real task now is working out how much upside is still on the table.
Most Popular Narrative: 10% Undervalued
Against UBS Group's last close at CHF39.63, the most followed narrative points to a fair value of CHF44.11, which implies meaningful upside once you factor in execution and regulatory risk.
The ongoing integration of Credit Suisse is progressing ahead of schedule, driving meaningful cost savings, increased scale, and improved operating efficiency. As these synergies are realized through further platform migration and operational streamlining, UBS's net margins and return on equity are likely to improve, supporting higher earnings growth.
See why 61 investors see UBS Group as 10% undervalued.
Result: Fair Value of CHF44.11 (UNDERVALUED)
Still, the narrative around UBS Group can unravel quickly if Swiss capital rules force it to hold US$24b to US$42b more capital, or if Credit Suisse integration setbacks drag on profitability longer than expected.
Find out about the key risks to this UBS Group narrative.
Another View: UBS Group Through The P/E Lens
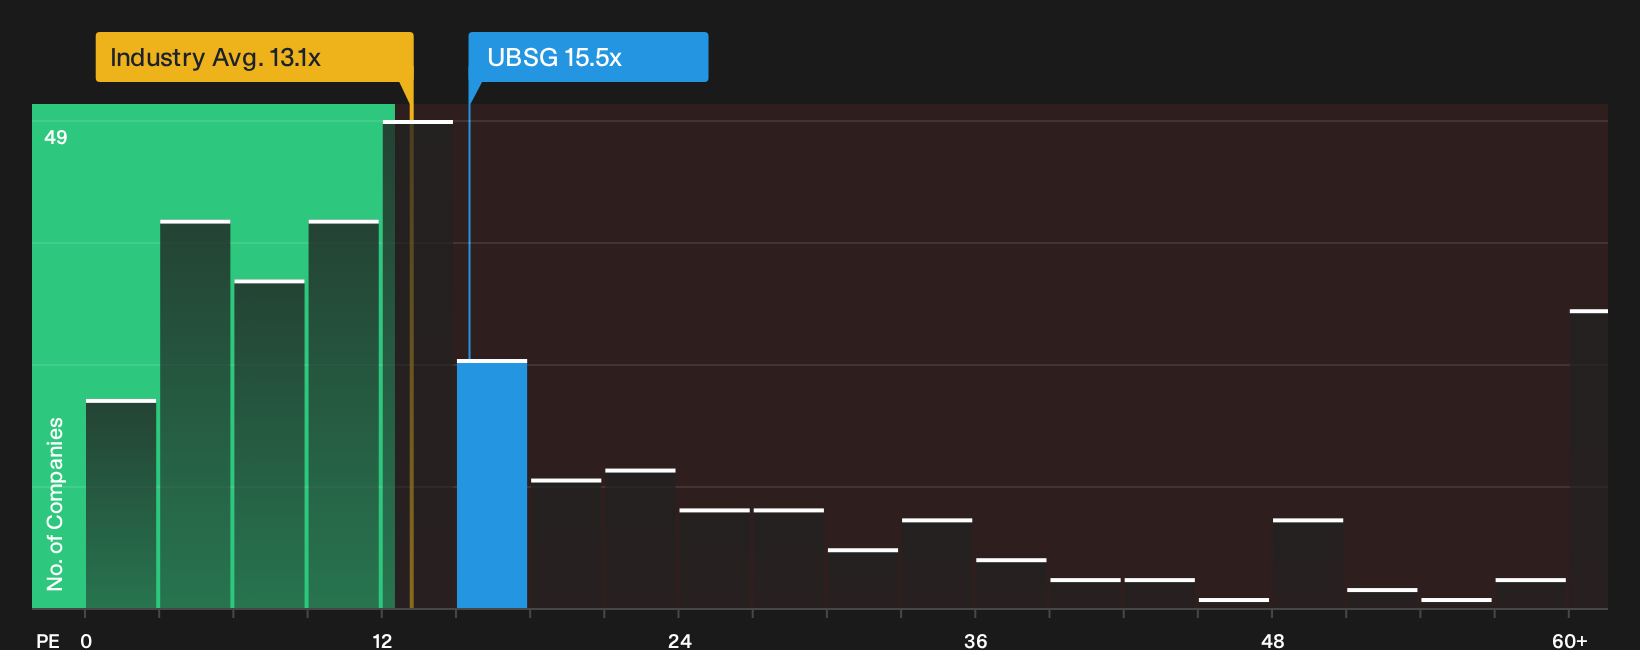
DCF work suggests UBS Group is trading well below an estimated fair value of CHF67.28, which frames the stock as undervalued. The P/E picture is less generous. At 15.5x earnings, UBSG is richer than the European capital markets average of 13.2x, yet below a fair ratio of 21.7x that our model implies.
This mix of a discount to fair ratio, a premium to the wider industry, and a P/E below close peers points to both room for re-rating and the risk that expectations are already running ahead of delivery. The real question is which side of that trade you think will matter more over the next few years.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or early opportunity? If you want to evaluate UBS Group on your own terms, consider both sides of the ledger through the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond UBS Group?
If UBS Group has sharpened your thinking, do not stop here. Fresh ideas often come from comparing opportunities side by side with different strengths.
Use these focused stock lists to pressure test your portfolio and spot opportunities that others might ignore.
- Target potential mispricing by scanning a 191 high quality undervalued stocks that filters for quality businesses trading below their fundamentals.
- Build a smoother ride through swings in sentiment by reviewing 233 resilient stocks with low risk scores with resilient balance sheets and steadier risk profiles.
- Hunt for future leaders early by checking a curated pool of 618 high quality undiscovered gems that pair solid financials with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com