
Jiangsu Expressway (SEHK:177) Is Getting Attention, What Is The Market Missing?
Recent share moves in Jiangsu Expressway (SEHK:177) have drawn attention after a period of solid returns over the past year. This has prompted investors to reassess how the toll road operator’s valuation lines up with its fundamentals.
With the share price now at HK$11.41 after a small pullback over the last day, Jiangsu Expressway is coming off a strong run, including a 30 day share price return of 8.98% and a year to date gain of 17.87%. Over a longer horizon, momentum has been supported by a 1 year total shareholder return of 25.50% and triple digit total shareholder returns over 3 and 5 years. This indicates that recent price action forms part of a much longer period of investor optimism rather than a short lived spike.
Scan for other potential momentum stories that feature a similar quality tilt by reviewing our hand picked 191 high quality undervalued stocks.
The question now is simple. Does Jiangsu Expressway’s latest pullback reveal a price drifting away from business reality, or just a pause in sentiment after a strong run, and what does that mean for valuation today?
Preferred P/E of 10.5x: Is it justified?
On simple earnings terms, Jiangsu Expressway trades on a P/E of 10.5x at a last close of HK$11.41. That earnings multiple prices the stock above its direct peer group but below the broader Asian infrastructure space, so the question is whether the current level fairly reflects the business profile and outlook.
The P/E ratio compares Jiangsu Expressway's share price to its net profit per share and gives you a shorthand view of how much investors are paying for each unit of earnings. For a mature toll road operator with steady but moderate profit growth, this lens is often more informative than top line measures, particularly in situations where revenue is forecast to decline and earnings are still expected to increase.
Against Hong Kong infrastructure peers on an 8.9x average P/E, Jiangsu Expressway screens as more expensive. This suggests the market is willing to pay a premium for its earnings quality and returns. Compared to the wider Asian infrastructure industry on 13.1x, the stock trades at a clear discount. This gap points to scope for the multiple to move closer to a level that our fair P/E estimate of 10.8x indicates as reasonable if sentiment or earnings profiles align.
Explore the SWS fair ratio for Jiangsu Expressway.
Result: Price-to-earnings of 10.5x (ABOUT RIGHT)
Still, Jiangsu Expressway’s revenue declined 5.9% while earnings grew 4.6%, and any reversal of that profit resilience or regulatory shifts could quickly challenge today’s rating.
Find out about the key risks to this Jiangsu Expressway narrative.
Another View: Jiangsu Expressway Through A Cash Flow Lens
Price ratios tell one story about Jiangsu Expressway. The SWS DCF model tells another. On that framework, the stock at HK$11.41 sits below an estimated future cash flow value of HK$14.04, which points to undervaluation and leaves you asking how comfortable you are with the assumptions behind those forecasts.
Look into how the SWS DCF model arrives at its fair value.
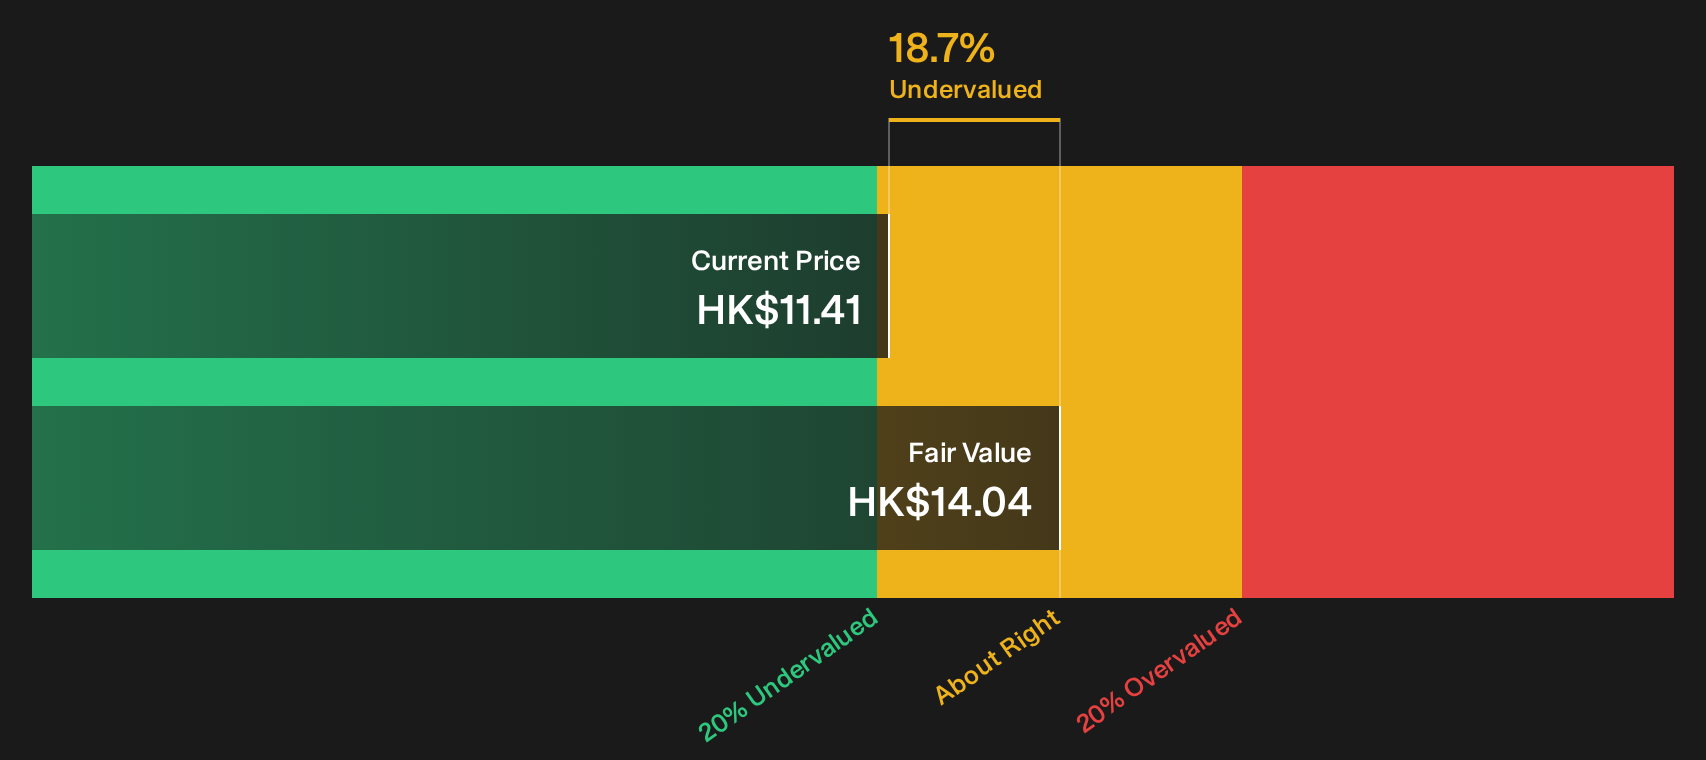
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Jiangsu Expressway for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If Jiangsu Expressway now appears to sit at a fine balance between optimism and caution, move quickly from the headline takeaways to the underlying data and decide where you stand by reviewing the 3 key rewards and 2 important warning signs.
Ready for more ideas beyond Jiangsu Expressway?
If Jiangsu Expressway sharpened your thinking on valuation, do not stop here. Broaden your watchlist and pressure test your thesis against other opportunities.
- Target higher potential payoffs with carefully filtered small caps by reviewing 131 elite penny stocks with strong financials that already show stronger underlying financial strength.
- Zero in on quality at a discount and pressure test your valuation instincts against our hand picked 191 high quality undervalued stocks with solid fundamentals.
- Prioritise resilience by focusing on companies with healthier finances through our curated list of solid balance sheet and fundamentals (203 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com