
HUB24 (ASX:HUB) Slides Into A Valuation Debate, Is The Pullback Enough?
Recent debate around HUB24 (ASX:HUB) has intensified after the stock’s sharp share price decline this year, with investors questioning whether its current valuation is supported by underlying returns on capital.
The recent slide in HUB24’s share price, including a 30-day share price return that declined 8.62% and a year to date share price return that fell 33.02%, contrasts sharply with a 3-year total shareholder return of 107.60%. This suggests longer term holders have still seen strong compounding even as shorter term momentum fades and market sentiment reassesses the risk and reward trade off at A$64.15.
Spot opportunities beyond HUB24 by scanning a curated short list of quality stocks that screen well on cash flows and balance sheet strength using our 4 high quality undervalued stocks.For HUB24, a steep year to date slide, set against still strong multi year returns, leaves a simple question: Does the current A$64.15 tag now skew the risk reward toward fresh buyers, or argue for more caution as valuation is tested next?
Most Popular Narrative: 32.1% Undervalued
On the most followed view of HUB24, the A$64.15 share price sits well below a fair value estimate of A$94.41. This puts the recent share price slide in the context of a valuation framework built on revenue, margin and discount rate assumptions.
The strategic positioning of HUB24 as a market leader with strong growth in funds under administration (FUA) is presented as indicating potential for ongoing revenue growth, based on a 4-year CAGR of 42% in group revenue. This is accompanied by an increase in market share from 6.6% to 7.9% over the last 12 months.
See why 17 investors see HUB24 as 32% undervalued.
Result: Fair Value of A$94.41 (UNDERVALUED)
Still, that underrating case can unravel quickly if competition forces lower pricing or if a sharp equity market slump drags on funds under administration and fee revenue.
Find out about the key risks to this HUB24 narrative.
Another View on HUB24’s Valuation
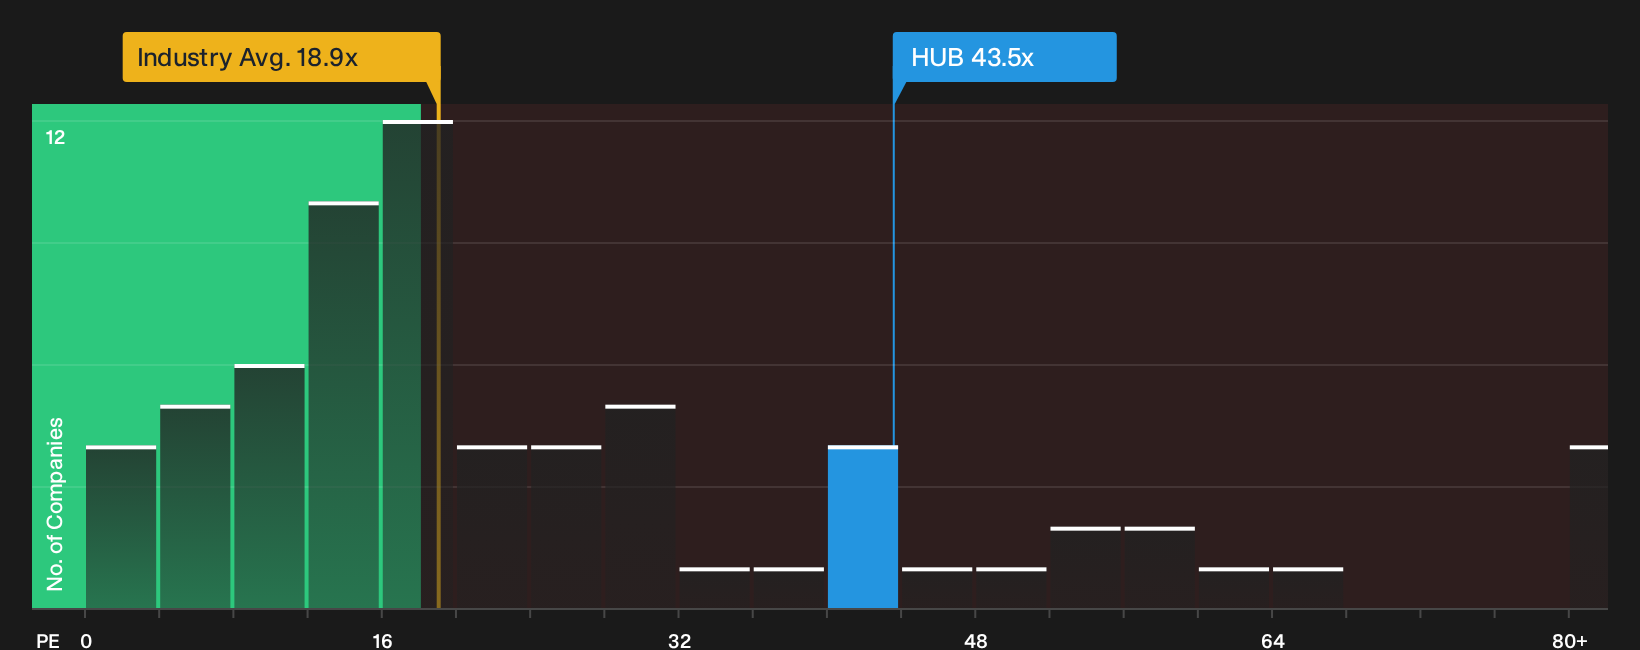
The first narrative leans on analyst fair value of A$94.41, yet HUB24 screens very differently when looking at the P/E ratio. At A$64.15, the shares trade on 43.5x earnings, which is higher than the estimated fair ratio of 21.4x, the Australian Capital Markets average of 18.7x, and the peer average of 25.9x. That gap points to meaningful valuation risk if sentiment or growth expectations cool.
For a closer look at what this richer P/E might mean for future returns, and how the ratio could move toward the fair ratio over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on HUB24’s valuation story so far. If the debate feels finely balanced, consider reviewing the underlying data for yourself using the 2 key rewards.
Looking for more investment ideas beyond HUB24?
If HUB24 has you thinking harder about price, quality and risk, use that momentum and line up a few fresh candidates for your watchlist today.
- Target reliable cash generators by reviewing companies on the list of solid balance sheet and fundamentals (12 results) that pair stronger finances with steadier fundamentals.
- Hunt for underappreciated opportunities by scanning the 15 high quality undiscovered gems that already show solid metrics yet attract limited market attention.
- Dial down portfolio stress by focusing on the 6 resilient stocks with low risk scores that keep volatility and financial risk scores in tighter check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com