
Will Earnings Beat Change Simmons First National's Stock Narrative
- Simmons First National reported third quarter 2026 results with net interest income of US$203.98 million and net income of US$47.11 million, compared with a loss in the prior year period, and adjusted EPS of US$0.54 that came in slightly ahead of analyst expectations.
- Behind the headline beat, Simmons First National showed a mix of positives and pressure points, including a 3.9% net interest margin, an efficiency ratio of 71.6%, stronger capital at a 14.8% total risk based ratio, and higher than anticipated nonperforming loans and assets.
- We will now look at how Simmons First National's earnings beat on US$0.54 adjusted EPS could influence its broader investment narrative.
Simmons First National Investment Narrative Recap
To own Simmons First National, you need to be comfortable with a slow, grinding improvement story, not a quick fix. The Q3 adjusted EPS of US$0.54 and 3.9% net interest margin point to a business that is earning its way out of past issues, while still wrestling with efficiency and credit clean up. The most important near term swing factor remains how well those repricing loans and core deposits offset funding pressure.
The biggest operational risk today sits in that same funding and credit mix. Fierce deposit competition, elevated nonperforming loans and a 71.6% efficiency ratio mean the bank has little room for sloppy execution. This quarter helps the thesis around capital strength and revenue resilience, but it does not materially change the core risk reward equation yet.
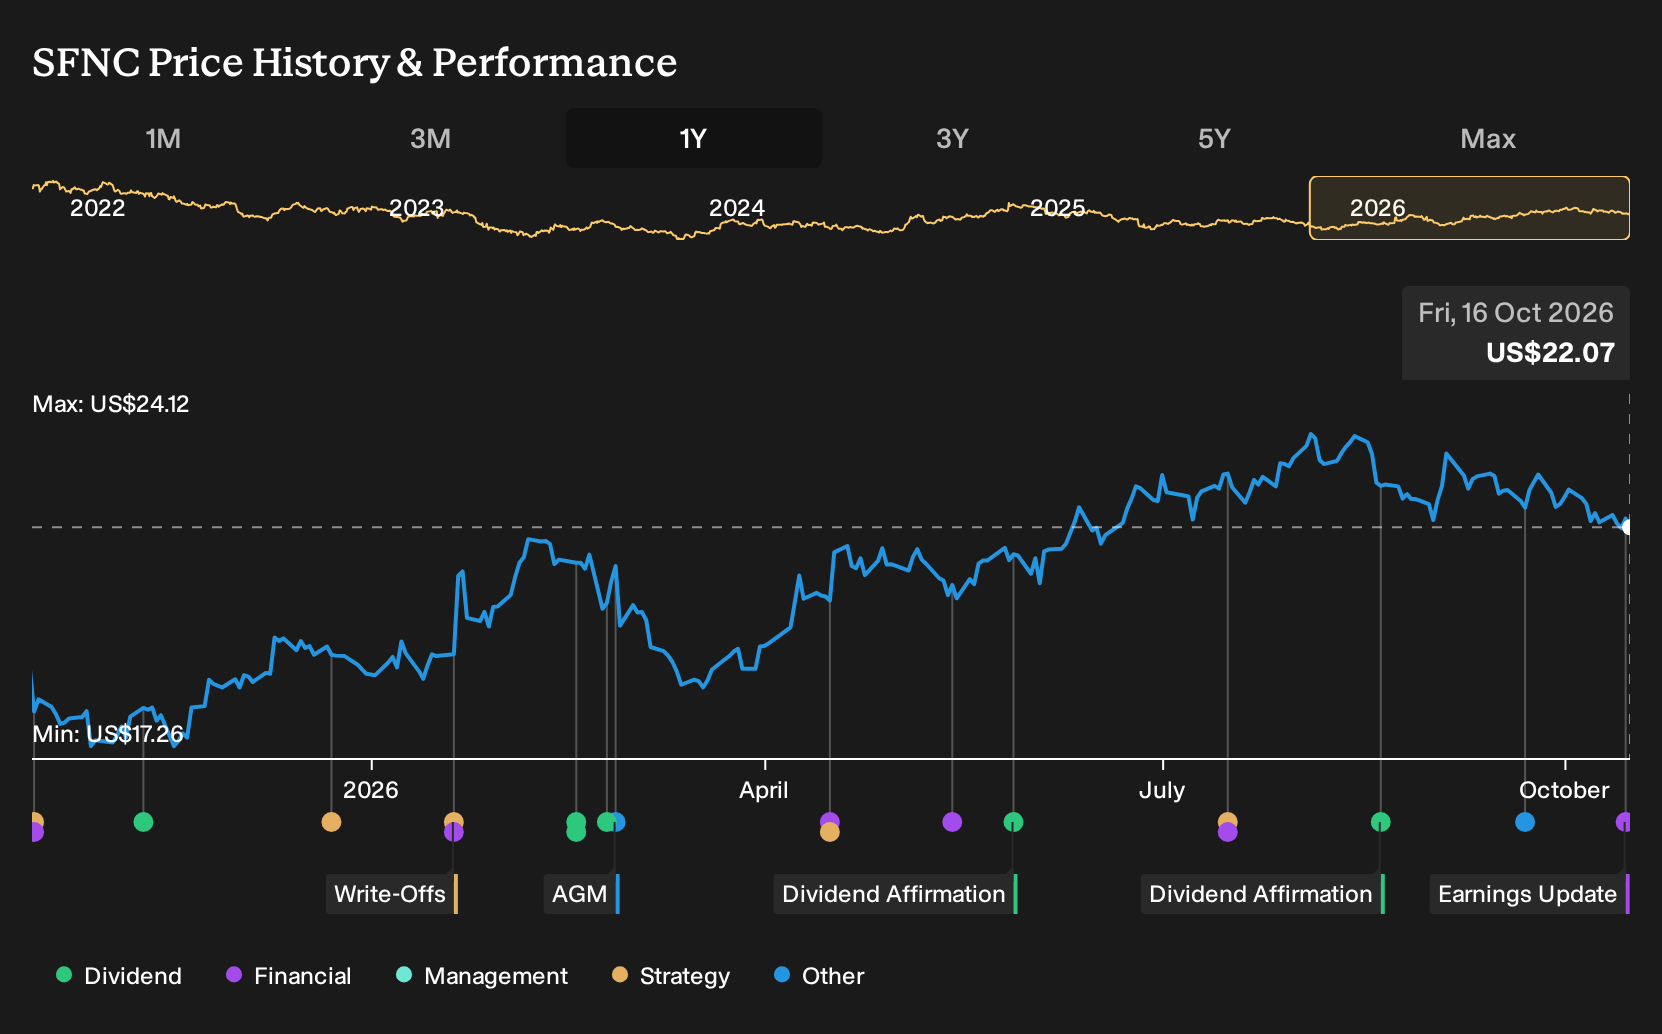
The key announcement here is the third quarter 2026 earnings release, where Simmons First National reported US$254.28 million in revenue and adjusted EPS of US$0.54. That update matters because it ties directly to the core catalysts investors are watching, including repricing of sub 4% loans and the ongoing efficiency push across the branch network.
Higher net interest income of US$203.98 million and a total risk based capital ratio of 14.8% show the balance sheet carrying the weight of the turnaround. At the same time, revenue slightly below some expectations, a relatively high efficiency ratio and increased nonperforming assets keep the focus on execution risk. Your call as a shareholder hinges on whether this kind of quarter becomes a consistent pattern while those credit issues are worked through.
Simmons First National's narrative projects US$1.6b revenue and US$673.4 million earnings by 2029. This assumes very large yearly revenue growth of 144.2% and an earnings increase of about US$1.0b from current earnings of a US$349.5 million loss.
Uncover why Simmons First National's fair value indicates a 17% potential upside to its current price that could close faster than many investors expect.
Exploring Other Perspectives
Retail investors in the Simply Wall St Community have only two fair value estimates for Simmons First National so far, spanning roughly US$25.93 to US$39.16 per share. That narrow sample still reflects different expectations around earnings power. Set those views against fierce deposit competition and loan pricing pressure, then decide which narrative you find more convincing.
Explore another Simmons First National fair value estimate, including one that suggests as much as 77% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Simmons First National research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Simmons First National. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Simmons First National's overall financial health at a glance.
Looking for more investment ideas beyond Simmons First National?
Once you have a view on Simmons First National, widen the lens. Use the Simply Wall St Screener to quickly line up other companies that fit the kind of risk, balance sheet strength, or income profile you want in your portfolio.
- If you want companies with stronger cushions against shocks, start with a curated 32 resilient stocks with low risk scores that keep overall risk scores in check.
- For investors hunting for quality at a reasonable price, scan a focused 33 high quality undervalued stocks that blend robust cash flows with disciplined balance sheets.
- Income seekers who care about consistency as much as yield can review a targeted 8 dividend fortresses built around higher payout levels and durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com