
Zurich Insurance Group (SWX:ZURN) Names China CEO, Is The Stock Fully Valued?
Zurich Insurance Group (SWX:ZURN) has appointed Scott Yin as CEO for China, a leadership shift that puts commercial insurance growth in the Chinese market in sharper focus for shareholders.
Recent trading has been constructive for Zurich Insurance Group, with a 7 day share price return of 6.49% and a 1 day move of 0.85% taking the stock to CHF613.4. The 90 day share price return is down 1.76%, and the 1 year total shareholder return sits at 16.62%, compared with a much stronger 3 year total shareholder return of 72.96% and 5 year total shareholder return of 101.36%. This indicates that, while near term momentum has cooled slightly, longer term holders have still seen substantial value creation as the business refreshes leadership in key markets such as China.
Scan beyond Zurich Insurance Group and compare this leadership-driven story with other insurers and financials flagged in our 233 resilient stocks with low risk scores.
Zurich Insurance Group has climbed to CHF613.4 while analyst targets and intrinsic estimates point to a different anchor point for value. How much of that gap still looks appealing after the recent rebound?
Most Popular Narrative: 1% Overvalued
Zurich Insurance Group closed at CHF613.4 against a narrative fair value of CHF609.76, a small premium that keeps the focus on execution rather than a clear bargain or excess.
Zurich is strategically pivoting its P&C business toward specialties and mid-market segments while reducing exposure to large corporate and liability lines. The company is capitalizing on increased demand for complex risk management solutions and better pricing discipline, supporting both sustained revenue growth and improved net margins.
See why 73 investors see Zurich Insurance Group as 1% overvalued.
Result: Fair Value of CHF609.76 (OVERVALUED)
Still, that tidy 1% premium to fair value can unravel quickly if higher expenses linger longer than expected or if softer pricing in key commercial lines reduces profitability.
Find out about the key risks to this Zurich Insurance Group narrative.
Another View: DCF Paints A Very Different Picture For Zurich Insurance Group
The analyst narrative sees Zurich Insurance Group trading about 1% above a CHF609.76 fair value. Our DCF model presents a different perspective, with a future cash flow value of CHF1,332.11 per share, which implies the current CHF613.4 price could be deeply discounted rather than slightly rich.
Two frameworks, two very different answers, and one big question for you as an investor: which set of assumptions feels more realistic over the long haul?
Look into how the SWS DCF model arrives at its fair value.
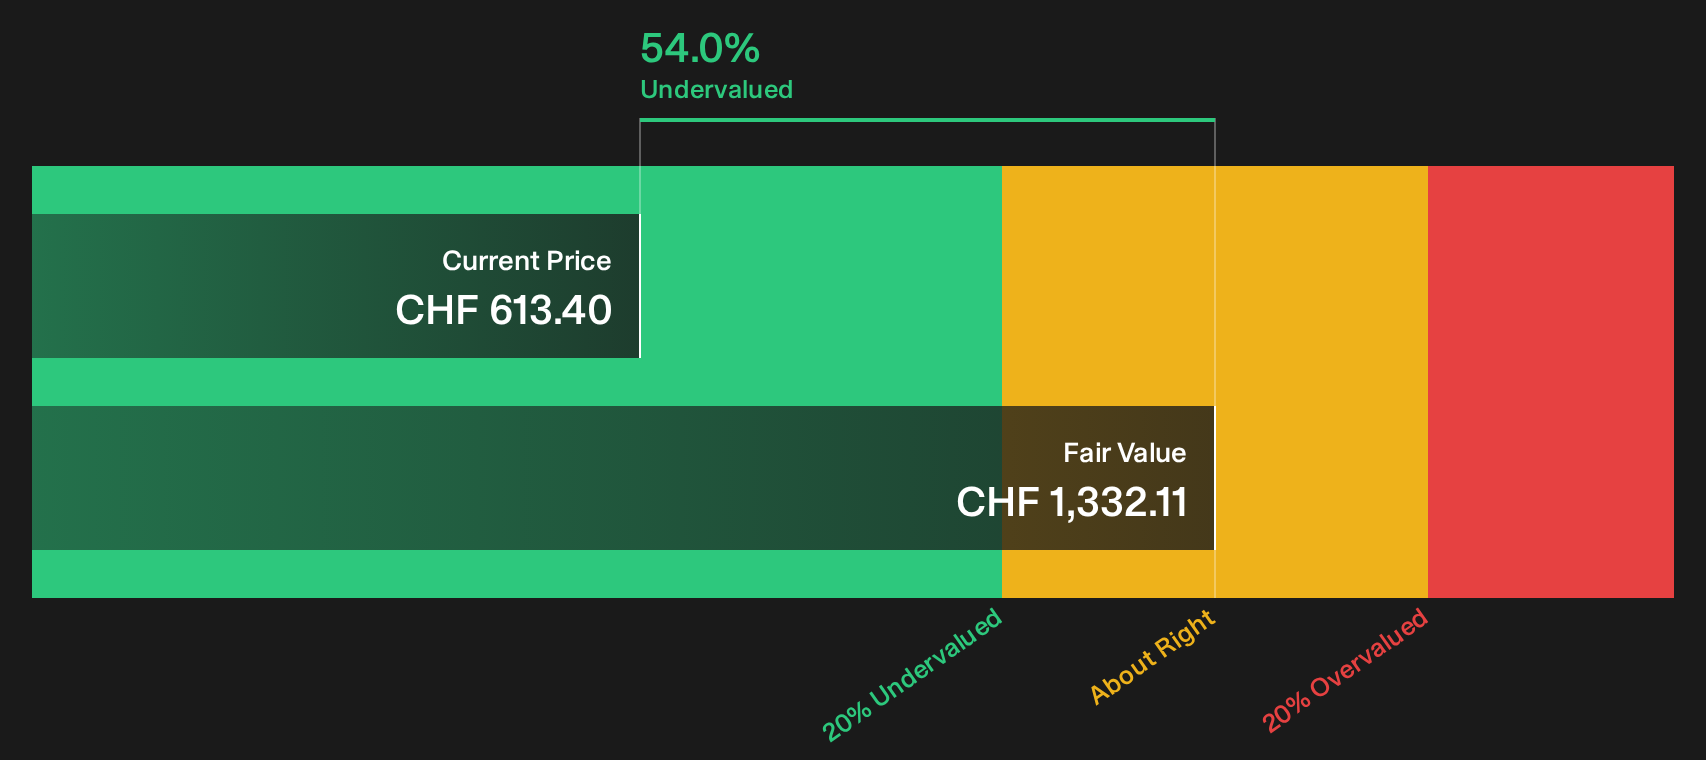
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Zurich Insurance Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in Zurich Insurance Group's valuation story can feel confusing, so it may be useful to move quickly, look through the underlying data, and weigh both the upside and the concerns highlighted in the 3 key rewards and 2 important warning signs.
Looking for more Zurich Insurance Group style ideas?
If Zurich Insurance Group has sharpened your interest in high quality businesses, do not stop here. Widen your watchlist and test fresh ideas with focused screeners.
- Target resilient opportunities that pair quality with potential mispricing by reviewing the 191 high quality undervalued stocks.
- Strengthen your income focus by scanning companies that resemble robust payers through the 214 dividend fortresses.
- Prioritize financial strength and durability by filtering candidates using the list of solid balance sheet and fundamentals (203 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com