
Travelers Companies (TRV) Has Everyone Asking The Same Question
Travelers Companies (TRV) has investors’ attention after reporting third quarter 2026 results that topped profit expectations, paired with a regular US$1.25 quarterly dividend and sizeable capital returns through buybacks.
Travelers Companies has seen momentum pick up, with a 1-day share price return of 1.47% and a 7-day move of 5.64% around the earnings and dividend news, while the year-to-date share price return of 36.59% sits alongside a 1-year total shareholder return of 50.95% and a 5-year total shareholder return of 163.82%. This points to strong recent price strength backed by multi year compounding when dividends are included.
Scan beyond Travelers Companies and see how other insurers, with strong recent momentum and resilient financial profiles, stack up in our curated list of 32 resilient stocks with low risk scores.
After a 36.59% year to date surge and strong third quarter news, Travelers Companies now asks a simple question of you: Lean into this momentum at US$389.54, or wait for a friendlier price tag as the valuation picture comes into focus next.
Most Popular Narrative: 8% Overvalued
Travelers Companies closed at $389.54, while the most followed narrative pegs fair value near $360.54, pointing to a modest premium that investors now need to weigh against a mature profit profile.
The pattern of disciplined underwriting and conservative reserving, backed by 19 years with net favorable prior-year reserve development totaling US$15b pre tax and fresh favorable development across all segments in 2026, may keep supporting core ROE and net margins even if written pricing growth slows.
See why 29 investors see Travelers Companies as 8% overvalued.
Result: Fair Value of $360.54 (OVERVALUED)
Still, the Travelers Companies story can change quickly if catastrophe losses spike beyond reinsurance protection or if long tail casualty claims outpace current reserving assumptions.
Find out about the key risks to this Travelers Companies narrative.
Another View on Travelers Companies’ Valuation
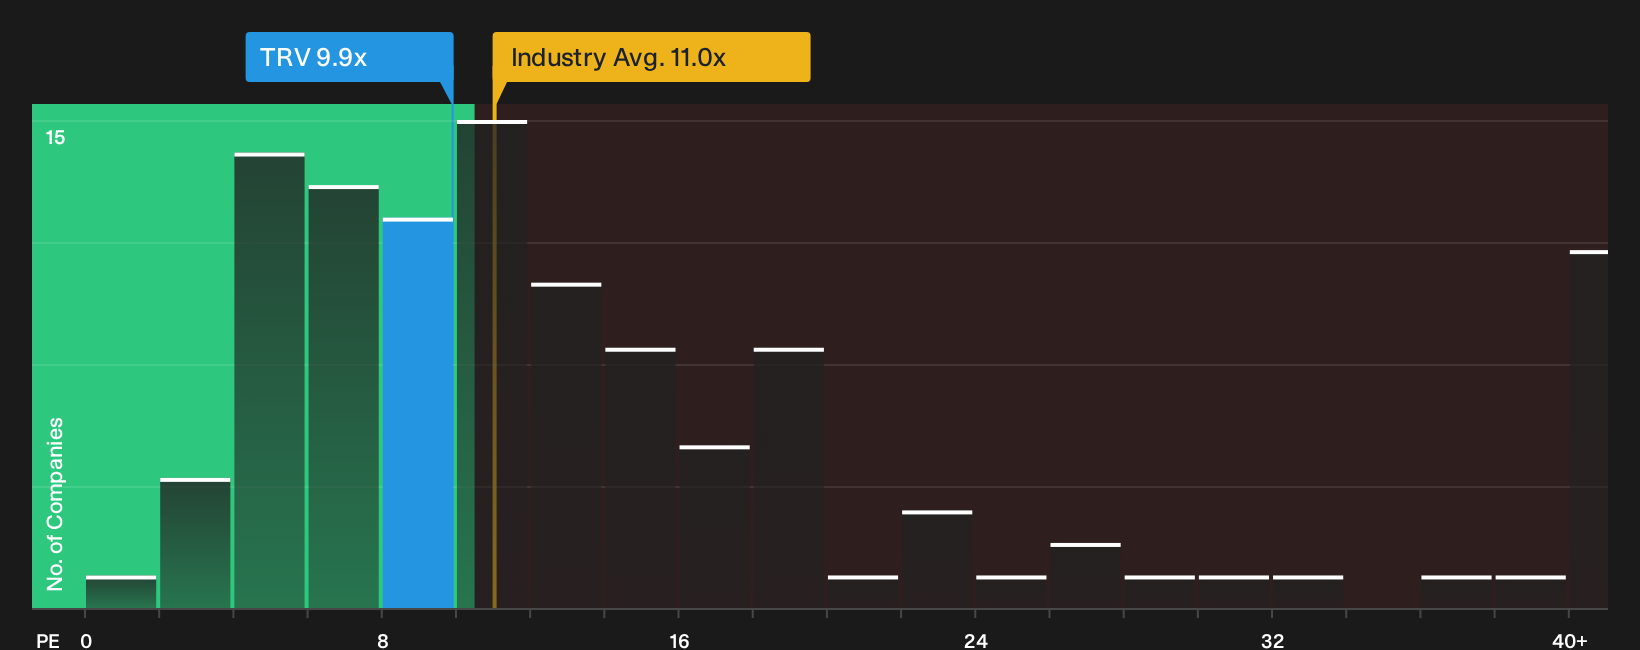
Analysts see Travelers Companies trading modestly above their US$360.54 fair value mark, yet the current P/E of 9.9x looks cheap next to the US Insurance sector at 11x and a fair ratio of 8.8x that peers cluster around. That mix of premium to fair ratio but discount to industry and slight premium to close peers leaves you with a simple question: Which reference point matters most for your own risk tolerance and holding period?
For a closer look at how the earnings multiple stacks up against both peers and that fair ratio that the market could move toward over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Travelers Companies so far. If you want to move before sentiment shifts again, consider both the potential upside and the threats in the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Travelers Companies?
Do not stop at Travelers Companies. Use the Simply Wall Street Screener to spot fresh ideas that match your risk comfort and return goals before the crowd does.
- Hunt for potential bargains by scanning companies that combine attractive valuations with solid fundamentals using the 33 high quality undervalued stocks.
- Build a steadier income stream by zeroing in on businesses with strong yields and resilient payouts in the 8 dividend fortresses.
- Prioritize resilience by focusing on companies with robust balance sheets and healthy financial profiles through the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com