
What REA Group Bears Spotted Before The Slide
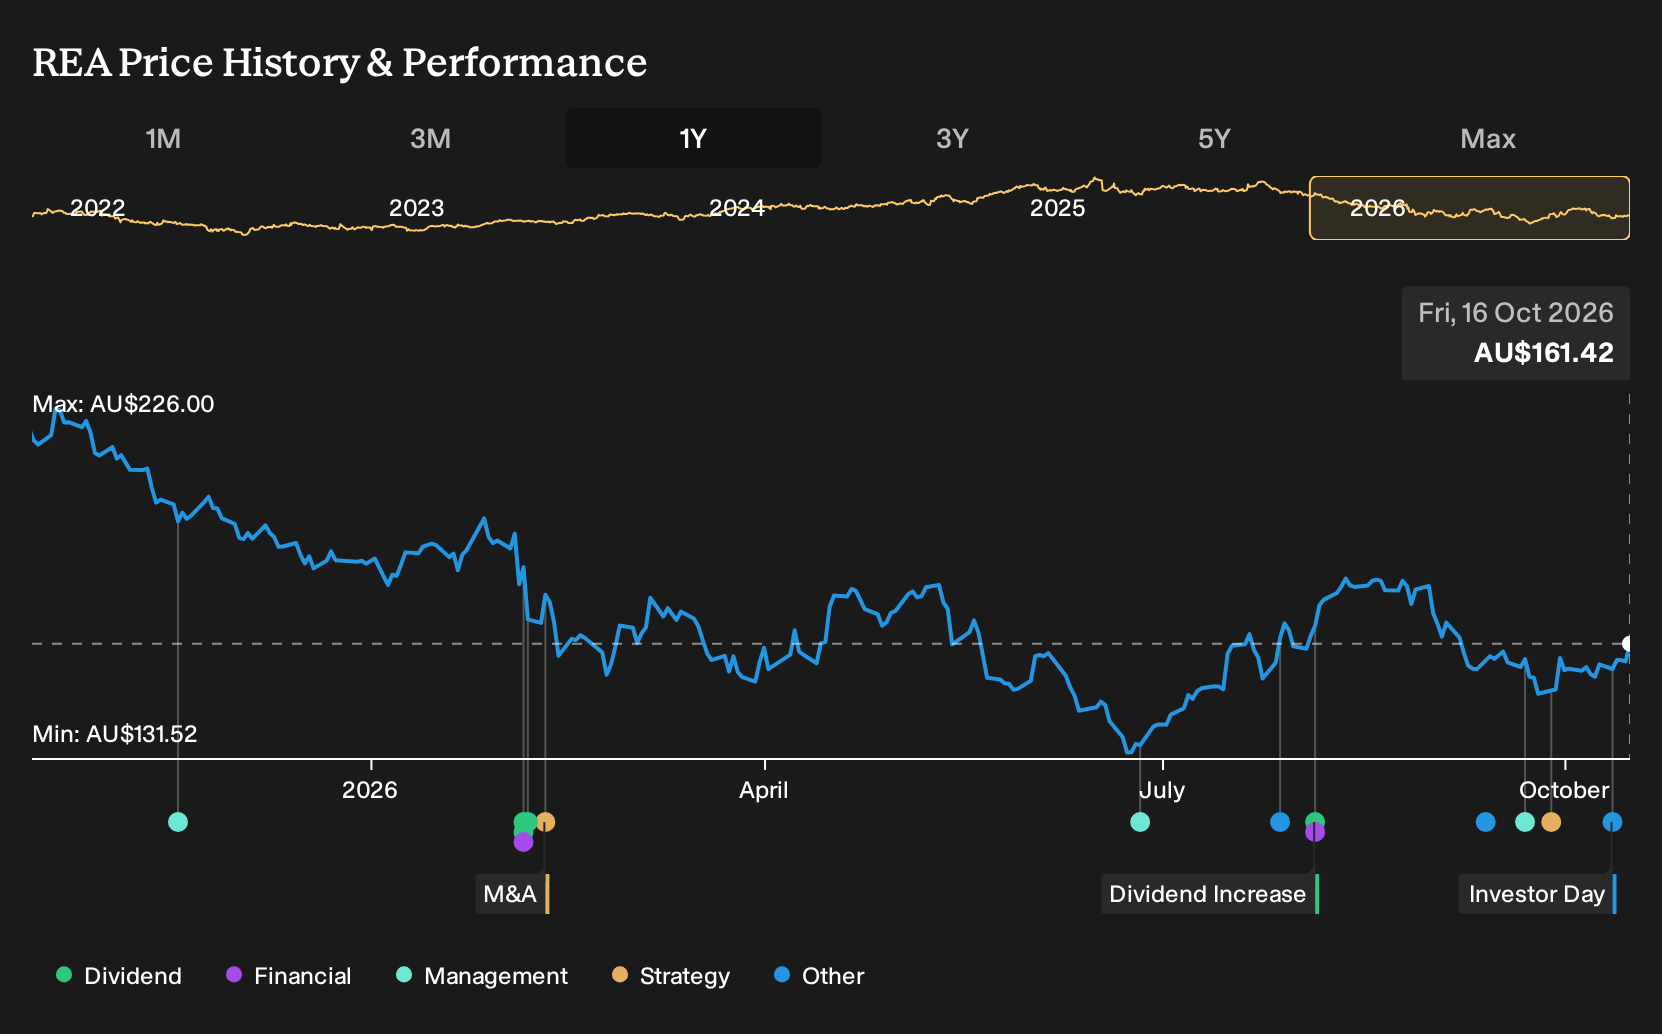
If you had looked at REA Group in October 2025 and decided to sit it out, the decision might feel different after seeing the scorecard. For REA Group shareholders, the loss over the past year was 24.0%, including dividends. With that outcome in hand and fresh headlines about Irish classifieds deals, Indian divestments, ACCC scrutiny, and a softer housing market, which assumption on record at the start would you want to stress test first?
If the move has made REA Group harder to judge, start where the gap is still open and scan 4 high quality undervalued stocks.
The Two REA Group Stories Investors Had To Weigh
The shares cost A$217 at the start, and anyone looking at REA Group then faced two very different stories about what came next.
The bullish view pinned a Fair Value of A$256, which served as a rough guide to what that camp thought the stock was worth, based on expectations of 7.1% annual revenue growth and profit margins rising toward 38.8% supported by higher adoption of premium listings.
The bearish case pointed instead to a Fair Value of A$132, based on slower 2.5% revenue growth and pressure on margins from tighter data privacy rules and rising technology costs.
What The REA Group Results Actually Tested
REA Group’s H2 2026 update gave the bullish story its cleanest test. Revenue moved from A$1,767.3m to A$1,976.9m, which leaned toward the growth assumptions. Profit slipped from A$708.4m to A$673m and net margin moved from 40.1% to 34.0%, which pushed back against the forecast of rising profitability. Overall, the evidence cut both ways.
The episode turned on one simple assumption: that higher sales would feed through to fatter profits. When you assess another high multiple platform, compare revenue, net income and margin side by side rather than just checking that turnover went up.
What REA Group’s Lower Price Now Asks You To Believe
REA Group trades at A$161 today, down 24.0% over the past year, while the selected Narrative’s Fair Value sits above the current price. The gap rests on a business case built around product mix, AI driven efficiency and adjacent services rather than a simple bounce in housing activity.
On that view, a buyer at today’s price would be assuming REA Group can keep lifting yield on Australian residential listings and related services faster than operating costs for several years.
"Expansion of REA Group’s premium listing tiers and add-ons, including products such as Luxe and Audience Maximiser, creates room for more granular packaging and price points that can shift mix toward higher value options and lift residential advertising revenue and segment margins over time."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Where REA Group’s Logic Points Next
REA Group turns home search activity into targeted advertising demand for property listings.
Those advertisers are really paying for focused attention on motivated audiences.
Another global business concentrates that attention across search, video and mobile screens.
Its software helps commercial customers design and measure campaigns, increasingly using artificial intelligence tools.
If housing platforms value precise reach and AI powered tools, that wider advertising and cloud engine could quietly reshape what belongs on your watchlist.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 27% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com