
Innodata (INOD) Dropped, So What Is Driving Attention Now?
Innodata (INOD) is back in focus after management highlighted strong revenue growth, improving profitability, and an outlook for at least 40% revenue expansion in 2026, tied to demand for AI data engineering services.
The recent enthusiasm around Innodata’s AI data engineering outlook contrasts with a share price that has been under pressure, with the stock down 6.63% over the last day and 14.86% over the past week. The 1-year total shareholder return has declined 33.51%, even though longer-term total shareholder returns over three and five years remain very large in absolute terms and suggest earlier investors have still seen substantial gains.
Scan beyond Innodata and see how it stacks up against other AI focused small caps with the 37 AI small caps currently catching investor attention.
So the share price has reset while Innodata’s revenue story stays loud. Do you lean into the drop now or wait for a calmer entry before putting fresh money to work?
Most Popular Narrative: 57% Undervalued
Innodata’s most followed narrative pegs fair value at $122.75 versus a last close of $52.82, so the gap between narrative and market price is wide. The implied upside rests on AI infrastructure spending, richer data work, and the idea that the current reset is more about sentiment than fundamentals.
Surging AI infrastructure spending and related capex by hyperscalers is creating a larger pool of long-term work for Innodata in model training, evaluation, and trust and safety services. This can support sustained revenue growth as more AI systems move into production.
See why 86 investors see Innodata as 57% undervalued.
Result: Fair Value of $122.75 (UNDERVALUED)
Still, the Innodata story can break if high customer concentration bites, or if that premium 50.7x P/E unwinds on any AI demand wobble.
Find out about the key risks to this Innodata narrative.
Another View: Innodata Through The P/E Lens
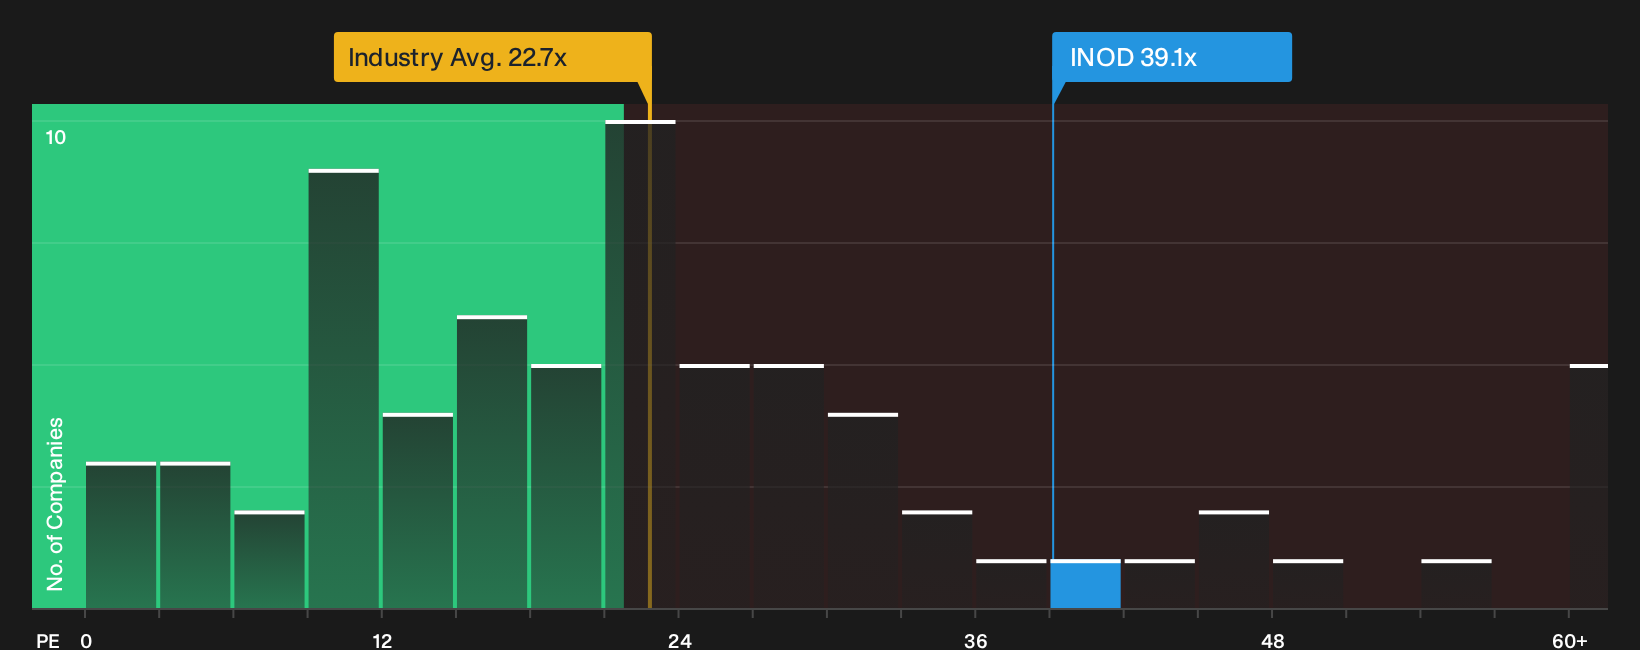
The narrative pegs Innodata at a fair value of $122.75, yet the share price already reflects a rich P/E of 39.1x. That is well above the Professional Services industry at 22.7x and peers at 21.6x, and also higher than its own fair ratio of 21.9x, which points to valuation risk if expectations cool.
Our P/E work suggests the market is paying a premium well beyond both industry and fair ratio anchors. The key question is whether you think Innodata’s AI story justifies staying at this elevated level if sentiment on growth or margins shifts.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Innodata is split between concern and optimism, and the clock is already ticking on how this AI data story evolves. Look through the key risks and potential rewards for yourself with the 3 key rewards and 1 important warning sign
Looking for more Innodata-sized opportunities?
If Innodata has sharpened your appetite for AI and high conviction ideas, do not stop here. Use the Simply Wall Street Screener to widen your opportunity set, pressure test your thesis, and avoid leaving potential winners undiscovered while others move first.
- Target potential mispricing by scanning a curated 33 high quality undervalued stocks that combine quality fundamentals with attractive valuations investors may have overlooked.
- Strengthen capital protection by focusing on companies with healthier financing and liquidity profiles using the list of solid balance sheet and fundamentals (25 results).
- Hunt for future market favorites early through the 20 high quality undiscovered gems that pair robust business metrics with lower current visibility among investors.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com