
Capital Southwest (CSWC) Posted Preliminary Q2 Results, Is A 9% Discount Enough?
Capital Southwest’s Preliminary Q2 Numbers Put Focus Back on Core Earnings
Capital Southwest (CSWC) set the stage for its upcoming earnings release by publishing preliminary operating results for the second quarter of fiscal 2027, including estimates for pre tax net investment income and net asset value per share.
Recent trading has been softer, with Capital Southwest’s share price slipping around 5% over the past 90 days even as the total shareholder return over the past year sits near 26%. This points to strong income and reinvested dividends but fading short term momentum into this preliminary update.
Scan opportunities that follow a similar income driven approach to Capital Southwest by reviewing our curated list of 8 dividend fortresses.
After a 5% slide over the past quarter but strong total return over the past year, Capital Southwest now sits in an awkward middle ground. Is this the moment to step in, or is patience better rewarded?
Most Popular Narrative: 9% Undervalued
Against the last close at $23.08, the most followed narrative puts Capital Southwest’s fair value at $25.30. This points to a modest discount that depends heavily on how consistently the lender can convert its deal pipeline into income producing assets.
Robust private equity sponsor relationships and rising lower middle market deal screens, with management reviewing roughly 1,300 opportunities over the last 12 months and committing US$762 million in FY26 plus US$222 million in Q1 FY27, support the view that Capital Southwest can keep adding income producing assets that underpin revenue and earnings.
See why 36 investors see Capital Southwest as 9% undervalued.
Result: Fair Value of $25.30 (UNDERVALUED)
Still, the case around Capital Southwest can fray quickly if spread compression deepens or if heavier at-the-market share issuance starts to cap per share outcomes.
Find out about the key risks to this Capital Southwest narrative.
Another View: What Multiples Say About Capital Southwest
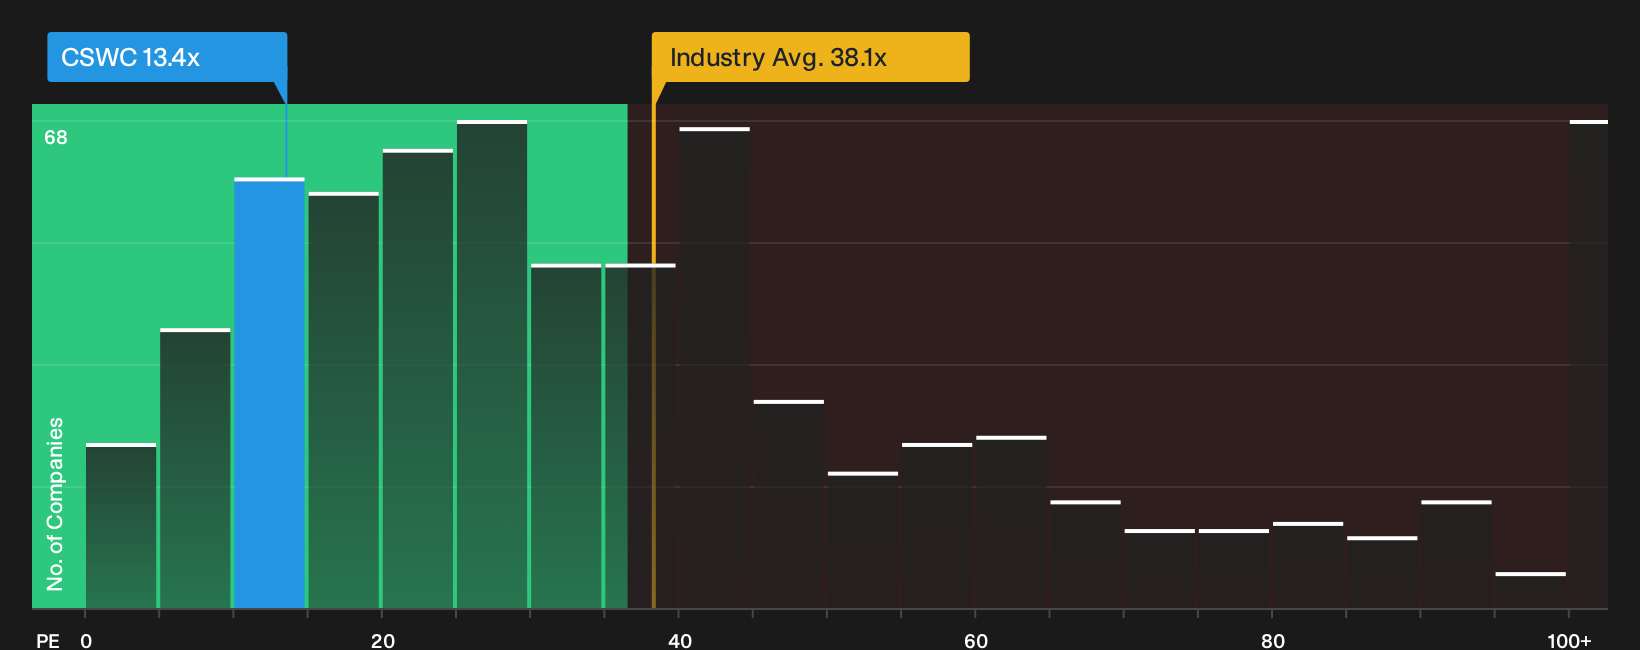
On simple P/E math, Capital Southwest looks less clear cut. The shares trade at 13.4x earnings, which is cheaper than the US Capital Markets average of 38.1x, yet more expensive than both peers at 12.4x and an estimated fair ratio of 11.2x. That gap suggests some valuation comfort against the sector, but also raises the chance that any slip in execution could compress the multiple toward the fair ratio. How much risk are you willing to accept for that kind of trade off?
For a closer look at how this pricing compares with detailed earnings assumptions and peer checks, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages run through this Capital Southwest story, which is exactly why it helps to move quickly and test the numbers yourself. To weigh the upside against the red flags, go straight to the 3 key rewards and 3 important warning signs.
Looking for more Capital Southwest style investment ideas?
If Capital Southwest has your attention, do not stop here. Use targeted screeners to surface fresh ideas before the rest of the market catches on.
- Target proven value by filtering for companies that combine quality fundamentals with pricing that still looks reasonable using the 33 high quality undervalued stocks.
- Prioritize resilience by focusing on businesses with stronger balance sheets and healthier financial profiles through the list of solid balance sheet and fundamentals (25 results).
- Hunt for overlooked opportunities by scanning a 20 high quality undiscovered gems that most investors are not paying attention to yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com