
Hitachi (TSE:6501) Could Be 13% Undervalued As Canada Factory Plan Draws Focus
Hitachi (TSE:6501) is back in focus after Hitachi Energy committed $479 million CAD to build a transformer insulation factory in London, Ontario, supported by $50 million CAD in Canadian federal and provincial funding.
Hitachi’s recent share price strength, including a 22.32% 90-day share price return and 7.41% 30-day share price return, sits alongside a 29.91% 1-year total shareholder return and a very large 3-year total shareholder return of about 25x. This points to momentum that investors appear to be linking to projects like the new Canadian facility and similar expansion efforts.
Scan other grid and infrastructure plays that may benefit from power demand and supply chain buildouts through our curated 41 power grid technology and infrastructure stocks
After a move like Hitachi has just logged, the real tension is simple: Do you accept today’s price to get exposure now, or wait and risk the valuation running further before it ever cools off?
Most Popular Narrative: 13% Undervalued
Hitachi closed at ¥5,770 against a widely followed fair value narrative of ¥6,600. This frames today’s price as leaving some upside on the table while still asking you to underwrite meaningful execution on grids and digital.
Reallocation of the portfolio toward Lumada, services and digital, alongside exits from non core assets such as the reduction of the Astemo stake and the sale of home appliances, is increasing the share of higher margin businesses like Energy services and DSS domestic IT, which targets 16 to 18% EBITDA margins by FY2027, and this mix shift can support higher group earnings and cash generation over time.
See why 23 investors see Hitachi as 13% undervalued.
Result: Fair Value of ¥6,600 (UNDERVALUED)
Still, substantial additional capital expenditures in Energy and ongoing geopolitical or tariff pressure could weaken Hitachi’s cash generation and stall the grid and digital narrative.
Find out about the key risks to this Hitachi narrative.
Another View: What Hitachi’s P/E Is Telling You
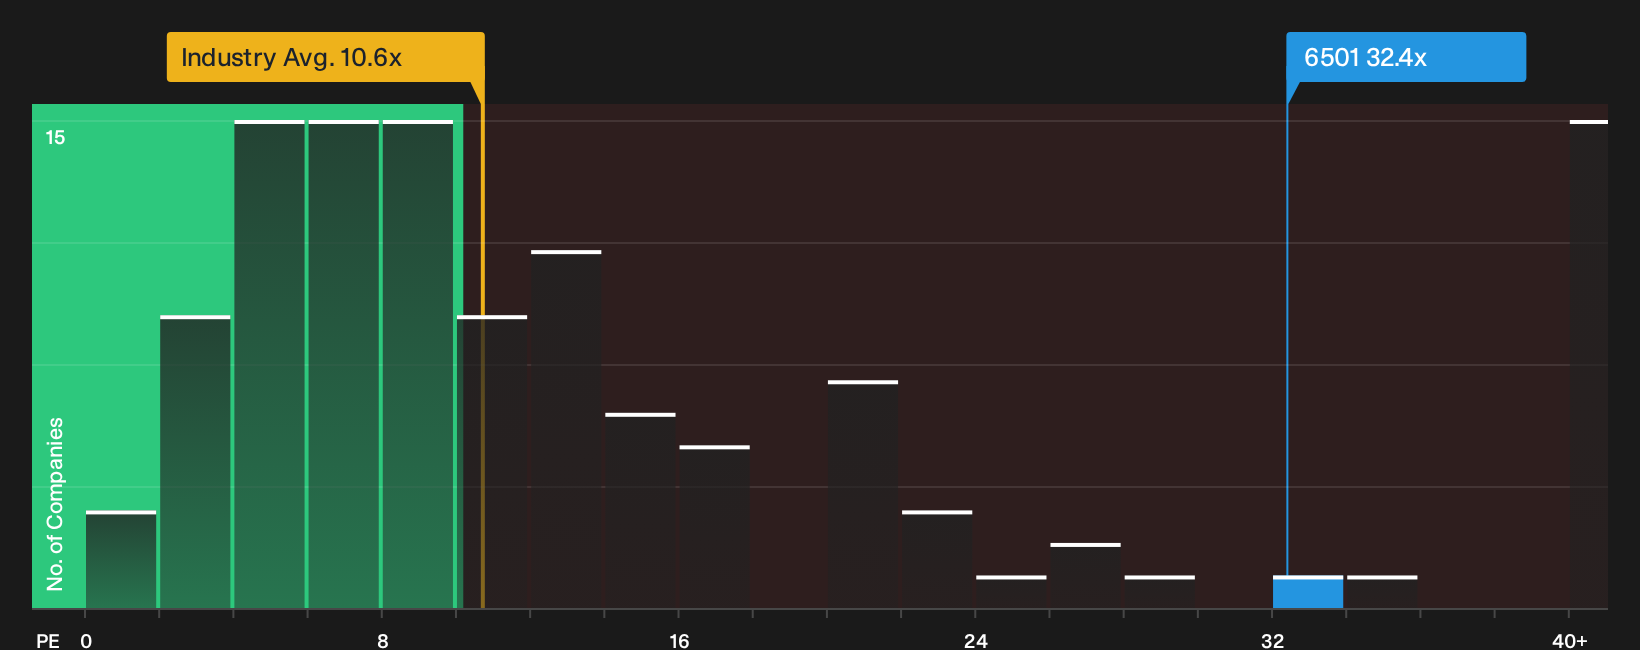
The earlier fair value of ¥6,600 leans on future cash flows. A very different picture appears when you look at Hitachi through its current P/E of 32.4x. This is far higher than both the Asian Industrials group at 10.3x and peers at 12.5x, and only slightly above a fair ratio of 32.2x. That kind of premium narrows the margin for error, so how comfortable are you paying up for this growth story?
For a closer look at how this valuation stacks up against earnings expectations and peer pricing, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of optimism and caution around Hitachi resonates, consider acting promptly and stress test the thesis against your own checklist using the 3 key rewards.
Looking for more investment ideas beyond Hitachi?
Do not stop with one opportunity. Broaden your watchlist with focused stock ideas built from the same data driven engine that surfaced Hitachi’s current valuation setup.
- Target resilience by reviewing companies with healthy finances and durable cash positions through our list of solid balance sheet and fundamentals (21 results).
- Hunt for potential mispricing by scanning the market for opportunities in our 14 high quality undervalued stocks.
- Prioritise staying power by focusing on dependable payers using our 29 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com