
Is MERLIN Properties SOCIMI (BME:MRL) A Bargain As Goldman Sachs Backs Its Data Centre Growth?
MERLIN Properties SOCIMI (BME:MRL) has drawn fresh attention after Goldman Sachs issued a buy rating, highlighting its data centre exposure in Iberia and its interest in potential project acceleration in Portugal.
Recent trading has been choppy for MERLIN Properties SOCIMI, with the share price falling 7.09% over the past 30 days and 22.42% over 90 days. However, the 3-year total shareholder return of 67.67% shows that longer term holders have still seen strong compounded gains.
Scan MERLIN Properties SOCIMI alongside other Iberian real estate and infrastructure plays by reviewing the hand picked list of solid balance sheet and fundamentals (203 results) positioned for potential data centre demand and asset resilience.
The recent slide in MERLIN Properties SOCIMI shares now sits against a sizeable discount to both analyst targets and estimated fair value. Is the market seeing real risk, or overpricing its caution, as we run the numbers next?
Preferred P/E of 8.5x: Is it justified for MERLIN Properties SOCIMI?
On the latest figures, MERLIN Properties SOCIMI trades on a P/E of 8.5x, while the share price sits at €11.66 after a period of weaker returns. Compared to both peers and the broader European REITs group, that earnings multiple points to a market that prices the stock below many listed property owners.
The P/E ratio compares what investors pay for each euro of current earnings. For a real estate and infrastructure group that generates income from offices, shopping centres, logistics assets and data centres, it is a simple way to gauge how the equity market weighs present profits against expectations for the future.
MERLIN Properties SOCIMI is flagged as good value on several fronts, with its 8.5x P/E marked as attractive relative to a peer average of 16.2x. It is also described as good value versus an estimated fair P/E of 14.8x, which points to a level the market could potentially move toward if sentiment and confidence in earnings quality improve.
The gap versus the wider European REITs industry is also wide, since that group trades on an average P/E of 12.9x against MERLIN Properties SOCIMI at 8.5x. That is a strong discount both to sector norms and to the fair ratio estimate, and suggests current pricing is more cautious than those benchmarks imply.
Explore the SWS fair ratio for MERLIN Properties SOCIMI.
Result: Price-to-Earnings of 8.5x (UNDERVALUED)
Still, MERLIN Properties SOCIMI faces pressure if Iberian commercial rents soften or data centre projects stall, which could keep that discounted P/E in place for a longer period.
Find out about the key risks to this MERLIN Properties SOCIMI narrative.
Another view on MERLIN Properties SOCIMI’s value
The story changes when you switch from the earnings multiple to cash flows. On Simply Wall St’s DCF model, MERLIN Properties SOCIMI at €11.66 is compared with an estimated future cash flow value of €29.21, which also screens as undervalued. If both signals point in the same direction, what is the market still unsure about?
Look into how the SWS DCF model arrives at its fair value.
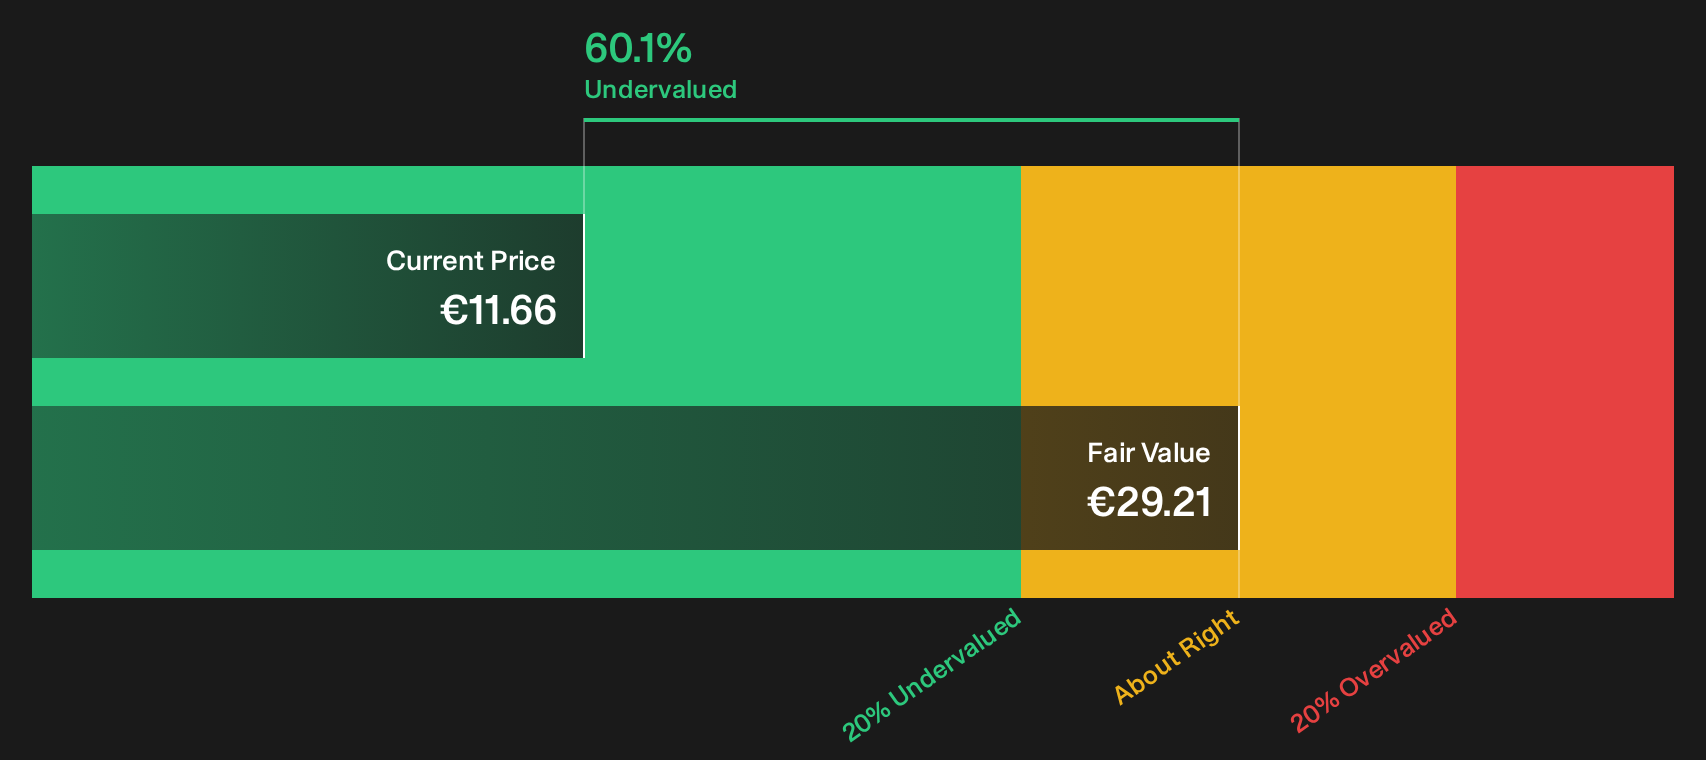
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out MERLIN Properties SOCIMI for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Neutral on MERLIN Properties SOCIMI after all this, or leaning one way already? Move quickly from headline impressions to hard data and weigh both sides of the story with the 5 key rewards and 2 important warning signs
Looking for more investment ideas beyond MERLIN Properties SOCIMI?
If MERLIN Properties SOCIMI has your attention, do not stop with one ticker. Use the screener to surface fresh opportunities before other investors start paying attention.
- Target reliable income streams by reviewing dividend-focused opportunities with the 214 dividend fortresses tailored to investors who care about consistent cash payouts.
- Hunt for mispriced quality by scanning the 618 high quality undiscovered gems that pair solid fundamentals with limited market attention.
- Prioritise capital protection by filtering companies through the 233 resilient stocks with low risk scores so potential downside is front and centre in your research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com