
How Investors May Respond To STERIS (STE) New Sanford Facility
- Steris recently confirmed plans for a 600,000 square foot facility in Sanford, North Carolina that is expected to support 335 new roles and expand its manufacturing and service footprint.
- This build out directly ties into Steris's push to scale chemistries and sterilization services, which already make up the bulk of its recurring revenue base.
- We will now look at how Steris's large Sanford chemistries expansion could reshape the investment narrative built around capacity and returns.
Scan how STERIS's expansion story compares with other capacity focused healthcare plays by reviewing our hand picked 33 healthcare AI stocks as a starting watchlist for your next idea.
STERIS Investment Narrative Recap
To own STERIS, you need to be comfortable with a capital intensive infection prevention platform that leans heavily on recurring chemistries and services. The belief is that procedure volumes and sterilization demand support the capacity being built. The Sanford expansion fits that story but does not fundamentally change the near term earnings driver, which is continued uptake of consumables and service contracts.
The largest short term swing factor is execution on these capacity projects without hurting supply reliability or margins. The biggest risk is that tariffs, US$55 million to US$70 million of restructuring tied to North Carolina, and higher capex squeeze free cash flow and compress net margins if efficiencies or pricing do not keep pace.
The Sanford announcement ties directly to STERIS already flagged US$600 million Formulated Chemistries Center of Excellence in North Carolina. Investors are watching whether this consolidation into large, automated hubs eventually supports higher volume in high margin consumables and a cleaner cost base once ramp up is complete.
In the near term, the buildout raises execution risk. Construction, transition and validation work can create timing gaps that affect shipment reliability or operating costs. For a shareholder, the key question is whether management can bring this capacity online while still managing tariffs, restructuring charges and maintaining the quality of recurring chemistries and service revenue that underpins the STERIS equity story.
What The Sanford Build Means For STERIS Consensus Targets
The analyst playbook around STERIS already bakes in steady expansion of chemistries and sterilization services, and the Sanford facility fits directly into that script. The stock is being modeled on the idea that capacity projects such as North Carolina support the earnings power analysts are penciling in for the back half of the decade.
Consensus assumptions are clear. Revenue is modeled to rise by 6.6% a year over the next three years, with profit margins moving from 13.3% today to 16.0% on roughly the same timeline. On that framework, earnings are expected to be US$805.0 million today and reach US$1.2b by about 2029, with some analysts setting their estimates as high as US$1.4b if everything goes right on utilization and mix.
For those projections to line up with current price targets, the shares would need to trade on a P/E of 26.8x those 2029 earnings compared with 25.1x today, which is above the 24.8x multiple cited for the broader US Medical Equipment group. The Sanford chemistries hub and related consolidation are effectively being treated as enablers of that step up, not as an optional side project. That is why the quality and timing of the ramp matter so much for anyone tracking the STERIS investment case.
The analysis also assumes a modest tailwind from capital returns. Forecasts call for the share count to shrink by about 0.66% a year over the next three years, reflecting buybacks layered on top of dividends. If execution on the North Carolina program lines up with this capital allocation playbook, the mix of higher margin consumables, a cleaner cost base and a slightly smaller share count could support the earnings trajectory embedded in current models.
STERIS' narrative projects US$7.3b revenue and US$1.2b earnings by 2029. This setup implies 6.6% yearly revenue growth and an earnings increase of about US$395.0 million from current earnings of US$805.0 million.
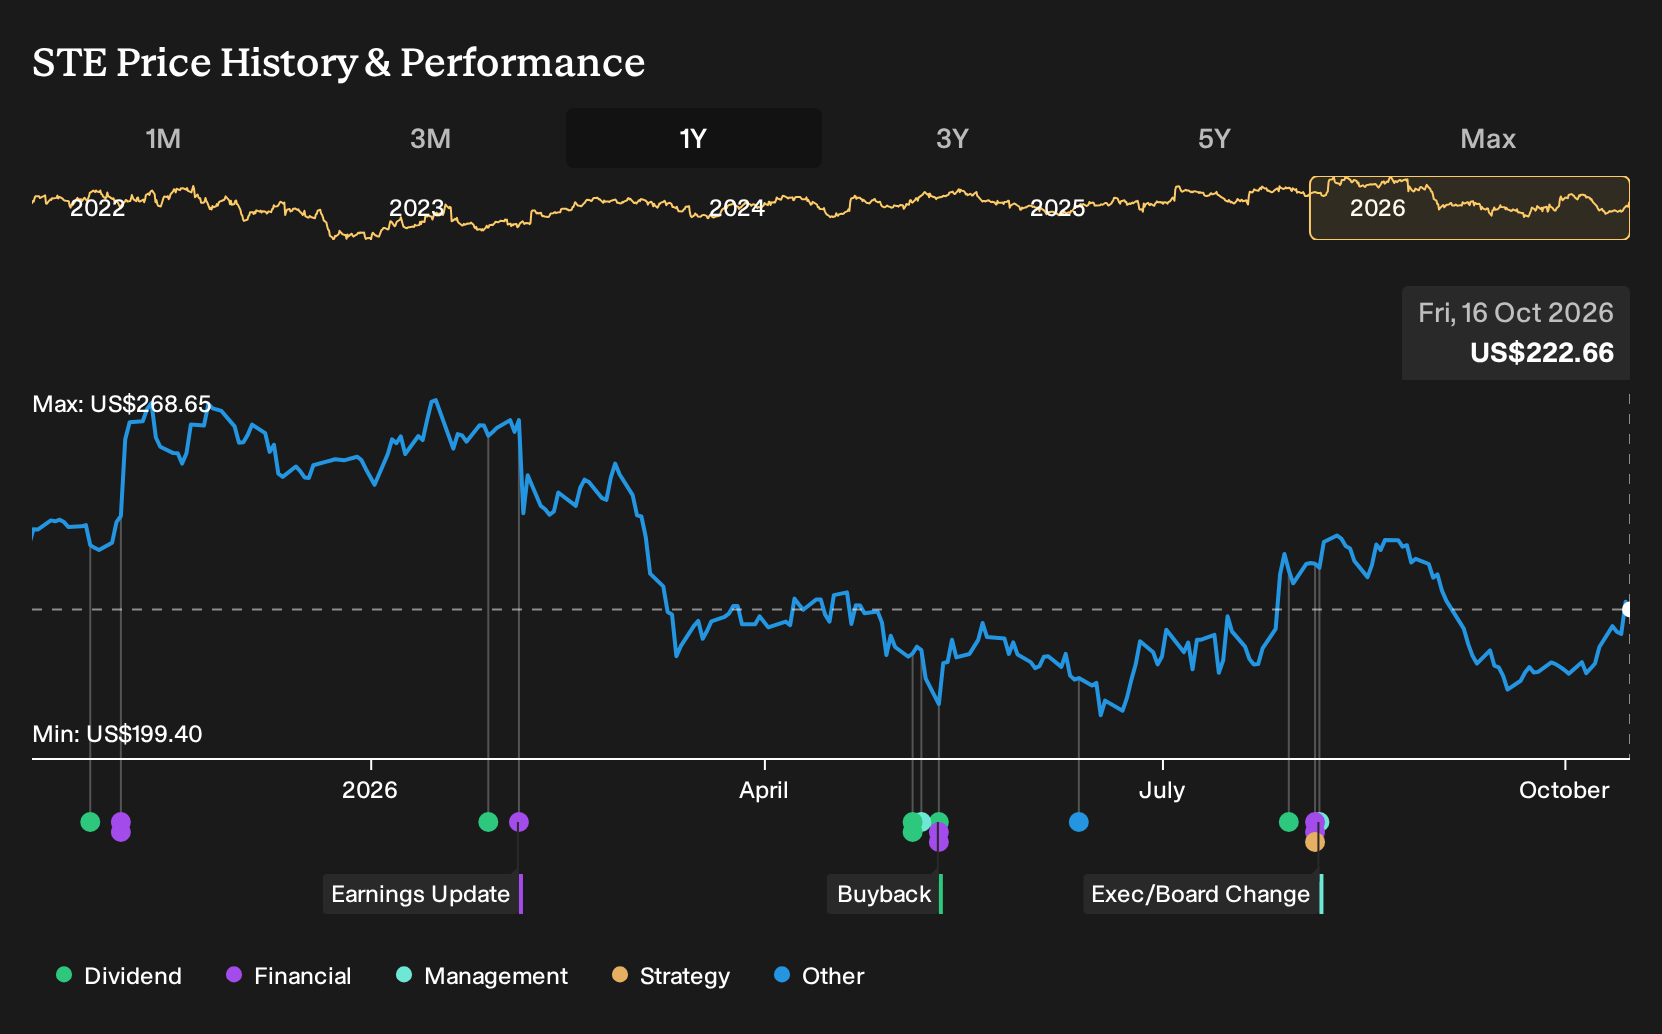
Uncover why STERIS' fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community contributes two fair value views for STERIS, spread between about US$216 and US$263. This already shows how far private estimates can stretch. Those figures pre date the Sanford expansion and do not factor in tariff costs or restructuring charges. Use these contrasting opinions as a prompt to test your own assumptions.
Explore another STERIS fair value estimate, including one that suggests a potential upside of as much as 18% from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your STERIS research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for STERIS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate STERIS' overall financial health at a glance.
Looking For More Investment Ideas Beyond STERIS?
Once you have a view on STERIS, broaden your watchlist using the Simply Wall St Screener so you can compare this story with other potential opportunities across the market.
- If you want potential upside with a margin of safety, start with our 33 high quality undervalued stocks that score well on quality and price.
- For income focused ideas, scan companies in the 8 dividend fortresses that may help you build a more dependable payout stream.
- If resilience matters most to you, filter for 32 resilient stocks with low risk scores and see which businesses line up with your risk tolerance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com