
What MTR Holders Bought Into
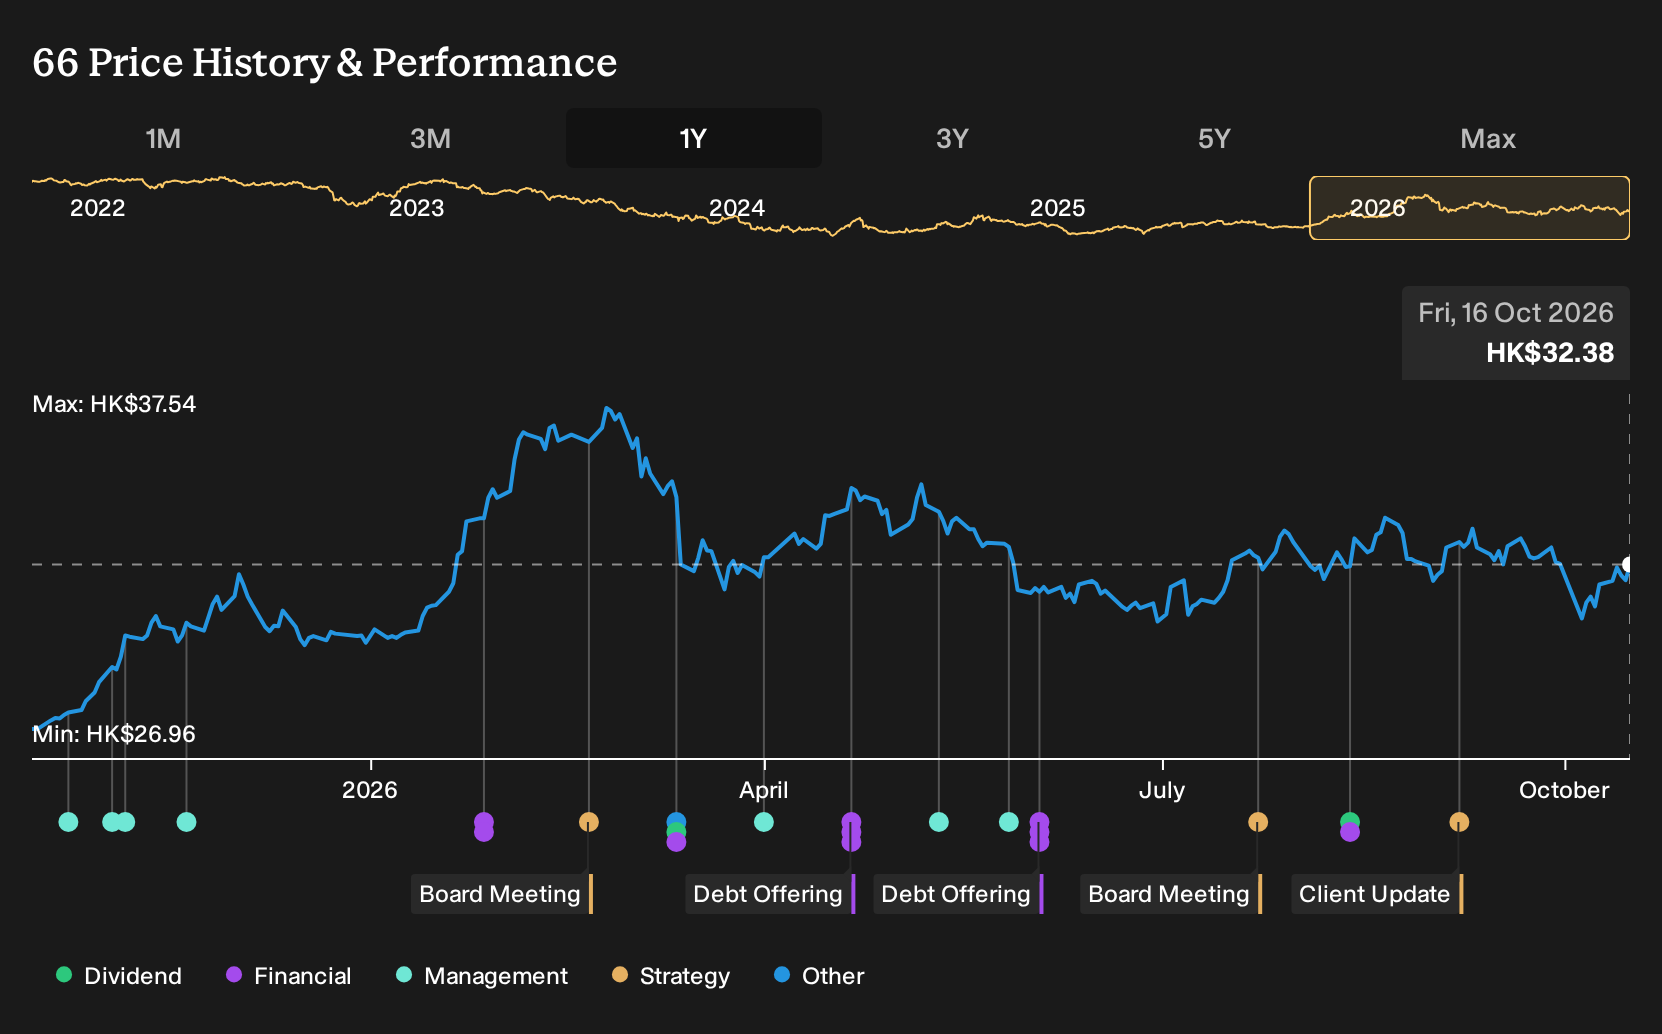
MTR looked like a grind at the starting line, with analysts split between “urban growth will pay off” and “CapEx will squeeze Hong Kong margins.” For MTR shareholders, the return over the past year was 25.1%, including dividends. If you had bought on 16 October 2025, you would now be asking a simple question: Did that payoff reflect the Parramatta metro contract and sharply higher net margin, or something more fragile in the business mix?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
This theme extends beyond MTR. See which of 41 power grid technology and infrastructure stocks may still merit a closer look.
The Argument You Would Have Been Weighing On MTR
The shares cost HK$26.96 at the start of the period, and MTR sat between two very different stories that both sounded plausible.
On the optimistic side, the bullish narrative put fair value at HK$32 and leaned on city growth and major property projects feeding recurring earnings, plus technology to improve efficiency across the rail network.
The bearish view set fair value at HK$21.8 and focused on lasting shifts in commuter habits and high capital spending as threats to Hong Kong profitability and future cash generation.
What The Results Changed For The MTR Thesis
The Parramatta metro station award, an A$880m contract shared through MTR Corporation Australia, backed the bullish idea that overseas rail work could diversify earnings beyond Hong Kong. Reported numbers told a different story on the core business mix. Revenue was HK$27,360m in H1 2025 and HK$26,231m in H1 2026, while net margin moved from 28.3% to 62.9%. Overall, that cut both ways.
The moving part that mattered was profit quality versus growth. When you assess another transport stock, compare any upbeat story about diversification with two signposts: the direction of sales, and whether the margin shift looks sustainable or one off in the next set of results.
What MTR's Price Now Asks You To Believe
With MTR at HK$32.38 today and the past year return at 25.1%, this Narrative’s Fair Value sits below the current price and frames that gap as a question about earnings quality rather than mood.
The selected Narrative argues that for today’s valuation to hold, you would need confidence that large rail and property projects can steadily cover heavy spending without leaning on irregular gains.
"The main thing that has to go right is that MTR turns its large rail expansion and Rail plus Property pipeline, including more than HK$100b of projects and thousands of housing units, into sustainable earnings that support both capital spending and dividends without relying on one off property profits."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Before The Next Story Makes Headlines
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 38% below our estimate - builds surgical robotics and implant systems that drive recurring procedure demand.
- Company 2 - 23% below our estimate - supplies advanced liquid cooling and power hardware tailored for dense AI server racks.
- Company 3 - 41% below our estimate - refocuses technology spend on digital payments, AI workflows and higher-margin branch services.
Those are three of them. See all 191 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com