
How Upgraded Earnings Outlook Will Impact Itochu Stock Investors
- ITOCHU Corp. recently received an upgraded full year earnings outlook, supported by higher consensus estimates that reflect confidence in its diversified trading and consumer focused operations.
- The upgraded projections highlight how Itochu Corp.’s downstream and non resource earnings base is gaining weight in the profit mix relative to sector peers.
- This article examines how Itochu Corp.’s investment narrative is shaped by the upgraded earnings outlook and changing consensus expectations.
Scan beyond ITOCHU and review other high quality diversified plays by exploring the hand picked 73 high quality undiscovered gems that may be flying under most investors' radar.
ITOCHU Investment Narrative Recap
To own ITOCHU, you need to be comfortable with a diversified trading group that leans more on consumer and non resource earnings while still carrying meaningful exposure to resources. The upgraded full year outlook ties directly into that story. It signals that downstream, data rich and consumer facing operations are pulling more weight in current conditions.
For the near term, the key swing factor is whether those non resource segments can offset pressure in areas like Australian coking coal, iron ore and the Finnish pulp business. The biggest risk remains earnings volatility from these resource and materials operations if recovery in projects and end markets stays slow.
The most relevant element in the recent news flow is the higher full year earnings outlook supported by rising consensus estimates. That shift reflects how ITOCHU's diversified profit base, including food, textiles, ICT and consumer related units, is tracking against earlier expectations and where the mix of earnings is heading.
For you as an investor, this matters because it touches the core catalyst: the gradual tilt toward more stable, higher margin non resource earnings. If that transition progresses while resource related headwinds such as weaker pulp or housing materials demand are kept contained, the group has more room to fund growth projects and maintain its dividend profile.
ITOCHU Consensus Expectations And Valuation Set Up
ITOCHU's latest consensus framing is quite specific. Analysts are assuming revenue will expand by 3.7% a year over the next three years, with profit margins moving from 6.0% today to 6.4% by around 2029 as the mix tilts further toward consumer and other non resource operations.
On the earnings side, the group is modeled to move from ¥910.1b in profit today to ¥1,088.8b by about 2029, which implies an increase of roughly ¥178.7b over that period. Those projections sit alongside an expectation that shares outstanding will shrink by 0.5% annually. This can support earnings per share if the forecasts play out as outlined.
To line up with the analyst case, you would need to assume ITOCHU reaches about ¥16,890.3b in revenue and ¥1,088.8b in earnings by 2029, and that the stock trades on a P/E ratio of 19.3x at that point compared with 16.4x today. That multiple would also sit above the current 10.3x P/E for the broader JP Trade Distributors group. This highlights how much of the story relies on the market assigning a premium to ITOCHU's diversified and more consumer weighted model.
ITOCHU's narrative projects ¥16,890.3b revenue and ¥1,088.8b earnings by 2029. This rests on 3.7% yearly revenue growth and an earnings increase of about ¥178.7b from ¥910.1b today.
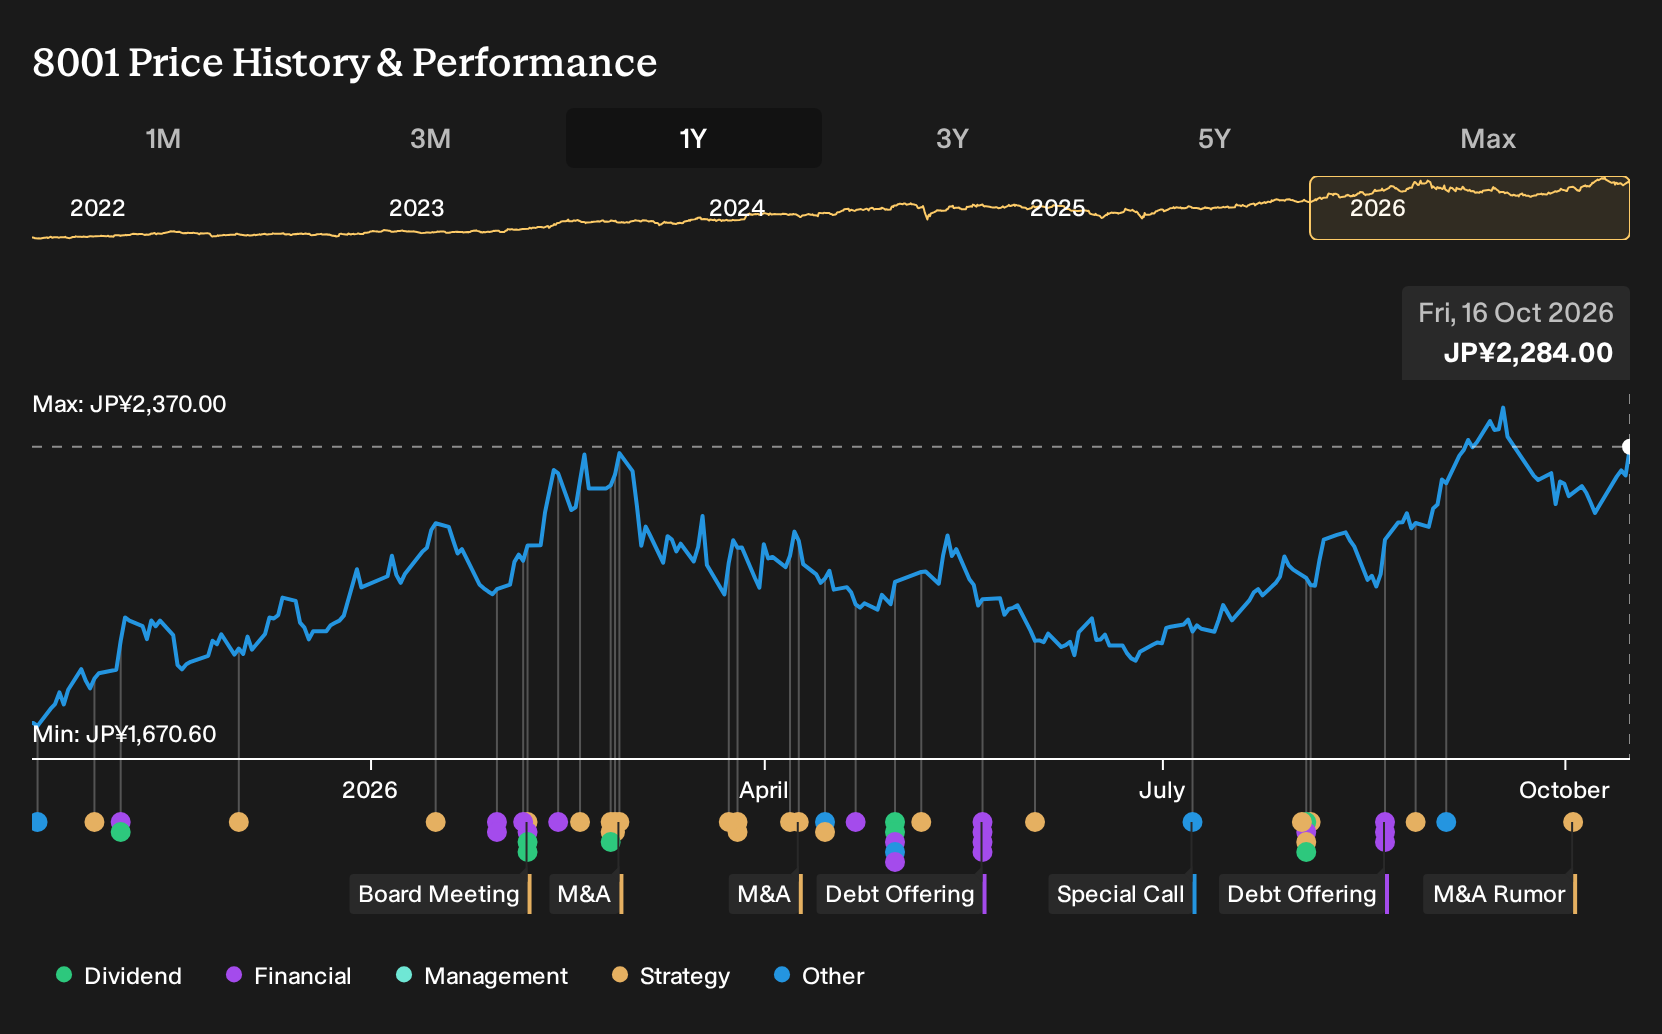
Uncover why ITOCHU's fair value indicates a potential 10% upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view centres on consumer demand risk rather than the resource swings that dominate the baseline ITOCHU story. The most cautious analysts were assuming revenue of ¥15,893.1b and earnings of ¥1,016.7b by 2029 before this earnings upgrade news, which paints a more subdued path. That gap shows how widely opinions can differ, so explore both sets of assumptions before deciding which narrative you find more realistic.
Explore 3 other ITOCHU fair value estimates, including one that suggests as much as 12% downside from the current price.
Reach Your Own Conclusion
Do not just follow the ticker; dig into the data and build a conviction that is truly your own.
- A great starting point for your ITOCHU research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ITOCHU. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ITOCHU's overall financial health at a glance.
Looking for more ITOCHU style investment ideas?
If the ITOCHU story has you thinking about portfolio upgrades, use the Simply Wall St Screener to hunt for other companies that fit the kind of risk, income, or balance sheet profile you want next.
- For investors who want potential upside with a margin of safety, review companies flagged as 14 high quality undervalued stocks based on their fundamentals and pricing.
- If resilience matters most to you, focus on businesses with lower risk scores by starting with the 22 resilient stocks with low risk scores that clear basic financial health checks.
- When you prefer stronger balance sheets and robust fundamentals, filter for financially grounded opportunities using the list of solid balance sheet and fundamentals (21 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com