
Exchange Income (TSX:EIF) The Latest Update Raises A Bigger Question
Exchange Income (TSX:EIF) just affirmed a monthly dividend of CA$0.24 per share for October 2026. This offers a fresh data point for investors watching the stock’s income profile and recent price performance.
Recent price action has been more muted, with the share price roughly flat over the past month after a decline of about 9% across the last 90 days. Even so, Exchange Income’s year to date share price return of 42% and 1 year total shareholder return of 55% still point to strong underlying momentum.
Scan for income plays with similar momentum by focusing on 3 dividend fortresses that, like Exchange Income, combine regular payouts with resilient recent share price performance.
Exchange Income now trades at a sizable discount to both analyst targets and one intrinsic value estimate, even after that 9% pullback. Is this caution from the market sensible, or has pricing swung too far?
Most Popular Narrative: 28.2% Undervalued
At a last close of CA$116.57, the most followed narrative on Exchange Income points to a fair value of CA$162.36, implying a wide gap between the current market price and that estimate.
The build out of data centers, telecommunications networks and defense and space programs is creating sustained demand for high specification precision components and engineering services, where EIC’s diversified manufacturing subsidiaries are already engaged. This can support higher capacity utilization, more stable order books and consistent earnings contributions.
See why 2 investors see Exchange Income as 28% undervalued.
Result: Fair Value of CA$162.36 (UNDERVALUED)
Still, the bullish story around Exchange Income can unravel if government and defense contracts are delayed, or if supply chain and labour pressures squeeze margins harder than expected.
Find out about the key risks to this Exchange Income narrative.
Another View: What Multiples Say About Exchange Income
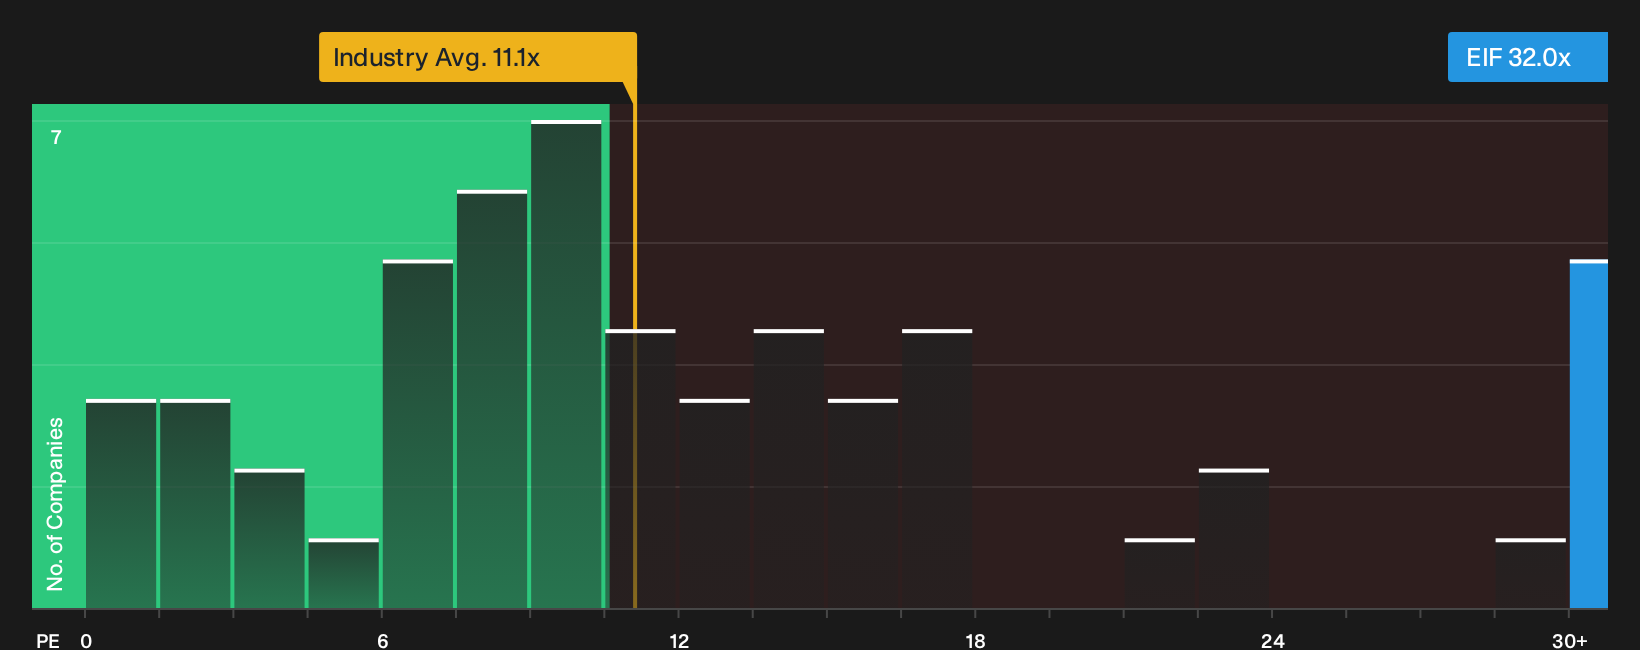
There is a catch. While the SWS DCF model flags Exchange Income as trading about 40.6% below an intrinsic value estimate of CA$196.38, the current P/E of 32x paints a much richer picture than peers.
That earnings multiple is almost 3x the Global Airlines industry average of 11.1x and well above the peer group on 20.5x. It also sits higher than the SWS fair ratio of 26.3x. This is the level the valuation could drift toward if sentiment cools. Is that premium a reasonable price for quality, or a margin of error you are not comfortable paying?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Exchange Income’s valuation and income appeal mean the only opinion that matters is yours. Move fast, pull up the numbers, and weigh both the 4 key rewards and 3 important warning signs
Looking for more investment ideas beyond Exchange Income?
If Exchange Income has sharpened your focus, now is the moment to widen your opportunity set and line up a few more contenders on your watchlist.
- Target resilient compounding potential by scanning a 3 dividend fortresses that aim to keep income flowing even when sentiment cools.
- Hunt for mispriced quality and let the 5 high quality undervalued stocks surface stocks where fundamentals and current market pricing look out of sync.
- Spot future leaders early by using a 10 high quality undiscovered gems before broader attention catches on and valuations adjust.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com