
Fraport (XTRA:FRA) Just Gave Investors Something To Think About
Fresh traffic data is back in focus for Fraport (XTRA:FRA). September figures show that Frankfurt Airport handled 6.1 million passengers, giving investors an updated read on aviation demand and the operator’s wider airport portfolio.
At a share price of €60.3, Fraport has seen a 7 day share price return of 4.96%, although the 90 day share price return is down 10.8% and the 1 year total shareholder return is down 21.06%, even after a 37.06% total shareholder return over three years, which points to longer term holders still being ahead overall.
Scan how Fraport compares with other airport and infrastructure operators by reviewing a curated set of list of solid balance sheet and fundamentals (203 results) in similar cash generative businesses.
After a quick rebound on the latest traffic data, Fraport now pits recent share price pressure against a richer pipeline of airport assets. Does that balance of risk and reward still lean toward investors at this valuation?
Most Popular Narrative: 21% Undervalued
Fraport's most followed narrative pitches a fair value of €76.30 against the recent €60.3 share price, so the story hinges on whether future cash generation can justify that gap.
Recent operational and financial results indicate a positive inflection in free cash flow, with reduced CapEx requirements and stronger operational cash generation supporting ongoing deleveraging and potentially enabling future dividend resumption, positively impacting net income and shareholder returns.
See why 8 investors see Fraport as 21% undervalued.
Result: Fair Value of €76.30 (UNDERVALUED)
Still, high leverage, alongside currency swings in markets like Turkey, could quickly test the bullish Fraport narrative if cash generation or refinancing conditions disappoint.
Find out about the key risks to this Fraport narrative.
Another View: What Fraport’s P/E Is Really Telling You
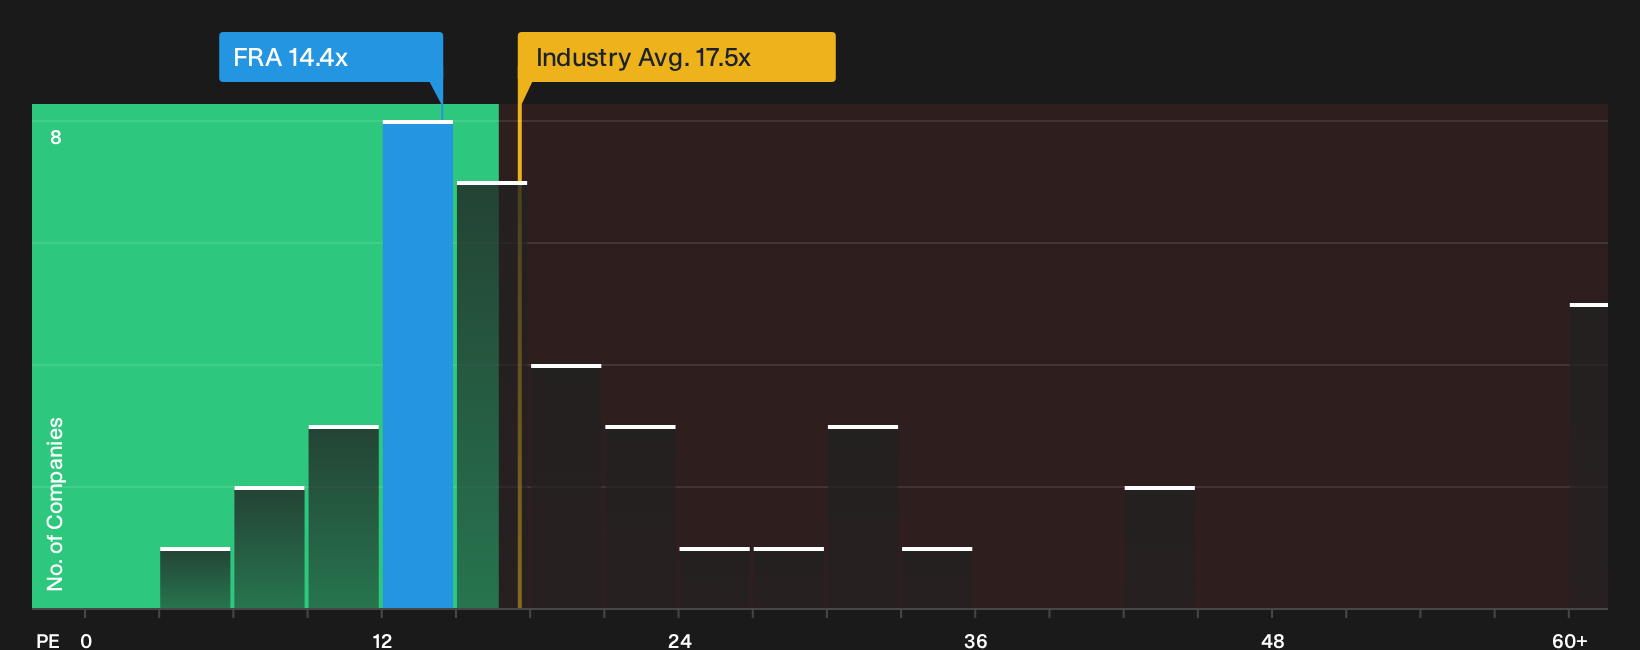
Fraport might look inexpensive compared with the wider European infrastructure group, with a P/E of 14.4x versus 17.4x. Against closer peers and a fair ratio of 14.1x though, the stock comes across as slightly expensive. That mix raises a simple question: Is the market pricing in enough execution risk?
To see how this price tag stacks up against earnings power across the sector, it is worth unpacking the valuation gap and what the fair ratio suggests about where the multiple could drift over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around Fraport's valuation and risks is clear. Move quickly, review the data in depth, and carefully weigh both 3 key rewards and 2 important warning signs
Looking for more ideas beyond Fraport?
Do not stop with one opportunity. The strongest portfolios usually blend different angles, and the Simply Wall Street Screener can surface ideas you might otherwise miss.
- Target quality at a discount by running through 191 high quality undervalued stocks that combine solid fundamentals with prices that may sit below their estimated worth.
- Strengthen your income stream by checking companies tagged as 213 dividend fortresses and see which payouts look more durable on the numbers.
- Dial down risk by scanning 233 resilient stocks with low risk scores where balance sheets and volatility scores aim to prioritise resilience over drama.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com