
Jyske Bank (CPSE:JYSK) Lifted Guidance, Is The Upside Already Priced In?
Jyske Bank (CPSE:JYSK) raised its 2026 earnings guidance after reporting third quarter results, updating investors on both recent performance and what management now expects for full year profit and earnings per share.
Jyske Bank’s guidance hike landed on a share price that has risen strongly over time, with a 90 day share price return of 7.11%, a year to date gain of 21.82% and a 1 year total shareholder return of 50.40%. This signals momentum that long term holders, who have seen total shareholder returns of 130.46% over three years and 267.70% over five years, will be watching closely as sentiment around its earnings outlook shifts.
Spot similar momentum stories by scanning our hand picked 191 high quality undervalued stocks, which combine stronger guidance, resilient earnings and balance sheet support.After a run like that and fresh guidance on the table, the real tension now sits in the valuation. Does Jyske Bank still offer enough upside to justify new risk, or is most of the reward already priced in?
Most Popular Narrative: 9% Undervalued
Against Jyske Bank’s last close of DKK 1,069, the most followed narrative points to a fair value of DKK 1,171.60, which implies a modest valuation gap built on detailed assumptions about earnings, margins and capital returns.
The current valuation assumes Jyske Bank's leading customer satisfaction and recent mortgage market share gains will persist, translating into robust core lending growth. A reversal in customer preferences or renewed competition could slow lending volumes and reduce overall earnings momentum.
See why 5 investors see Jyske Bank as 9% undervalued.
Result: Fair Value of DKK 1,171.60 (UNDERVALUED)
Still, the narrative wobbles if digital adoption disappoints or if regulators demand higher capital. This could squeeze Jyske Bank’s efficiency gains and slow buyback plans.
Find out about the key risks to this Jyske Bank narrative.
Another View: Jyske Bank Through Earnings Multiples
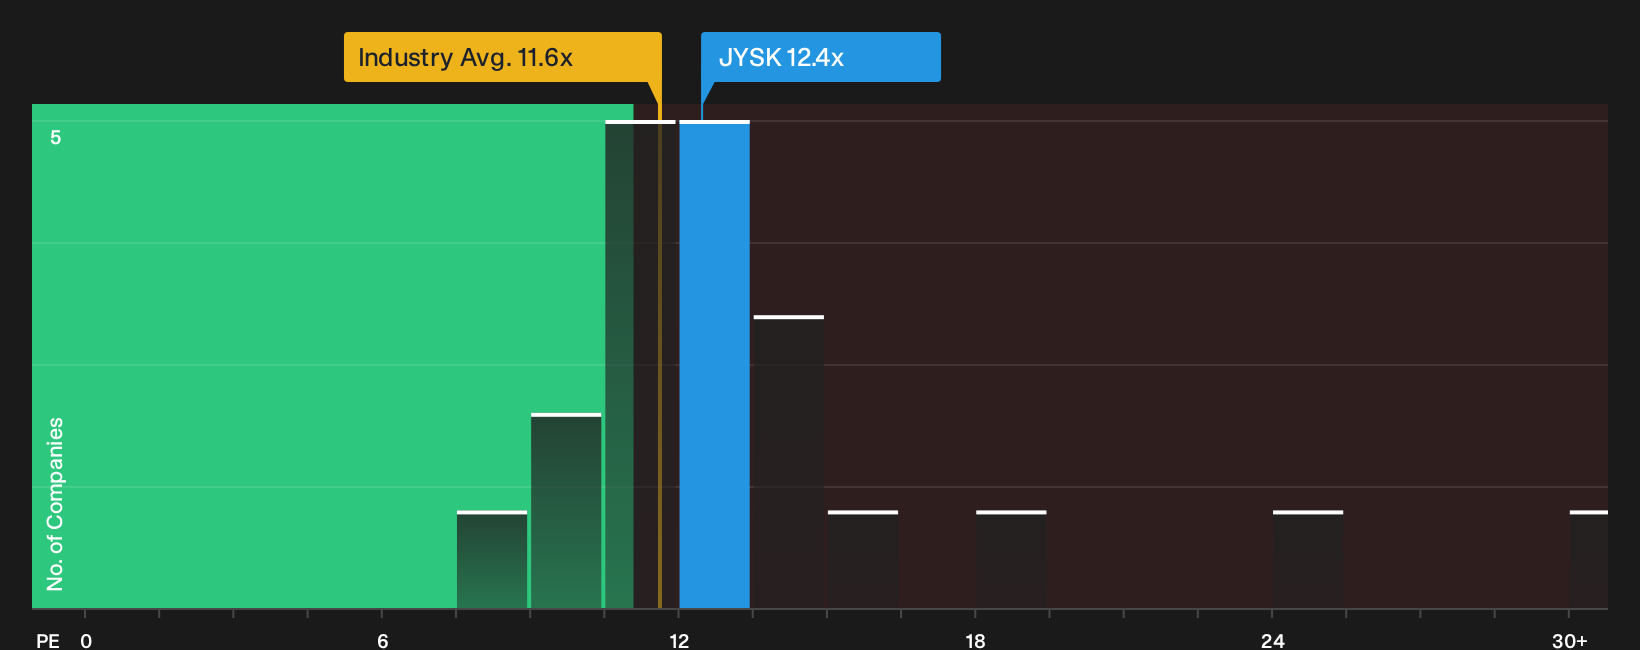
The DKK 1,069 Jyske Bank share price looks different when viewed through simple earnings ratios. On a P/E of 12.4x, the stock trades above the European banks average of 11.6x, so investors are already paying a slight premium to the wider sector.
The fair ratio for Jyske Bank is 15.1x, which sits meaningfully higher than both its current 12.4x and the peer average. If the market moves closer to that fair ratio, the current P/E could look conservative. However, if sentiment cools, that premium to the sector may feel less comfortable. Which side of that trade off do you want to be on?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
That mix of optimism and caution around Jyske Bank only matters if you put the numbers in context and test the story yourself. To move quickly from headlines to a clear personal view, weigh both sides of the ledger and start with the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Jyske Bank?
If Jyske Bank has sharpened your focus on quality and valuation, do not stop here. Broaden your watchlist now so you are not catching up later.
- Target potential mispricings by reviewing the 191 high quality undervalued stocks that combine solid fundamentals with pricing that still leaves room for a thesis.
- Strengthen portfolio resilience by using the list of solid balance sheet and fundamentals (203 results) to filter for companies with healthier debt profiles and sturdier financial footing.
- Spot future standouts early by scanning the 618 high quality undiscovered gems that pair strong financial quality with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com