
How Strong Unit Sales At Ryman Healthcare (NZSE:RYM) Has Changed Its Investment Story
- Ryman Healthcare has reported stronger unit sales, tight retirement village inventory and high care occupancy, prompting closer scrutiny of how well its current market valuation aligns with cash flows the business can generate.
- The renewed sales momentum and high occupancy focus investor attention on whether Ryman Healthcare’s operational performance now better supports its intrinsic cash flow value.
- We will now look at how Ryman Healthcare’s improved sales momentum could influence the existing investment narrative around governance and cash generation.
Scan how Ryman Healthcare’s renewed sales momentum compares with other businesses showing resilient fundamentals in our hand picked 618 high quality undiscovered gems.
Ryman Healthcare Investment Narrative Recap
To hold Ryman Healthcare, you need to believe the retirement village model can turn higher unit sales and strong care occupancy into steadier cash generation, despite past losses and heavy debt. The latest lift in unit transactions and tight village inventory supports that view because it points to better utilisation of assets already built.
The key short term catalyst is whether this renewed sales momentum turns into more consistent operating cash flow, given previous negative cash from existing operations. The main risk is that high borrowings of about NZ$2.56b and increased interest costs absorb much of that cash, limiting financial flexibility if property market conditions soften again.
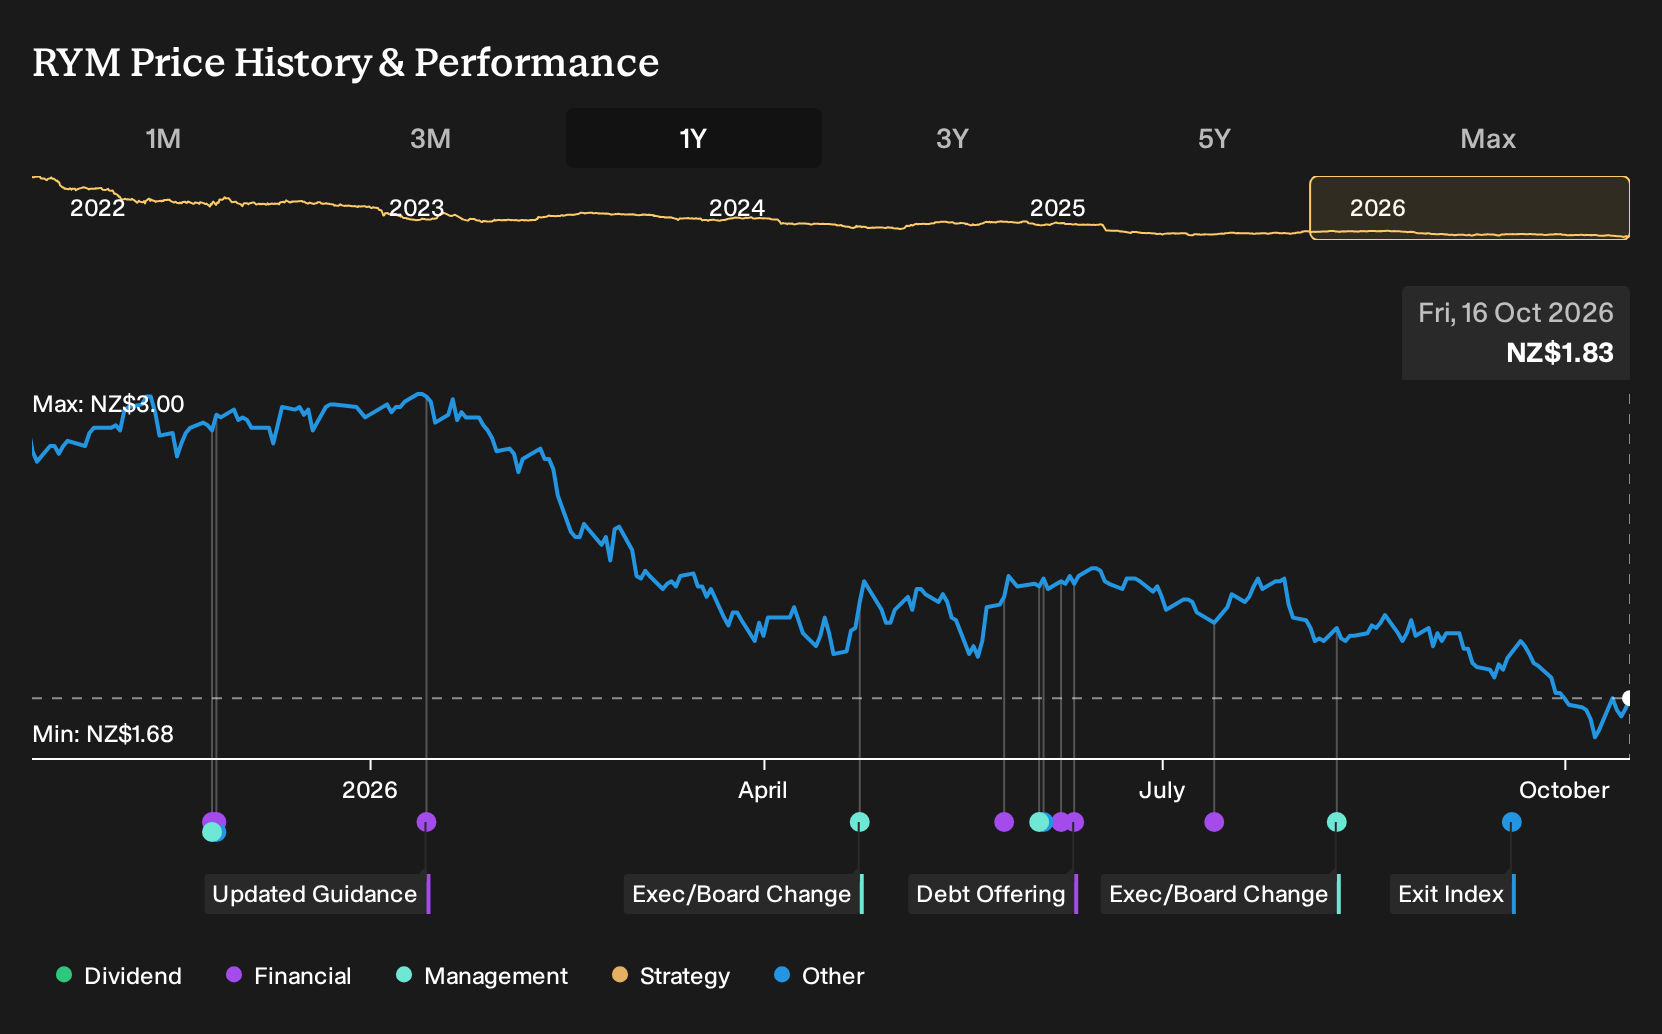
The most relevant recent development is the strength in new unit sales and ongoing high care occupancy, which has coincided with a smaller share price gain of 2% on a weak NZX 50 trading day. That move was modest, yet it suggests the market is watching how operational metrics track rather than just headline earnings.
For catalysts, this operational momentum now sits alongside Ryman Healthcare’s ongoing cost reorganisation and new pricing structure. Execution on those programs, combined with sustained demand for units and care beds, will shape whether the business can move from a reported NZ$79.8m pre tax loss and negative operating cash flow toward more durable, self funded growth.
Ryman Healthcare's narrative projects NZ$1.1b revenue and NZ$672.2m earnings by 2029. This requires 8.1% yearly revenue growth and an earnings increase of about NZ$843.5m from a current loss of NZ$171.3m.
Uncover how Ryman Healthcare's fair value indicates a 64% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Ryman Healthcare’s pricing power as the real swing factor. Before this news, they were already pencilling in revenue of about NZ$1.0b and earnings of NZ$747.6m by 2029. That is a far brighter story than consensus, and fresh sales data could shift these narratives again.
Explore 3 other Ryman Healthcare fair value estimates, including one that suggests as much as 102% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ryman Healthcare research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Ryman Healthcare. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ryman Healthcare's overall financial health at a glance.
Looking for more Ryman Healthcare style investment ideas?
If the Ryman Healthcare story has sharpened your thinking, it can help to scan a wider field of companies that fit the kind of profile you want in your portfolio.
- For investors who want quality businesses trading below what their fundamentals suggest, start by checking a focused set of 191 high quality undervalued stocks that pass a strict value and quality filter.
- If your priority is resilience when conditions turn, consider broadening your watchlist with a curated 233 resilient stocks with low risk scores that screens for companies with lower risk scores.
- For readers who care most about balance sheet strength and solid financial footing, the list of solid balance sheet and fundamentals (203 results) is a straightforward way to surface potential ideas.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com