
Learn Why The Bull Case For C&D International Investment Group Stock Could Change Following Sales Decline
- C&D International Investment Group reported unaudited nine month operating figures to 30 September 2026, with contracted sales attributable to shareholders of about RMB 65.58b and gross floor area of roughly 2.45 million square metres, both showing year on year declines.
- The drop of about 7.7% in contracted sales value and 10.9% in gross floor area suggests pressure on project sell through and overall buyer demand for C&D International Investment Group’s developments.
- Attention now turns to how C&D International Investment Group’s investment narrative absorbs weaker contracted sales momentum and what that means for expectations.
Compare C&D International Investment Group’s sales slowdown with other property developers by scanning the list of solid balance sheet and fundamentals (203 results) that may be better positioned for choppy demand.
What Is C&D International Investment Group's Investment Narrative?
The big question for a shareholder is whether C&D International Investment Group can keep turning a capital heavy development model into acceptable returns as contracted sales cool. The 7.7% decline in sales value and 10.9% drop in floor area for the nine months to September 2026 point to softer demand and potentially tougher pricing. That feeds straight into near term catalysts because revenue is forecast to decline 4.3% a year while earnings are still expected to grow 10.33% a year, which will likely require tight execution on costs and project mix.
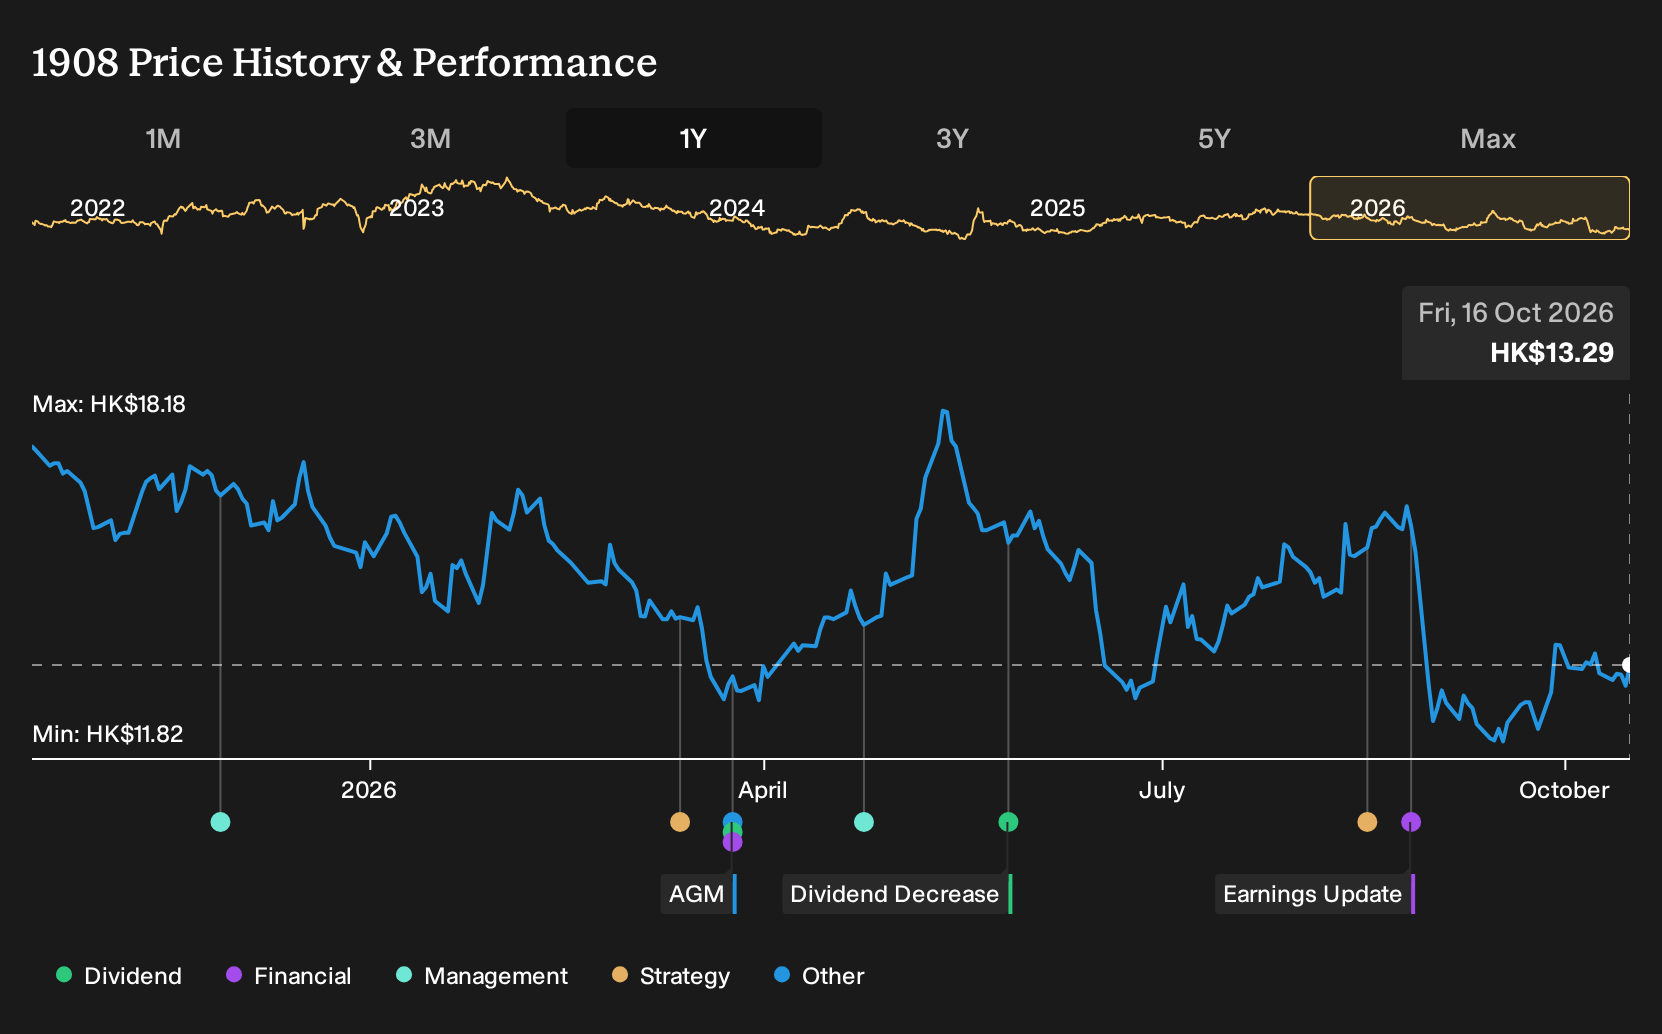
In the short term, you are essentially betting that management can work through weaker sell through without stressing a balance sheet funded entirely by higher risk external borrowing. C&D International Investment Group still screens as good value on P/E at 8.6x versus an estimated fair P/E of 11.3x, and analysts as a group see room above the current HK$13.29 share price. Recent underperformance against the Hong Kong market and lower net margins at 2.5% compared with 3% last year show how thin the cushion is if contracted sales pressure persists.
Yet one pressure point, away from sales headlines and valuation screens, sits uncomfortably close to the heart of the story...
There's only one way to know the right time to buy, sell or hold C&D International Investment Group. Head to Simply Wall St's company report for the latest analysis of C&D International Investment Group's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide band, from about HK$18.47 to HK$313.20. This shows how far apart retail views on C&D International Investment Group can be. Those opinions were formed before the recent sales update, so you may want to test your own view against several contrasting assumptions.
Explore another C&D International Investment Group fair value estimate, including one that suggests it could be worth just HK$18.47!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your C&D International Investment Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for C&D International Investment Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate C&D International Investment Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond C&D International Investment Group?
If the recent sales figures for C&D International Investment Group have you reassessing property exposure, it can help to widen the lens and compare opportunities across sectors and capital structures using the Simply Wall St Screener.
- For investors who want potential mispricing with quality traits, review a curated set of 191 high quality undervalued stocks that combine fundamentals with attractive valuations.
- If income is a priority and you care about consistency, scan a hand picked group of 213 dividend fortresses that focus on higher yields with supporting financials.
- When capital preservation ranks high on your list, filter for 233 resilient stocks with low risk scores that aim to balance return potential with more moderate risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com