
Why Everyone Is Watching Jet2 (AIM:JET2) Today
Jet2 (AIM:JET2) has extended its Tunisia holiday and flight programme into winter 2027, adding more than 32,000 extra seats after strong early bookings and widening options around key family travel periods.
For context, Jet2 shares trade at £14.11, with the 1 year total shareholder return of 7.2% contrasting with a 3 year total shareholder return of 46.1%. This suggests momentum has cooled recently, even as news like the Tunisia extension keeps investor interest alive.
Spot opportunities riding similar travel trends by scanning our hand-picked 5 high quality undiscovered gems that echo the kind of demand Jet2 is seeing on its extended Tunisia routes.So with Jet2 shares cooling after strong multi year returns, yet fresh Tunisia capacity now on sale, does the current price still offer an attractive balance of risk and reward, or has most of the easy upside already been claimed?
Most Popular Narrative: 15% Undervalued
On the most followed narrative, Jet2 is priced below an implied fair value of £16.63, which compares with the £14.11 last close and reflects a focus on disciplined execution rather than headline growth.
Robust cash generation, a conservative balance sheet, and prudent management of debt and liquidity provide the financial flexibility to compound shareholder returns via dividends and buybacks, while also insulating earnings from macroeconomic shocks.
Product diversification, expanding both the range of destinations and holiday options, and targeting younger and less affluent demographics without sacrificing quality, broadens Jet2's addressable market and supports stable, compounding revenue with a risk-mitigating customer mix.
See why 37 investors see Jet2 as 15% undervalued.
Result: Fair Value of £16.63 (UNDERVALUED)
Still, the narrative can crack if Jet2 faces sharper price competition in UK flight markets, or if rising fuel and environmental costs squeeze already thin margins.
Find out about the key risks to this Jet2 narrative.
Another View: Cash Flows Tell A Tougher Story
The earlier Jet2 narrative leans on earnings and a £16.63 fair value, yet the SWS DCF model points in a very different direction. On that lens, estimated future cash flows support only about £2.78 per share, which suggests the current £14.11 price embeds a lot more optimism than the cash assumptions do.
Our DCF output is only as good as the inputs, but when one framework flags Jet2 as undervalued and another points to a large gap the other way, it is worth asking which set of expectations feels closer to your own Look into how the SWS DCF model arrives at its fair value..
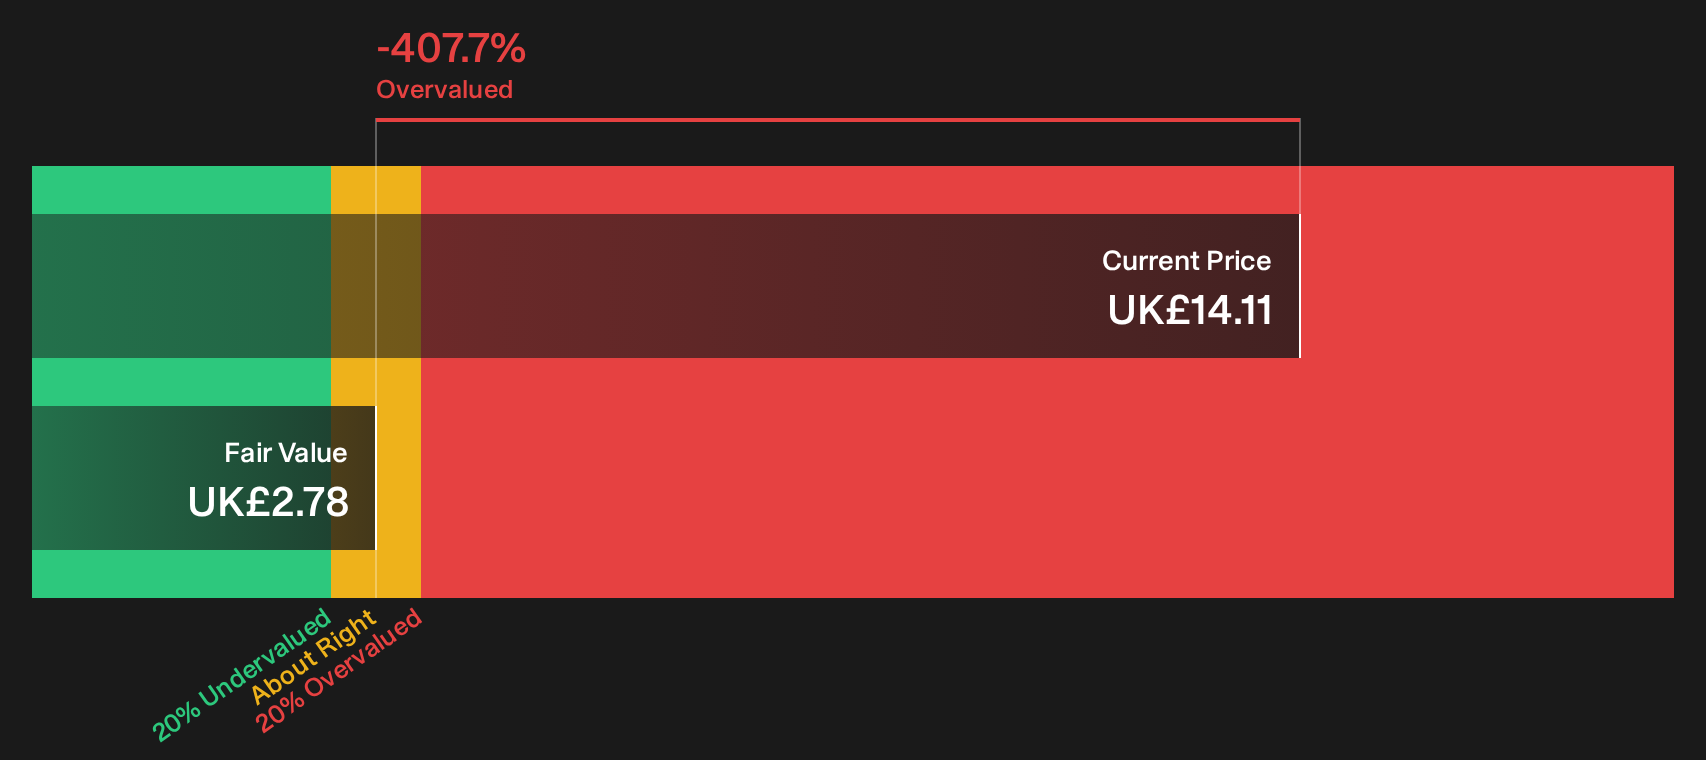
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Jet2 for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages from Jet2's valuation and cash flow models make this a moment to move quickly, stress test the assumptions, and weigh both enthusiasm and caution through the lens of 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Jet2?
If you stop with Jet2, you risk missing other shares that fit your style. Put a few minutes into scanning fresh ideas with the Simply Wall Street Screener.
- Target reliable income streams by reviewing companies built around steady shareholder payouts through the 2 dividend fortresses.
- Hunt for quality at a sensible entry point by focusing on financially strong businesses that appear mispriced in the 7 high quality undervalued stocks.
- Zero in on resilience first by filtering for businesses with robust financial footing and cleaner risk profiles in the list of solid balance sheet and fundamentals (9 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com