
What Just Happened With Zhaojin Mining Industry (SEHK:1818)?
Zhaojin Mining Industry (SEHK:1818) just released earnings for the nine months to September 30, 2026, reporting higher sales of CN¥13,510.27 million while net income eased to CN¥1,969.51 million.
The latest earnings report landed alongside a sharp reset in sentiment, with Zhaojin Mining Industry’s share price down 14.36% over the past month and 42.98% year to date, even though the three and five year total shareholder returns of 68.11% and 223.94% remain firmly positive.
Scan beyond Zhaojin Mining Industry’s mixed nine month update and size up other precious metal producers with the 36 elite gold producer stocks, which screens for scale and balance sheet quality.
Bulls see Zhaojin Mining Industry’s pullback as a chance to buy a growing producer at a discount. Bears focus on softer profits and sentiment. Which story do the current valuation numbers lean toward?
Price-to-Earnings of 15.5x: Is it justified?
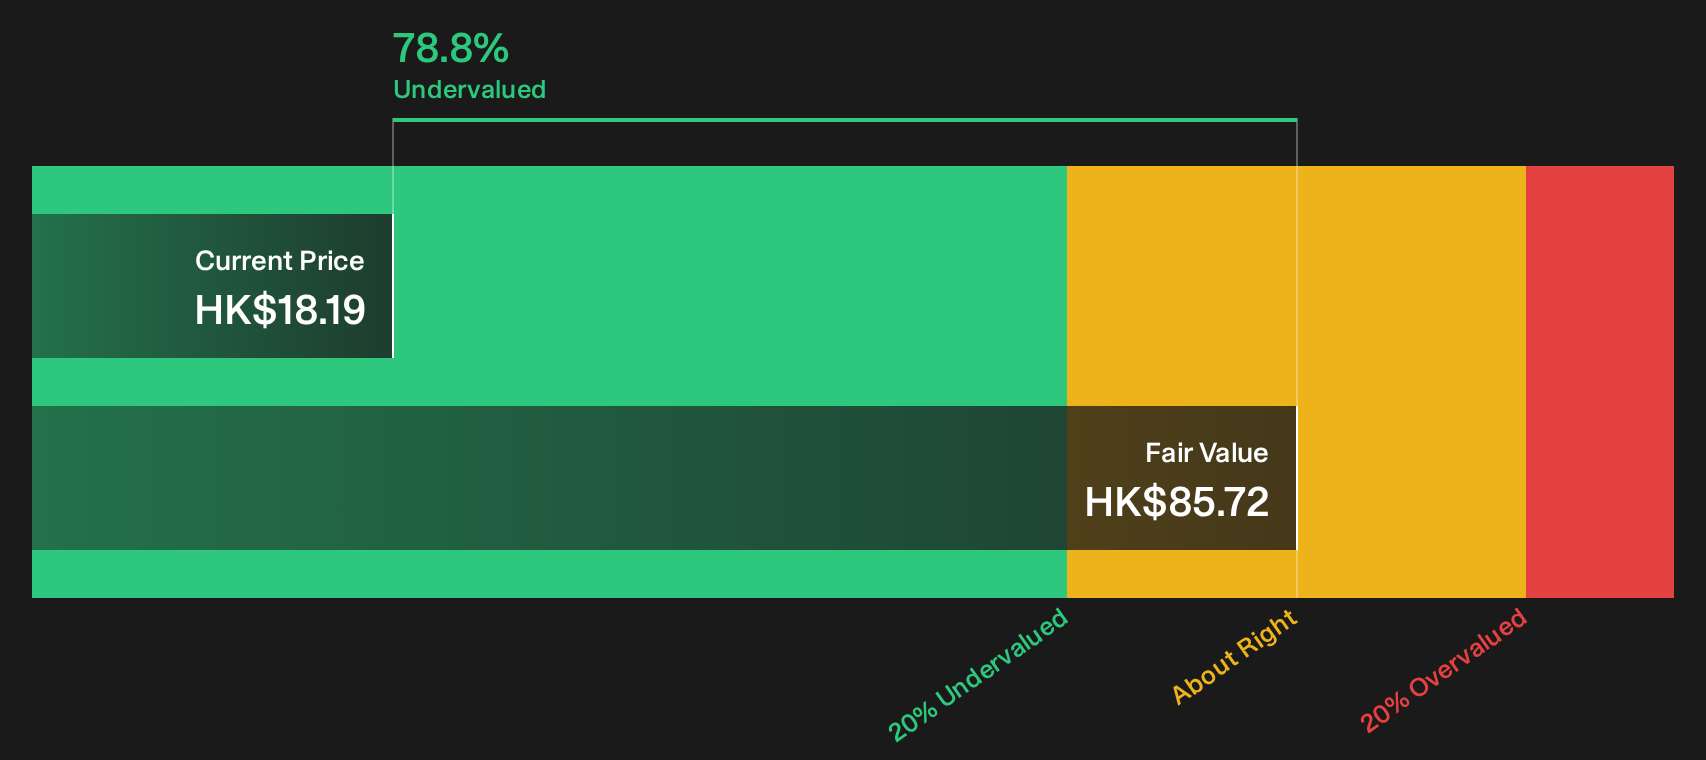
On the latest numbers, Zhaojin Mining Industry trades on a P/E of 15.5x, while our DCF work suggests a fair value of HK$85.72 against a last close of HK$18.19. That mix of signals leaves you weighing a premium earnings multiple against a large implied discount to projected cash flows.
The P/E ratio compares what investors pay today for each unit of earnings to what the business currently generates. For a precious metals producer like Zhaojin Mining Industry, that figure often reflects how the market weighs factors such as earnings quality, growth forecasts and exposure to commodity cycles.
Here, the stock is described as expensive against several benchmarks. The current P/E of 15.5x is higher than the estimated fair P/E of 14.6x that our fair ratio work points to as a level the market could move towards. The same 15.5x P/E is also higher than the Hong Kong Metals and Mining industry average of 9.1x and above the peer group average of 12.7x, which signals investors are paying a clear premium compared to similar miners.
Explore the SWS fair ratio for Zhaojin Mining Industry.
Result: Preferred multiple of Price-to-Earnings of 15.5x (OVERVALUED)
Still, the sharp 43% year to date share price slide and softer nine month net income leave Zhaojin Mining Industry exposed if sentiment weakens further.
Find out about the key risks to this Zhaojin Mining Industry narrative.
Another View on Zhaojin Mining Industry’s Value
The SWS DCF model points in a very different direction. It estimates Zhaojin Mining Industry’s fair value at HK$85.72 per share, compared with the current HK$18.19 price, which appears deeply undervalued on this framework. So which signal do you trust more: earnings multiple or cash flow value?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Zhaojin Mining Industry for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or clear message? Sentiment around Zhaojin Mining Industry is split, so move quickly, review the full picture and weigh the 3 key rewards.
Want more ideas beyond Zhaojin Mining Industry?
If Zhaojin Mining Industry has you rethinking where your money works hardest, do not stop here. Cast a wider net now and keep potential outperformance on your radar.
- Target stability first by hunting for companies that show resilience with a 233 resilient stocks with low risk scores and avoid letting hidden volatility catch you off guard.
- Prioritise quality at a sensible entry point by scanning a 618 high quality undiscovered gems that the crowd has not piled into yet.
- Focus on financial strength by filtering for businesses on the list of solid balance sheet and fundamentals (203 results) so weak balance sheets do not quietly erode your returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com