
Top 3 Japanese Defensive Stocks To Watch In October 2026
When the US posts a projected budget deficit of almost US$2t for 2026 and interest costs hit US$1.1t, higher global borrowing costs stop being an abstract headline and start shaping your portfolio risk. Japanese low risk leaders with stronger balance sheets and steadier risk profiles can look especially appealing when volatility in bonds and currencies flares up. This article highlights three such stocks from our low risk screener.
The three Japanese low risk leaders in this article are only a starter set, since the full screen surfaced 19 more companies with equally compelling narratives that are not covered below. To identify your own highest conviction foundations, head straight into the Low Risk Leaders screener to filter, analyze, and focus on the balance sheets and risk profiles that fit your portfolio best.
ASICS (TSE:7936)
ASICS is a Kobe based sportswear group that sells running shoes and athletic apparel under the ASICS and Onitsuka Tiger brands, a recurring footwear and clothing line well suited to a Low Risk Leaders foundation theme. It generated ¥278.6b in Europe, ¥211.1b in Japan, ¥162.0b in North America, and has a market value of about ¥3.2t.
For a portfolio anchor, ASICS offers a global, repeat purchase product line in running shoes and sportswear, backed by a sizeable market cap and healthy cash generation that supports both dividends and buybacks. The real test will be how one quiet pressure on its pricing power develops from here.
That pricing pressure question makes the DCF valuation analysis for ASICS a useful next step for seeing how sensitive the ASICS story is to even small margin shifts.
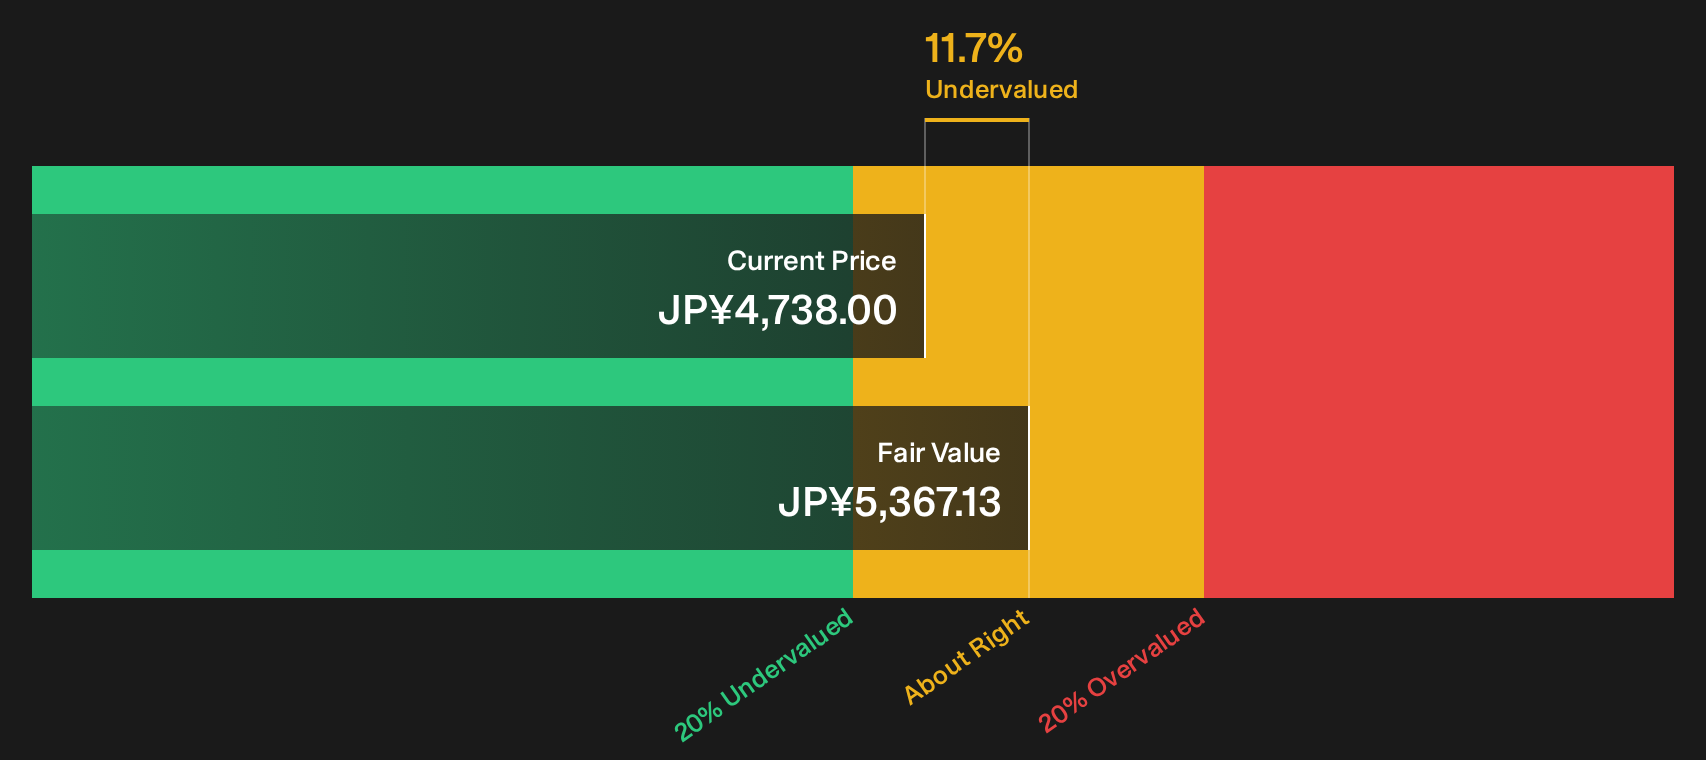
Sansan (TSE:4443)
Sansan runs a cloud platform that lets corporates share business card data, online interactions, and meeting history across teams, anchoring recurring subscription income that fits the Low Risk Leaders theme. Its Sansan and Bill One segment brings in about ¥48.9b, with Eight contributing ¥7.1b, all from Japan, and the stock is valued at roughly ¥251.5b.
Sansan combines a recurring SaaS contact platform, a ¥48.9b Sansan and Bill One segment, and a ¥251.5b market value into a profile that many investors may view as suitable portfolio ballast. The focus is on how that stability might change if a single assumption about future earnings strength shifts.
If that assumption is wrong, the analysis report for Sansan can show where Sansan’s subscription engine could diverge from expectations.

Tsugami (TSE:6101)
Tsugami is a Tokyo based manufacturer of precision CNC machine tools that help clients run stable, repeatable production lines, a clear fit with the Low Risk Leaders focus on dependable foundations. It generates about ¥122.2b in China, ¥29.8b in Japan, and ¥7.3b in India, and carries a market value near ¥242.6b.
Tsugami combines precision machine tools that support long equipment lifecycles with a high quality financial profile, including 53.6% earnings growth over the past year, 16% annualised over five years, a 23.2% ROE and a dividend yield of 1.87%. For a foundation style holding, the most important swing factor is what happens if a single unseen pressure on that earnings engine shifts.
When that earnings engine starts to shift, the 3 key rewards and 1 important warning sign can help you see whether Tsugami’s current strengths are masking a bigger turning point ahead.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. By the time every screen lights up, the cleanest setups can already be gone. Scan these focused lists while it matters and get in early.
- Target cash rich balance sheets before they get crowded by running a quick pass through the list of solid balance sheet and fundamentals (21 results) and spotting the quiet compounders under the radar for now.
- Catch early AI momentum while prices still lag the story by scanning the 39 profitable AI stocks that aren't just burning cash that already produce real earnings instead of burning cash.
- Position ahead of potential power grid upgrades by reviewing the curated 41 power grid technology and infrastructure stocks and tracking which operators could benefit if infrastructure spending accelerates.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com