
Will Preliminary Sales Update Change Rakus Stock Narrative
- Rakus Co., Ltd. reported preliminary consolidated sales of JPY 4,928 million for September 2026, giving investors a fresh read on recent business activity.
- The monthly disclosure of JPY 4,928 million in sales highlights how frequently Rakus updates the market on its underlying operating trends.
- Next, the focus shifts to how Rakus's latest JPY 4,928 million September sales figure relates to its broader investment narrative and appeal.
What Is Rakus' Investment Narrative?
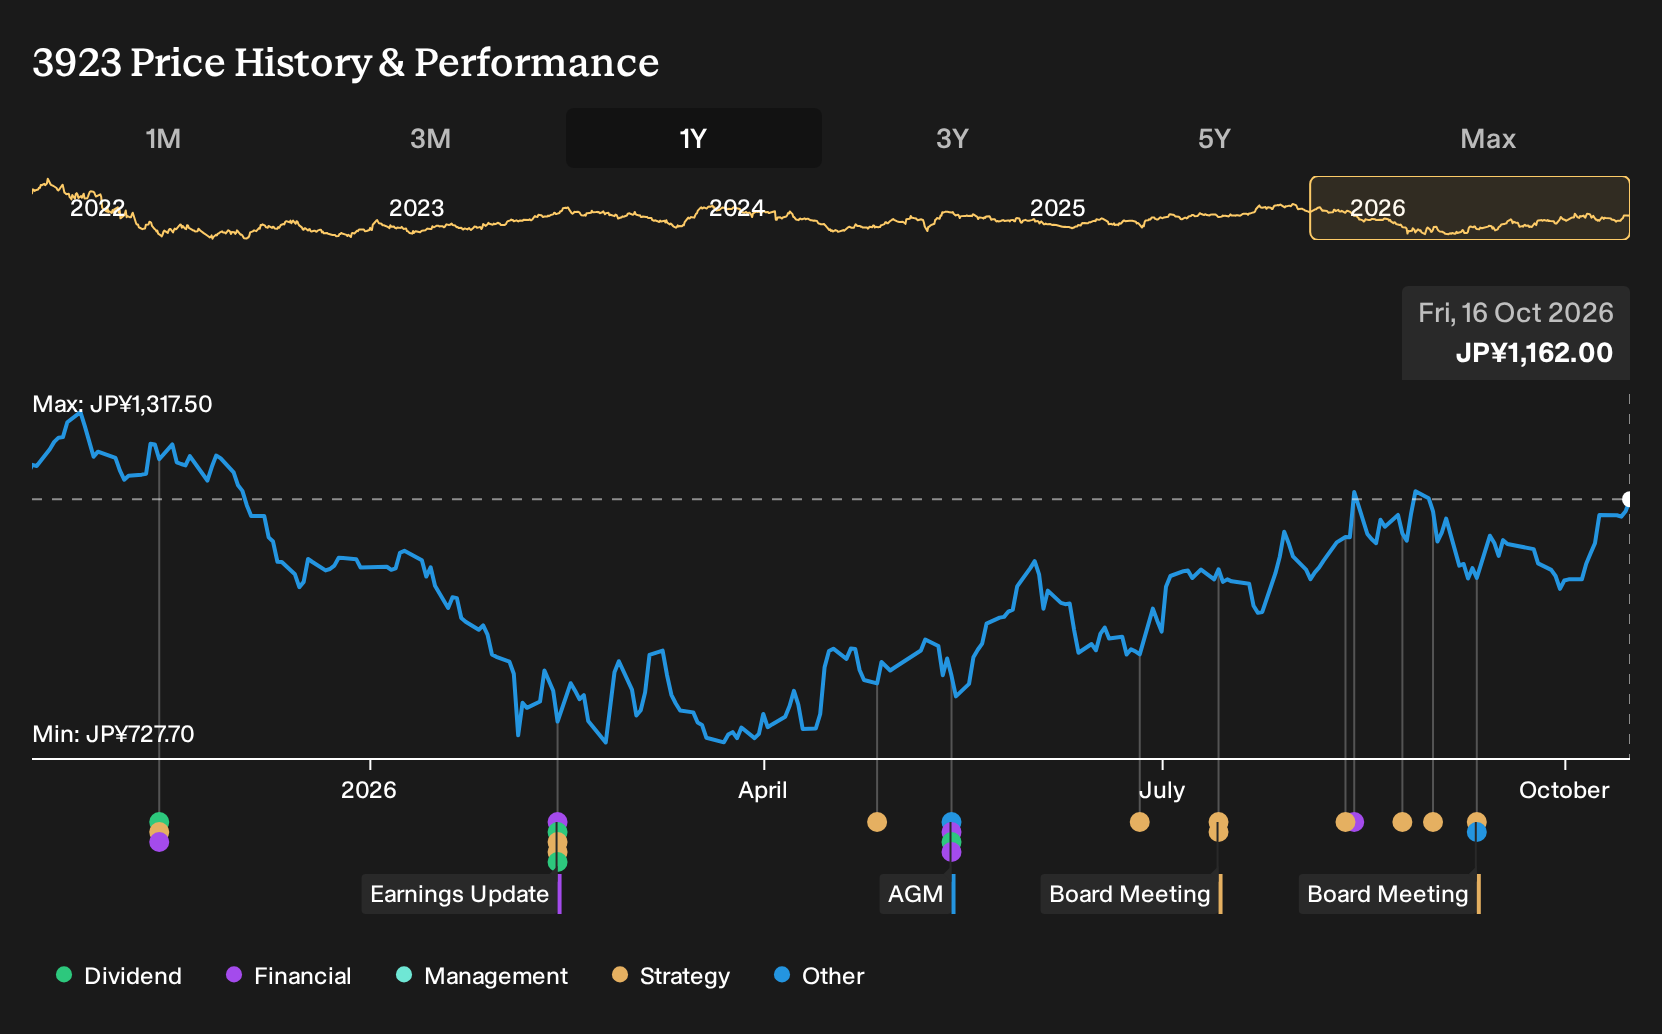
To own Rakus, you have to buy into a fairly simple idea. This is a software group trying to convert recurring cloud demand in Japan into steady, high margin earnings, while keeping capital needs light and pricing power intact. The September sales print of ¥4,928 million slots into that story as another datapoint on day to day execution rather than a clear new inflection. Recent share gains over 1 week, 1 month, and 3 months suggest traders are already reacting to this operational backdrop.
The more interesting piece for a potential shareholder is how that monthly revenue rhythm interacts with a business that has very high recent earnings growth, strong return on equity, and a P/E of 16.9x that screens as good value versus peers. In the short term, the key swing factors still look operational. Can Rakus keep landing and expanding cloud customers in Japan while managing any lumpiness from large one off items in past results and a share price that has been volatile relative to the JP market? The September disclosure helps you judge that execution in real time, but it does not rewrite the main risk reward equation on its own.
Even so, there is a quieter detail in Rakus' profile that could matter far more once you look at ...
There's only one way to know the right time to buy, sell or hold Rakus. Head to Simply Wall St's company report for the latest analysis of Rakus's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community only submits two fair value views for Rakus, yet they span a wide band from about ¥1,221 to ¥2,083 per share. That spread underlines how far opinions can diverge. These estimates also pre date the September JPY 4,928 million sales update, so you may want to weigh the fresh trading statement against those earlier assumptions and explore several alternative viewpoints before forming your own stance.
Explore another Rakus fair value estimate, including one that suggests potential upside of up to 79% from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Rakus research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Rakus. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rakus' overall financial health at a glance.
Looking For More Ideas Beyond Rakus?
If Rakus has sharpened your focus on recurring earnings, balance sheet strength, and valuation discipline, then it can help to line those themes up against other companies too. The Simply Wall St Screener gives you a simple way to compare that ¥4,928 million sales context with a wider set of listed businesses and stress test your thesis across different sectors and risk levels.
- If you want a wider pool of potential upside candidates with robust fundamentals, scan a curated set of 73 high quality undiscovered gems that share an emphasis on quality and financial resilience.
- If capital preservation matters just as much as return, filter for 22 resilient stocks with low risk scores that score well on factors such as earnings stability and balance sheet strength.
- If dependable finances are your starting point, focus your research on a list of solid balance sheet and fundamentals (21 results) and use it as a watchlist of companies to study next.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com