
W.T.B. Financial (WTBF.B) Reports Higher Earnings, Is The Stock Above Fair Value?
W.T.B. Financial (WTBF.B) just released third quarter and nine month 2026 earnings, reporting higher net interest income, net income, and earnings per share compared with the same periods a year earlier.
The earnings update landed alongside a share price that has climbed 12.87% over the past 90 days and delivered a 24.39% year to date share price return, while W.T.B. Financial’s 1 year total shareholder return of 46.86% points to stronger longer term momentum than the recent 30 day pause suggests.
Scan for other bank stocks showing similar earnings momentum and price strength using the hand picked 32 resilient stocks with low risk scores as a starting universe.
Bulls point to rising earnings and a strong 1 year return at W.T.B. Financial. Bears focus on the quieter last 30 days and a low value score. Which side does the current valuation support?
Price-to-Earnings of 9.3x: Is it justified?
W.T.B. Financial trades on a P/E of 9.3x at a last close of $460.23, which points to a lower earnings multiple than many peers and the wider US market.
The P/E ratio compares the share price to earnings per share, so for a bank like W.T.B. Financial it effectively reflects what investors are willing to pay for each dollar of current profit. For established lenders, this metric often captures how the market weighs profitability, perceived risk, and growth potential.
Here, the business scores a value rating of 2, yet its P/E of 9.3x screens as good value against both the US market average of 18.2x and the US Banks industry average of 11.4x. That combination, alongside earnings growth of 72.8% over the past year and higher net profit margins of 25.6% compared with 18.8% a year earlier, suggests investors are not assigning a premium multiple to those recent results.
Against the banking peer group, W.T.B. Financial trades on a meaningfully lower P/E than the 14.7x peer average, which is comparative evidence that the stock is priced more conservatively despite earnings growth that has exceeded the broader Banks sector over the past year.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 9.3x (UNDERVALUED)
Still, the recent 30 day pause in the share price and a value score of 2 suggest that expectations around W.T.B. Financial could reset quickly.
Find out about the key risks to this W.T.B. Financial narrative.
Another View: Our DCF Model Flags a Premium Price
The P/E suggests W.T.B. Financial looks inexpensive, yet the SWS DCF model points the other way. At a share price of $460.23 and an estimated future cash flow value of $345.60, the stock screens as overvalued on this second yardstick.
This gap matters. A rich price versus our DCF estimate can limit room for error if earnings momentum cools or if sentiment toward regional banks softens.
Look into how the SWS DCF model arrives at its fair value.
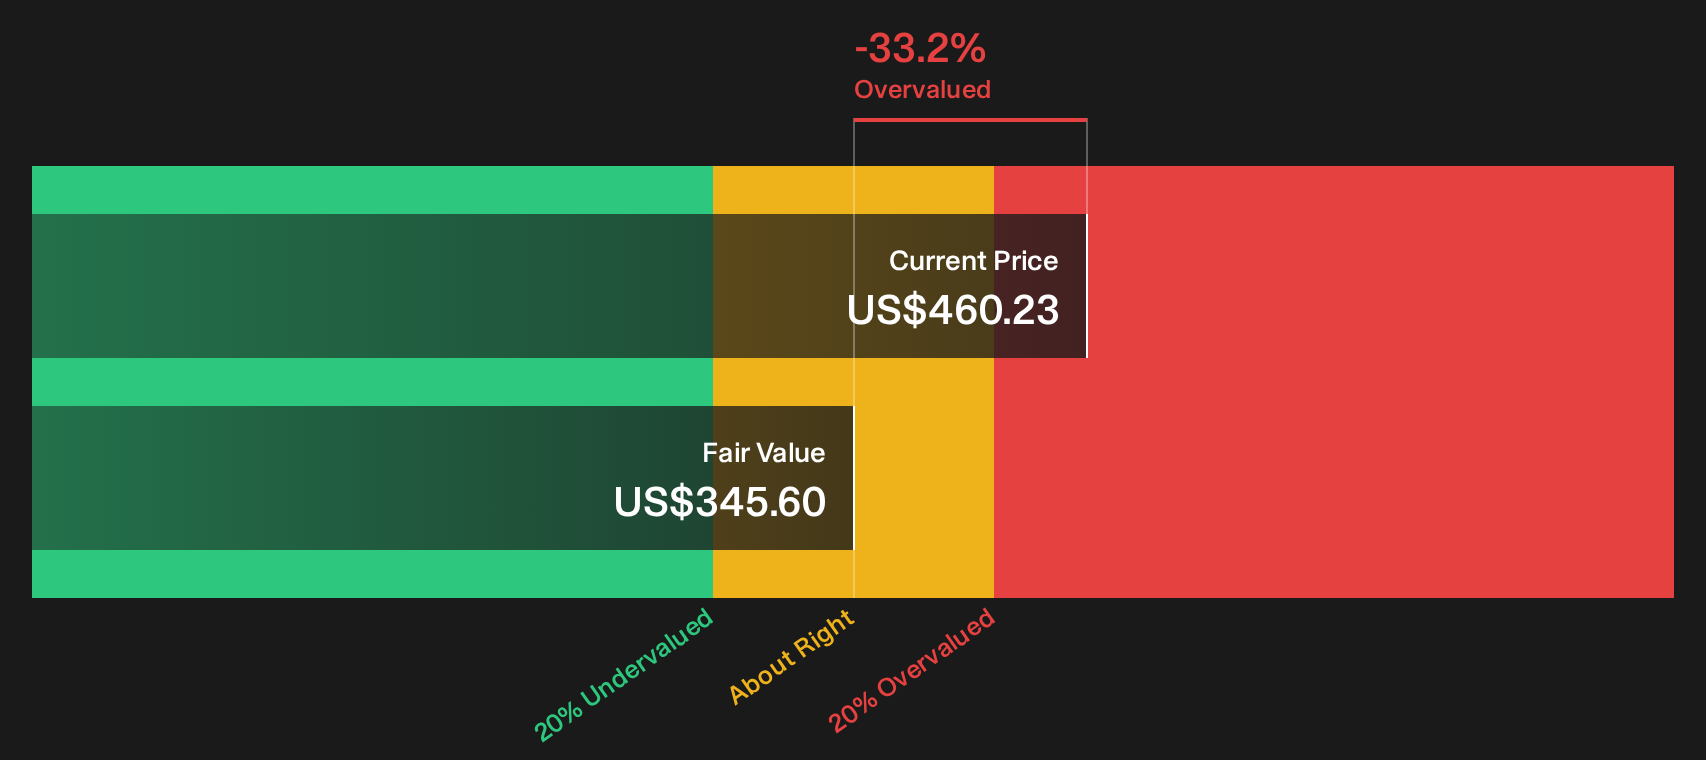
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out W.T.B. Financial for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around W.T.B. Financial is clearly mixed, with both risks and rewards in play. Move quickly and weigh the evidence for yourself using the full 3 key rewards and 1 important warning sign
Want more ideas beyond W.T.B. Financial?
If you like how W.T.B. Financial stacks up but want a broader watchlist, use targeted screeners to spot other candidates with fundamentals that suit your style.
- Target resilient balance sheets and consistent fundamentals by starting with a curated list of solid balance sheet and fundamentals (25 results) that filters out weaker profiles before you commit fresh capital.
- Hunt for quality at a discount by scanning the 33 high quality undervalued stocks so you are not relying on headlines alone to find potential mispriced opportunities.
- Zero in on income ideas by reviewing the 8 dividend fortresses and focus on companies where yield and financial strength work together rather than pulling in opposite directions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com