
Equinor (OB:EQNR) Lands Another Eneco Gas Deal As Valuation Questions Linger
Equinor (OB:EQNR) is back in focus after announcing a new five year natural gas supply agreement with Eneco, the third such contract between the partners so far this year.
The fresh supply deal lands while Equinor’s share price has picked up clear momentum, with a 90 day share price return of 20.77% and a year to date share price return of 79.06%, alongside a 1 year total shareholder return of 94.65% that reflects both price gains and payouts. Recent catalysts include its interest in bidding for Germany’s Uniper and stronger recent trading in Equinor’s US listed receipts. The Eneco contract fits into that pattern of investors reassessing both growth potential in European gas and perceived risk around long term cash flows.
Scan other energy players that could benefit from similar contract momentum by reviewing our hand picked 41 power grid technology and infrastructure stocks.
After a near 95% one year total return, Equinor now trades above the average analyst target and slightly above some intrinsic value estimates. So where does fair value really look anchored in this new price range?
Most Popular Narrative: 14% Overvalued
Equinor last closed at NOK432.60, while the most followed narrative pegs fair value at NOK378.73. This frames that recent price strength as a premium to intrinsic value built on discounted cash flow assumptions using a 6.79% hurdle rate.
Current valuations reflect assumptions of sustained or increasing shareholder returns (dividends and buybacks). However, high capital distribution may become harder to maintain if energy prices soften, FX movements turn adverse, or capex needs for transition projects increase, pressuring future EPS and total shareholder yield.
See why 97 investors see Equinor as 14% overvalued.
Result: Fair Value of NOK378.73 (OVERVALUED)
Still, if Equinor executes large projects like Johan Castberg efficiently and continues to secure long term gas contracts, that could soften the current overvaluation argument.
Find out about the key risks to this Equinor narrative.
Another View on Equinor’s Valuation
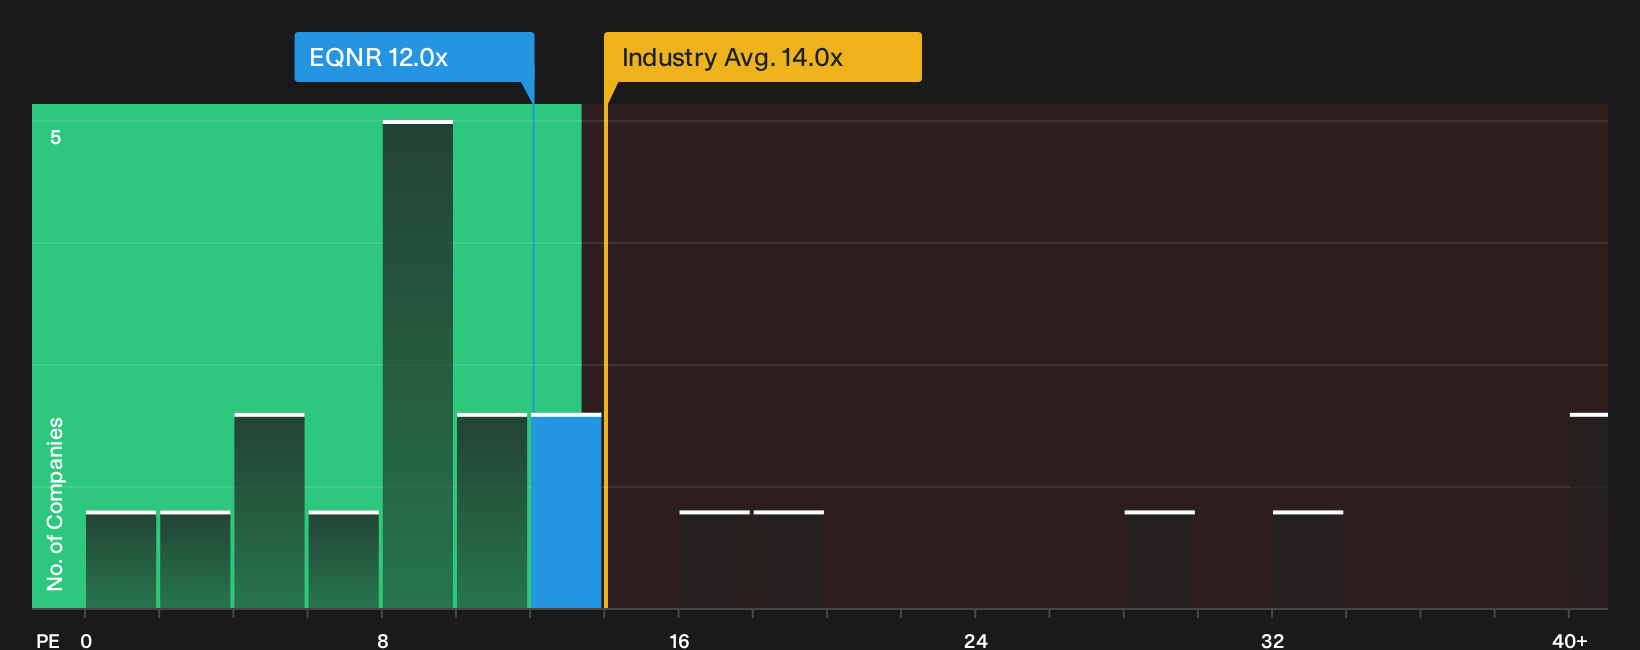
The fair value narrative calls Equinor about 14% overvalued at NOK432.60, yet the market is not pricing it like a clear outlier. The P/E sits near 12x, below the European oil and gas average of 14x, but above a fair ratio of 10.9x that the market could gravitate toward. That mix of relative cheapness and fair ratio premium raises a simple question. Is this pricing a cushion or a trap if sentiment cools?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling the mixed mood around Equinor after this run and valuation debate. Act quickly, review the full risk reward mix, and weigh the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Equinor?
Equinor’s story is just one opportunity. Broaden your watchlist now so you are not relying on a single outcome when markets shift.
- Target potential mispricing by scanning a curated set of attractively valued companies through the 191 high quality undervalued stocks.
- Strengthen your income stream by reviewing a focused shortlist of stronger yield opportunities in the 213 dividend fortresses.
- Protect your downside by filtering for sturdier balance sheets and fundamentals using the list of solid balance sheet and fundamentals (203 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com