
NVIDIA And 2 Other Undervalued Stocks To Watch
Bond markets are flashing warning lights as the US federal budget deficit nears US$2t and interest costs reach record levels, pushing Treasury yields to 24 year highs. When the risk free rate jumps, many investors focus on dependable cash generation and what they are paying for it. This article highlights three stocks where projected cash flows look attractive relative to price, based on SWS DCF estimates.
The three stocks below are just a sample set, and the full screen surfaced 91 more companies with equally cash focused stories that are not covered here.
If you want to go straight to the source and identify, compare, and analyze those ideas by their projected cash generation, head into the Undervalued Stocks Based On Cash Flows screener.
NVIDIA (NVDA)
Overview: NVIDIA builds data center scale AI computing platforms, selling GPUs, software, and related systems for cloud providers, enterprises, gaming, and automotive customers.
Operations: NVIDIA generates about US$275.4b from Compute & Networking and US$27.6b from Graphics, with most sales coming from the United States and Taiwan.
Market Cap: US$5,245.5b
NVIDIA matters for this cash flow focused screen because its data center AI platforms convert heavy infrastructure spending into substantial projected free cash generation.
"Uptake of an open-source, cheaper, or better platform than Nvidia's CUDA would heavily undermine Nvidia's moat and enable any sizeable firm to directly engage semiconductor manufacturers such as TSMC to produce their own chips, stealing away Nvidia's high margin products."
For investors watching NVIDIA, a single shift in how customers value premium AI compute could ripple quickly through margins and long term cash flow potential.
That kind of shift is exactly what the full narrative for NVIDIA unpacks, separating headline AI enthusiasm from the cash flow engine that could keep accelerating or stall.
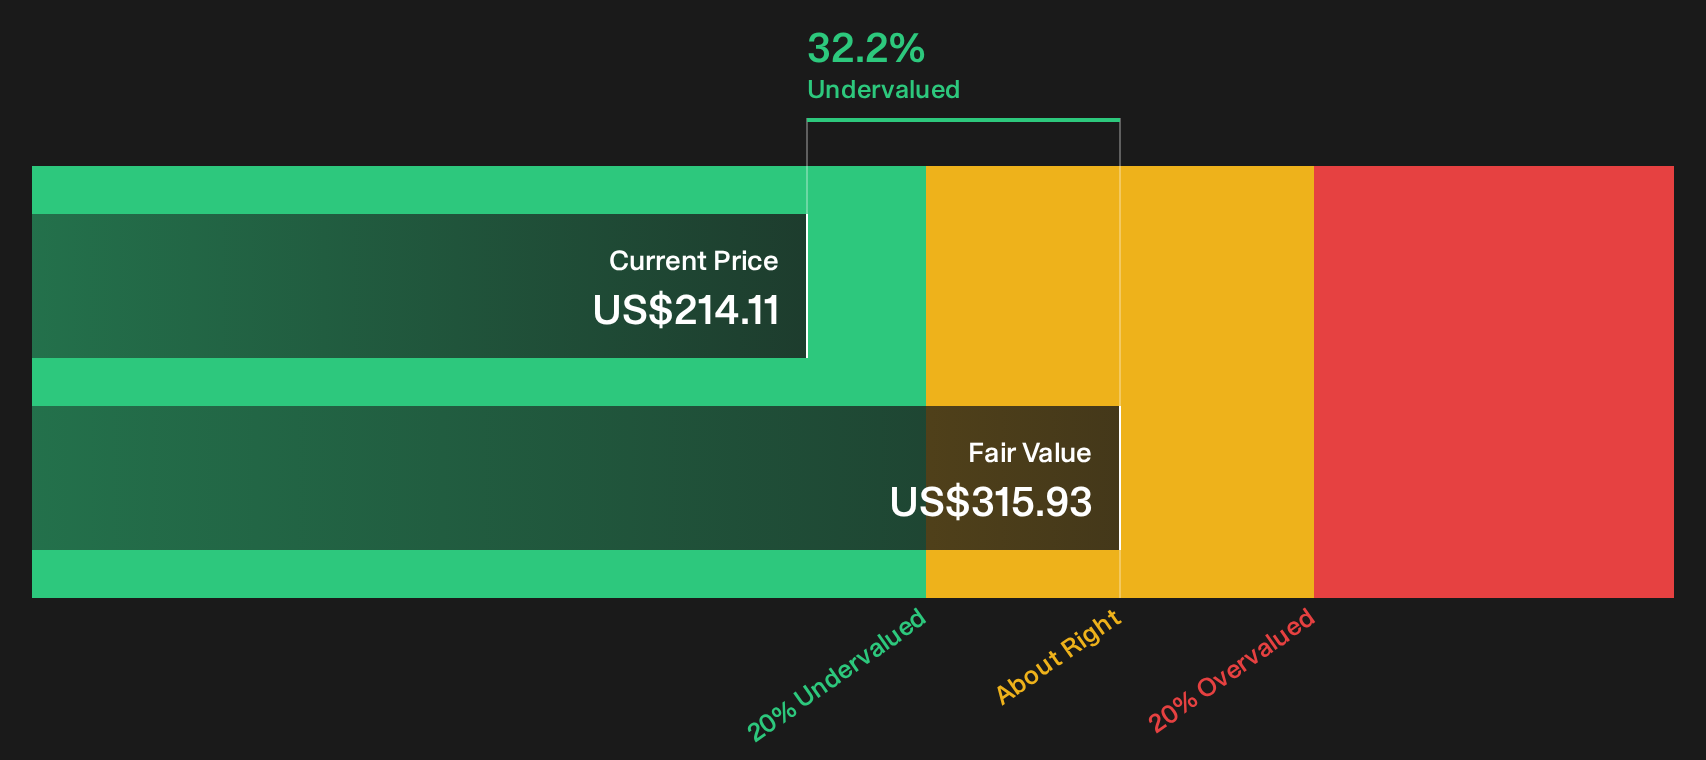
SouthState Bank (SSB)
Overview: SouthState Bank Corporation is a regional US bank that earns most of its money from lending and everyday banking and treasury services for households and businesses.
Operations: SouthState Bank generates about US$2.7b of general banking revenue entirely in the United States, reflecting a primarily domestic lending and deposit franchise.
Market Cap: US$9.8b
SouthState Bank fits this cash flow based screen because its commercial and real estate loan book, combined with treasury and fee income, drives the discounted cash flows that underpin its valuation case.
"Continued strong loan production growth in Texas and Colorado, where SouthState Bank has more than doubled loan production year over year to about US$1.1b in Q1 2026, with Houston leading the footprint, supports the view that this newer presence can keep lifting revenue and earnings over time."
What happens to that cash flow story if one quiet pressure on funding costs forces a rethink of how quickly margins can expand?
If that pressure on funding costs is the real swing factor, the full narrative for SouthState Bank shows how SouthState Bank’s newer markets could still keep the growth engine accelerating.
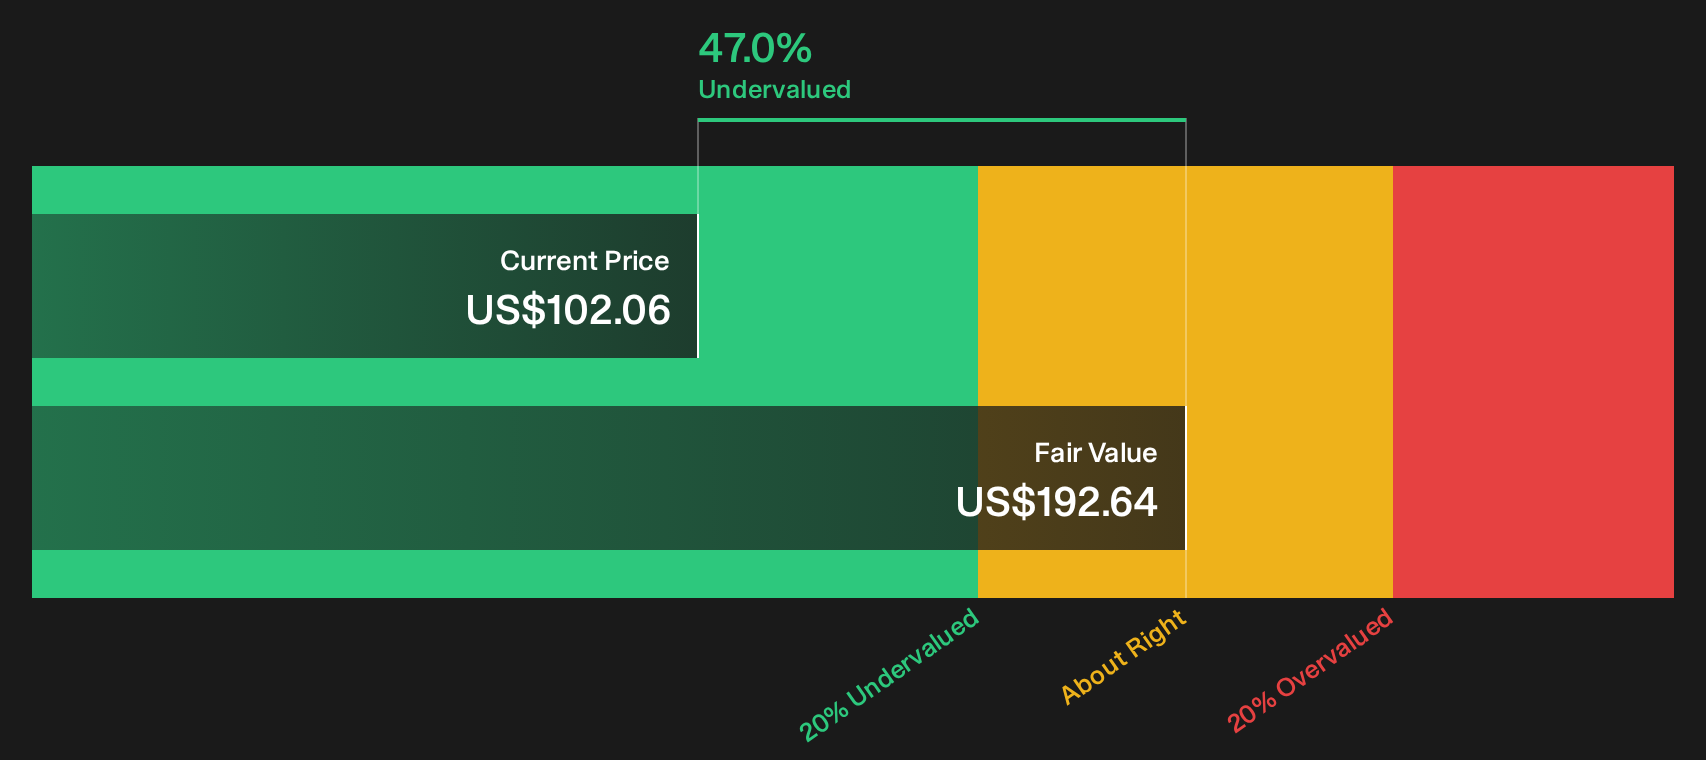
Bank of America (BAC)
Overview: Bank of America is a global financial group that uses everyday consumer deposits and loans to power broad banking, wealth, and markets services.
Market Cap: US$357.9b
Bank of America matters for a cash flow focused screen because its consumer deposit base and everyday lending products can generate recurring income that feeds directly into discounted cash flow models.
"Bank of America's continued investment in digital engagement and AI-driven efficiencies remains a live driver, with plans to double the AI budget within a US$14b technology spend. More than 140 AI applications such as Erica and CashPro are already reducing support needs, which could support revenue growth and net margins as the next wave of use cases rolls out."
The real swing factor is what happens if one unseen cost line moves faster than the revenue benefits that investors are currently baking in.
That hidden cost question is exactly what the full narrative for Bank of America tackles, showing where Bank of America’s efficiency push could accelerate or quietly stall.
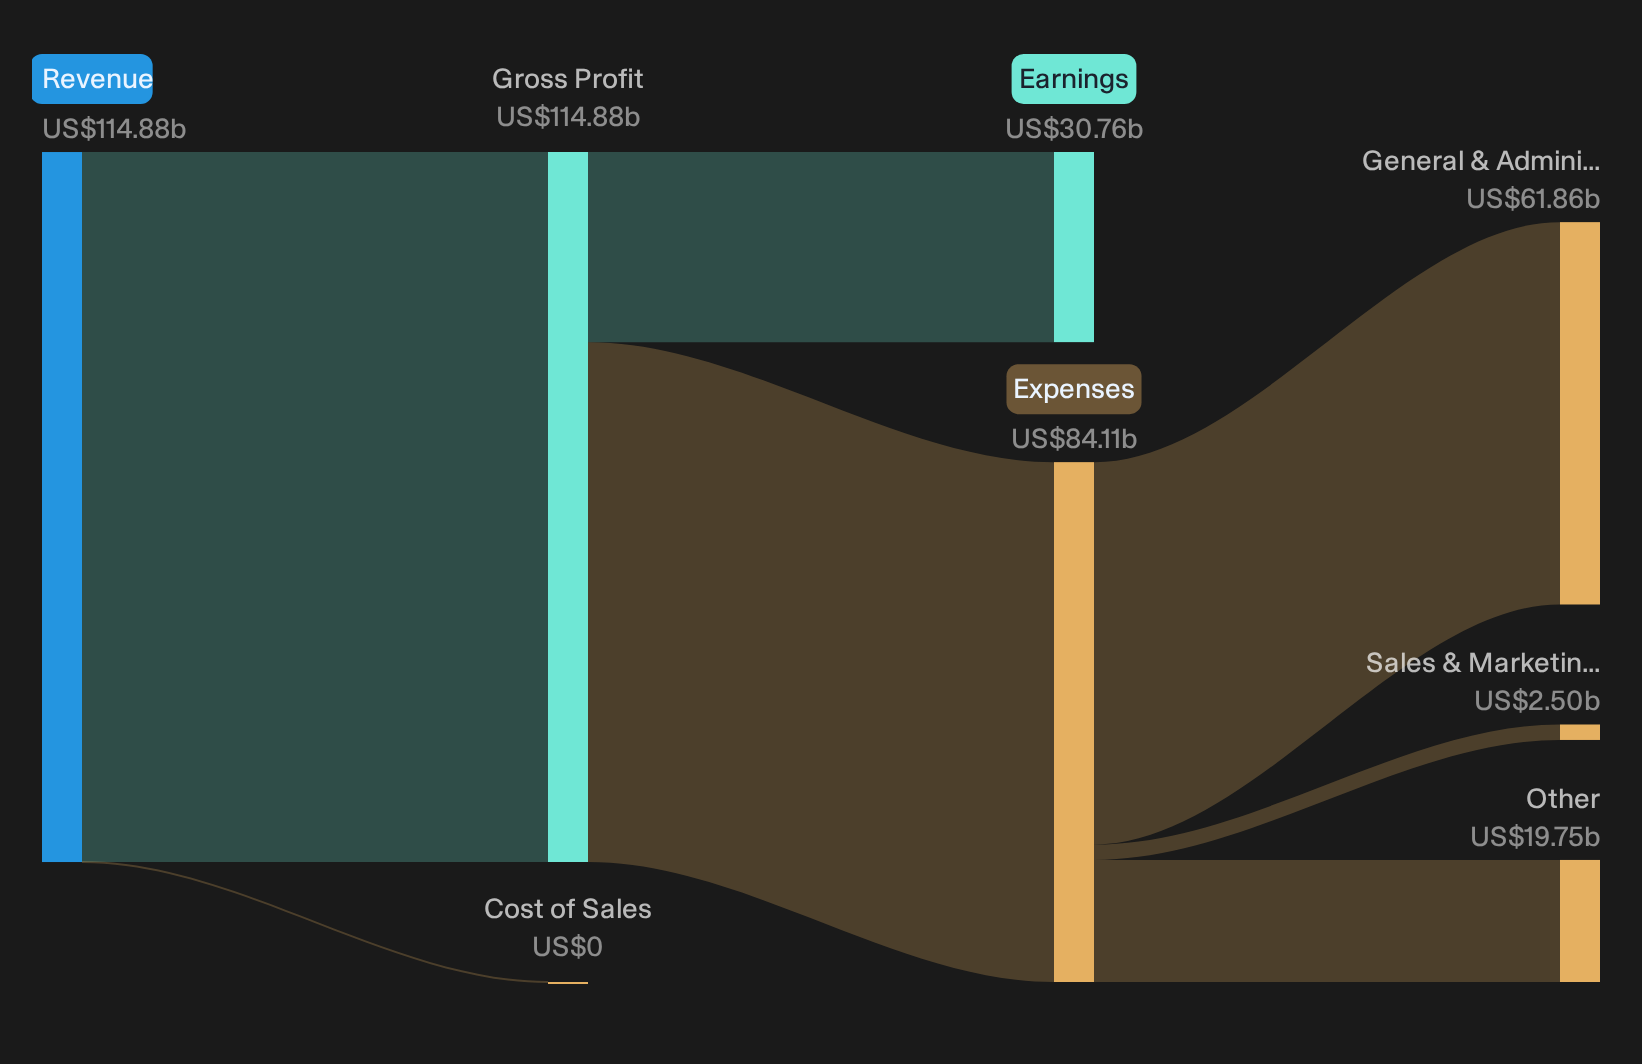
Seeking Alternatives Before The Crowd Moves
Fresh ideas move first. Breakout momentum often flies under the radar for now, then gets caught once attention floods in. Scan what others may miss and act now.
- Spot cash rich companies still priced like afterthoughts by screening a curated set of 20 high quality undiscovered gems before attention catches up.
- Track where reliable payouts meet resilient balance sheets by running through a focused pool of 8 dividend fortresses while yields and coverage still align.
- Follow real-world infrastructure behind AI momentum by scanning a hand picked universe of 55 AI infrastructure stocks before demand fully shows up in the headlines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com