
Peab (OM:PEAB B) Wins Askim Contract, Is The Stock Still Undervalued?
Peab (OM:PEAB B) has secured a NOK 319 million housing and commercial contract in Askim's Bytorget project, which will add 116 apartments and 2,000 m2 of retail space to its Norwegian order book.
Peab’s latest Bytorget win lands at a time when momentum has cooled a little in the short term. The 30 day share price return is 5.71% despite a positive 7 day move of 1.82%. The longer view looks stronger, with a 1 year total shareholder return of 26.28% and a 3 year total shareholder return of 133.89%, hinting that investors have been rewarding the construction group over time as it continues to secure sizeable Nordic projects.
Scan how Peab compares with other construction driven opportunities by running through our hand picked 41 power grid technology and infrastructure stocks aligned to long term infrastructure and urban development themes.
After a strong multi year run and a fresh contract in Askim, Peab’s share price now asks a simple question: Does the current valuation still leave enough upside to justify the risk?
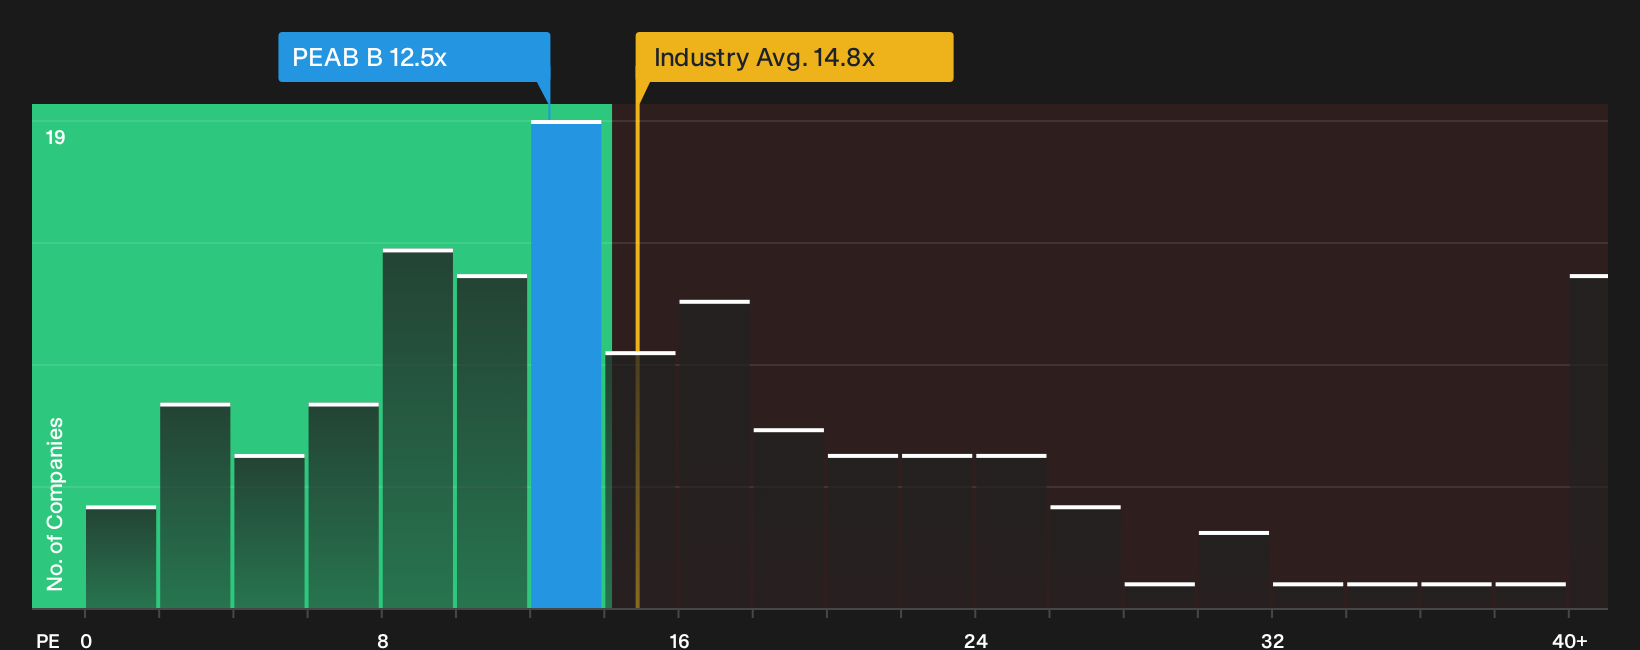
Preferred P/E of 12.5x for Peab: Is it justified?
Peab is priced at SEK92.5 per share, while the SWS DCF model estimates a future cash flow value of SEK168.6, which points to a wide gap between the traded level and that intrinsic estimate.
The DCF approach projects future cash flows based on current forecasts and then discounts those amounts back to today using a required rate of return. That process gives one all-in valuation number that folds in both expected growth and the risk profile of those cash flows.
For a construction and civil engineering group with SEK60,083.0m in revenue and SEK2,074.0m in net income, this kind of cash flow lens can be useful. Earnings are forecast to grow 9.6% per year, which is higher than the 7.1% expected for the Swedish market, and recent profit growth of 33.6% over the past year alongside higher net profit margins of 3.5% versus 2.6% gives the model more profitable cash flow inputs to work with.
The same dataset flags trade offs that readers should weigh alongside the apparent 45.1% discount to fair value. Analysts expect revenue to grow 4.3% per year, which is slower than high growth thresholds, return on equity is described as low at 13%, the balance sheet carries a high level of debt and the dividend track record is marked as unstable. These factors can help explain why the share may trade well below the SEK168.6 cash flow estimate in practice.
Result: DCF fair value of SEK168.6 (UNDERVALUED)
Look into how the SWS DCF model arrives at its fair value..
Still, Peab’s high debt load and slower 4.3% revenue growth outlook could quickly challenge the bullish DCF gap if project conditions or financing costs change.
Find out about the key risks to this Peab narrative.
Another view on Peab’s valuation
Market pricing tells a different story to the SWS DCF model. Peab trades on a P/E of 12.5x, while peers sit at 21.3x and the wider European construction group averages 14.8x. The fair ratio sits even higher at 20.1x, which points to a sizeable valuation gap.
That spread can look like opportunity when sentiment improves, or it can signal that investors are baking in balance sheet risk, profit cyclicality, or both. The key question is whether you see the current discount as a margin of safety or as compensation for those risks.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Peab for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Peab’s valuation and risk reward profile make this a judgment call that cannot be outsourced. Move quickly, review the data for yourself, then weigh the 4 key rewards and 2 important warning signs
Looking for more Peab sized investment ideas?
If Peab has sharpened your focus on pricing, cash flows and risk, do not stop here. Broadening your watchlist can reveal opportunities you would otherwise miss.
- Target potential mispricing by scanning companies that combine quality fundamentals with discounted valuations through the 191 high quality undervalued stocks.
- Strengthen your income pillar by reviewing resilient payout opportunities highlighted in the 213 dividend fortresses.
- Calm portfolio swings by filtering for steadier businesses using the 233 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com