
What Bharat Forge Holders Got Right
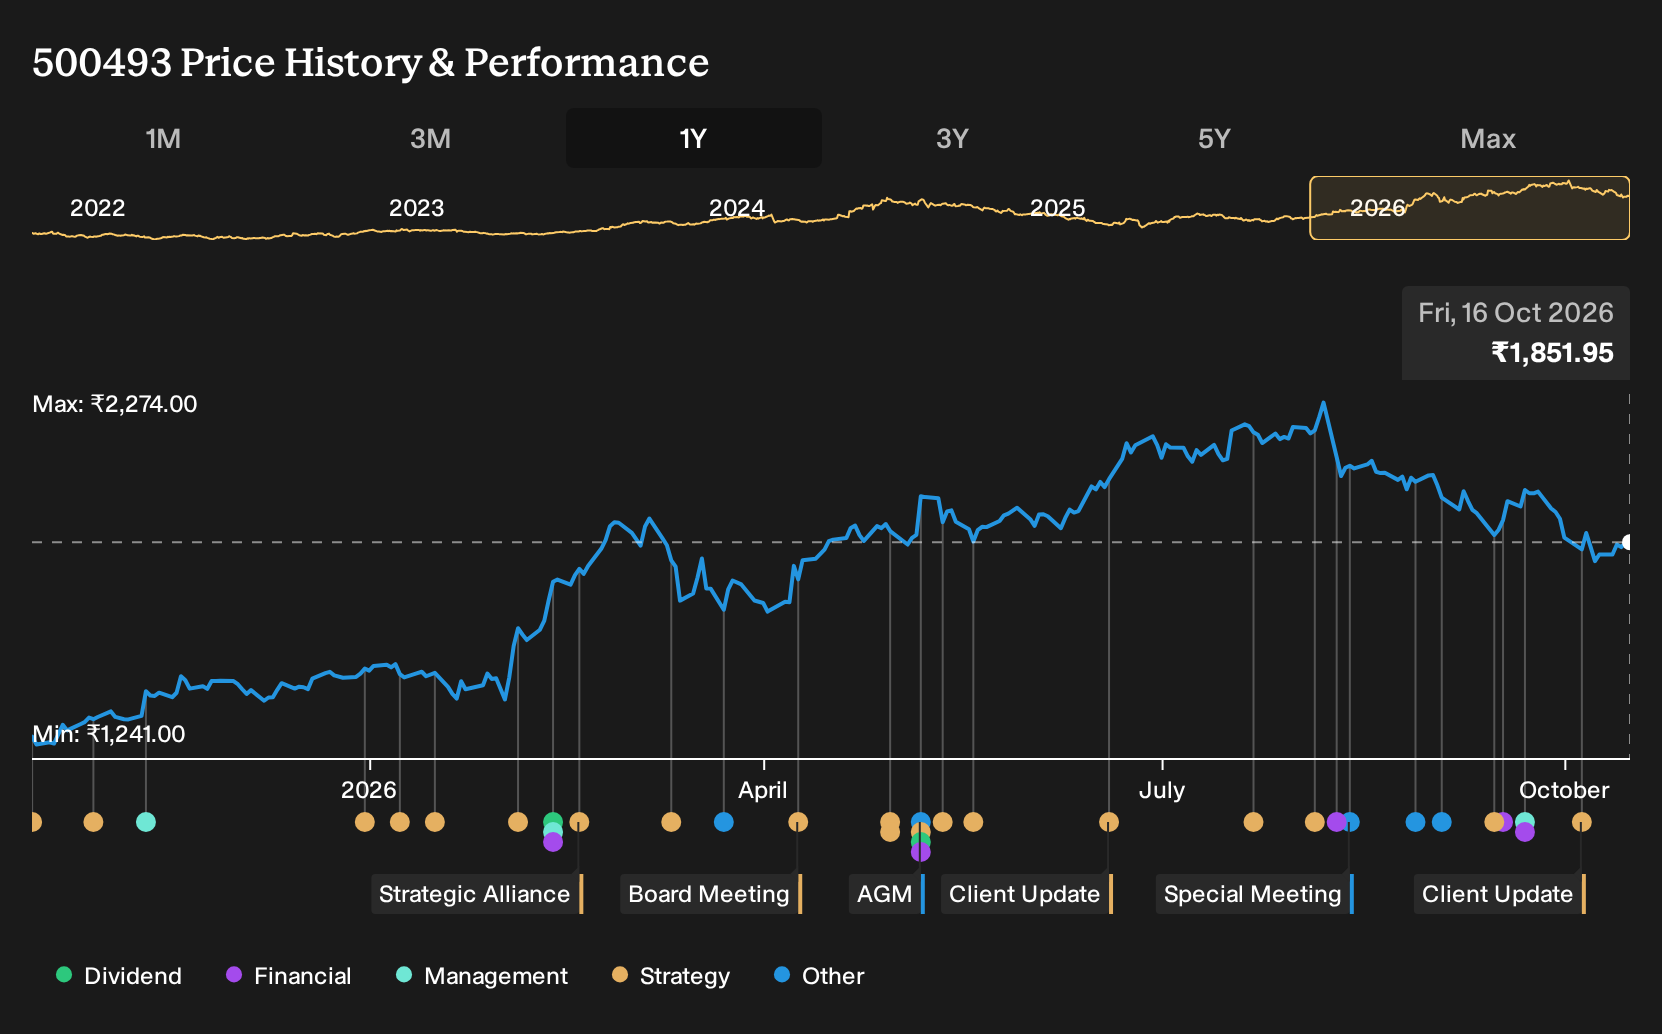
If you only glanced at Bharat Forge’s latest figures, the story looks awkward. Revenue reached ₹46,399.41m in Q1 2027 while the company swung to a net loss and its net margin fell to 1.9% in the red, yet the share price told a very different story. Holding Bharat Forge over the past year would have returned 49.9%, including dividends. If you had bought on 16 October 2025, how could that mix of rising sales and falling profitability have looked acceptable at the time?
If the move has made Bharat Forge harder to judge, start where the gap is still open and scan 191 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On Bharat Forge
The shares cost ₹1,265 at the start of the period, which meant you had to decide whether Bharat Forge was quietly underpriced or already baking in a lot of optimism.
On the optimistic side, one Narrative put Fair Value at ₹1,800, a notional “worth” if faster expansion played out, built on the idea that aerospace revenue could run ahead of consensus and that new electronics and server work would support higher margins.
The more cautious script pointed to a Fair Value of ₹1,164, based on assumptions of 11.4% annual revenue growth and profit margins reaching 11.0%, while flagging ongoing tariff risk in the United States as a key threat to earnings stability.
What The Results Put To The Test For Bharat Forge
The clearest update on Bharat Forge was the Q1 2027 print. Revenue reached ₹46,399.41m compared with ₹39,087.49m in Q1 2026, which backed the growth leg of the optimistic script. Profit flipped to a loss of ₹897.27m and net margin moved from 7.3% to 1.9% in the red, so the higher-margin promise stayed unproven. The evidence cut both ways.
The hinge assumption was that faster expansion would arrive with richer profitability. When you look at other companies making similar claims, track revenue, absolute earnings, and net margin together across several reports to see whether sales gains are actually coming through with sturdier economics.
What Bharat Forge’s Price Already Assumes After The Run
Bharat Forge now trades at ₹1,852, well above the level where this cautious Narrative places Fair Value. As a result, the valuation argument leans on what has to go right rather than what has already happened.
The Narrative concentrates on whether new defense, aerospace and tech-heavy projects can offset pressure in older overseas auto lines and turn the capex surge into solid cash.
"The main factor that has to go right is successful execution of the large India capex and the build out of defense, aerospace and high precision components, so that these newer verticals can offset overseas drag and cost inflation."
The price and this Narrative do not agree. → Uncover what this Narrative says Bharat Forge is actually worth
Before The Next Story Makes Headlines
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 44% below our estimate - support law-enforcement clients with tools for mobile device evidence analysis.
- Company 2 - 46% below our estimate - grow an established intimates label into higher margin everyday athletic apparel.
- Company 3 - 48% below our estimate - deliver integrated security solutions for modernizing data center and smart-building infrastructure.
Those are three of them. See every one of the 203 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com