
Caught Out By Teladoc Health's Slide? Here's What Bears Saw
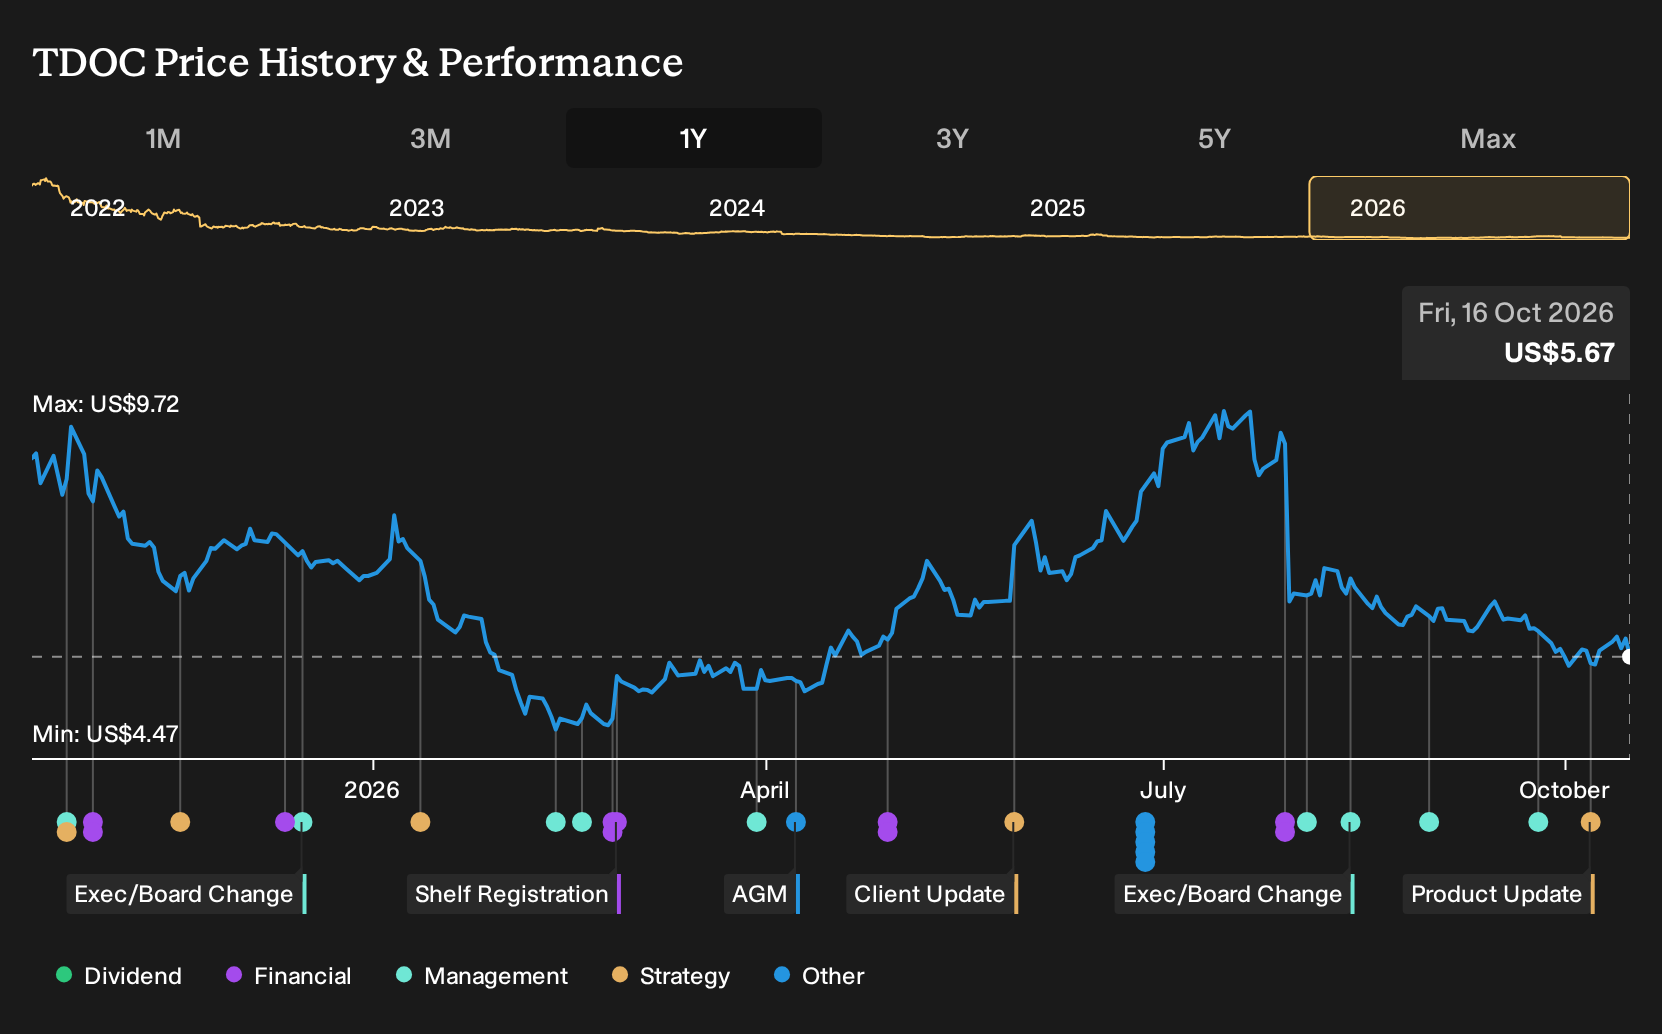
If you bought into Teladoc Health on the promise that virtual care, aging demographics and AI-enabled care orchestration would quietly grind higher over a few years, the past twelve months have been bruising. Investors who held Teladoc Health over the past year are down 33.5%, including dividends. If that holding period started with faith in modest 2.7% revenue growth, a 0.5% profit margin and a 221.1x future P/E, what exactly did that thesis miss about BetterHelp, reimbursement trends and the shift from subscriptions to visit-based care?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Teladoc Health is not the only name tied to this theme. Zero in on 33 healthcare AI stocks and compare how each one is priced.
The Two Teladoc Health Stories Investors Had To Weigh
Teladoc Health shares cost US$9.02 at the start of the period, and buyers were essentially choosing between two very different stories about virtual care.
The bullish narrative put fair value at US$12 and relied on revenue growth of 2.7% a year with profit margins rising to 0.5%. It treated a future P/E of 221.1x as reasonable if BetterHelp insurance access and AI-enabled care orchestration lifted earnings.
The bearish view anchored fair value at US$7 and assumed revenue would fall 0.6% a year while margins eventually reached 8.8%. It focused on rising compliance costs, reimbursement uncertainty and pressure from the shift toward visit-based care.
What The Results Changed For The Teladoc Health Story
Teladoc Health cut its 2026 revenue outlook after Q2 revenue moved from US$631.9 million in 2025 to US$606.9 million in 2026, with BetterHelp demand weakening and net income loss widening from US$32.66 million to US$38.91 million. Net margin moved from a 5.2% loss to a 6.4% loss. That mix of contracting top line and deeper losses supported the more cautious case.
The whole episode turned on one assumption investors could measure later: that BetterHelp and the new visit-based model would stabilise revenue and margins. For any other virtual care stock, watch the segment-level revenue trend and the reported net margin, then check whether management’s promised business model shift is actually improving both.
What Teladoc Health’s Drop Leaves You Paying For Today
Teladoc Health now trades at US$5.67, with the selected Narrative’s Fair Value sitting above that quoted level. The argument leans on the idea that investors today are paying for an established virtual care infrastructure rather than a speculative concept.
The same Narrative asks you to judge whether BetterHelp’s insurance pivot and Teladoc’s cash generation can support that view. A buyer now would need to believe the payer integration and free cash flow described there can justify treating the recent fall as an opening instead of a warning sign.
"The core lesson from that venture was simple: Without a crystal-clear alignment of whose wallet pays whom, even the most innovative platform dies. Teladoc’s early struggles mirror this exact dynamic, but its true inflection point arrived when it solved the 'who pays' equation through deep integration with health insurance payers."
The price and this Narrative do not agree. → Uncover what this Narrative says Teladoc Health is actually worth
How Could You Get There Earlier?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 42% below our estimate - sells tracker, software and storage packages to grid-scale solar developers.
- Company 2 - 45% below our estimate - converts data center and industrial backlogs into modular power and retrofit solutions.
- Company 3 - 49% below our estimate - builds digital banking tools that small business borrowers use as primary platforms.
Those are three of them. See the full list of 33 companies trading below our fair value estimates →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com