
Upcoming Earnings Might Change The Case For Investing In Tenet Healthcare Stock (THC)
- Tenet Healthcare recently drew attention as investors focused on its upcoming October 29, 2026 earnings report, with forecasts calling for strong revenue and profit along with commentary on Medicaid exposure and payer mix trends.
- The business is viewed as a potential beneficiary if future policy decisions soften Medicaid cuts, which would be significant given its reliance on supplemental Medicaid programs and state directed payments.
- This article examines how Tenet Healthcare's investment narrative may be influenced by expectations for stronger earnings and possible Medicaid policy relief.
Scan for other hospital and Medicaid exposed operators that could react in similar fashion to Tenet Healthcare with our curated list of solid balance sheet and fundamentals (25 results)
Tenet Healthcare Investment Narrative Recap
To own Tenet Healthcare, you need to be comfortable with a hospital and ambulatory operator that focuses on higher acuity procedures while managing payer mix and policy risk. The near term hinge point is the October 29 earnings release, where investors will be watching how exchange weakness, uninsured volumes and supplemental Medicaid flows show up in margins and cash generation.
The biggest near term risk remains pressure from declining exchange revenues and a heavier uninsured pool, which can lift bad debt and strain hospital profitability if it persists. Election discussion around softer Medicaid cuts matters to sentiment, but it does not change that heavy dependence on supplemental Medicaid programs and a sizable capital and buyback plan keeps financial flexibility in focus.
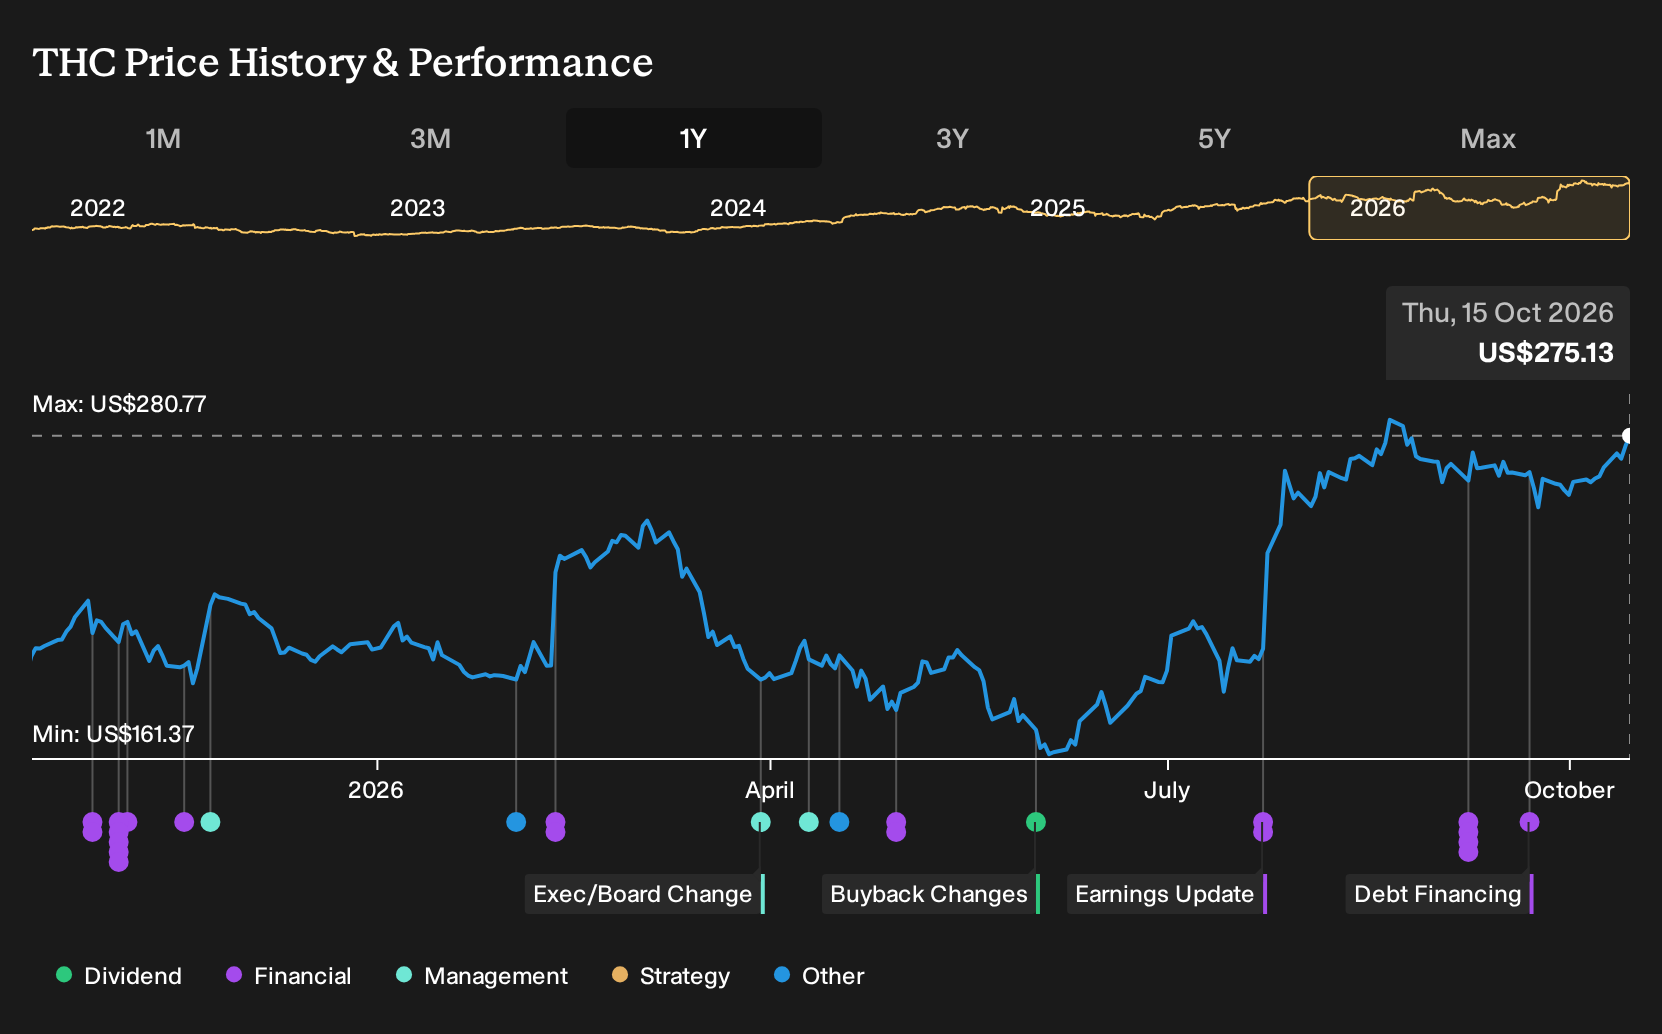
The most relevant data point tied to this setup is the recent stock performance into earnings, with Tenet Healthcare outperforming over the past quarter and year while forecasts call for strong revenue and profit in the upcoming report. That price move raises the bar for the earnings release because expectations around hospital trends, ambulatory volumes and cost savings are already elevated in investors’ minds.
Estimate revisions described as stable and an analyst hold stance frame this as a story where execution on operations, not fresh guidance upgrades, is the near term catalyst. For investors, that puts attention on three levers in the coming quarters: whether higher acuity procedures support mix, whether technology driven cost efficiencies still have room and whether capital deployment on USPI deals and buybacks remains compatible with Tenet Healthcare’s high debt load.
Tenet Healthcare's narrative projects US$24.1b revenue and US$1.6b earnings by 2029. This projection assumes 3.3% yearly revenue growth and an earnings decrease of US$600m from the current US$2.2b.
Uncover why Tenet Healthcare's fair value indicates a 7% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Not every analyst sees Tenet Healthcare through the same lens. The most optimistic group leans hard into higher acuity growth and tech efficiencies, assuming roughly 4.7% annual revenue growth and about US$1.6b in earnings by 2029. These pre-news views could shift meaningfully once the upcoming October 29 report lands.
Explore 4 other Tenet Healthcare fair value estimates, including one that suggests up to 568% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Tenet Healthcare research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Tenet Healthcare. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tenet Healthcare's overall financial health at a glance.
Looking for more Tenet Healthcare style investment ideas?
If the Tenet Healthcare setup has you thinking about portfolio upgrades, it can help to line it up against a wider field of opportunities with similar or contrasting qualities. The Simply Wall St Screener lets you move quickly from this single story to a shortlist of stocks that match the financial traits you care about most.
- If you want potential value combined with balance sheet resilience, start by scanning our 33 high quality undervalued stocks that already clear basic quality and financial strength checks.
- For readers who care more about staying on the front foot with risk, filter for companies passing strict stability and leverage filters by using our 32 resilient stocks with low risk scores as a starting universe.
- If the goal is to surface underfollowed opportunities rather than the usual large caps, broaden your watchlist with our curated 20 high quality undiscovered gems that pair quality fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com