
What Were Markets Telling Us at Friday's Close?
Some key markets that stand out to me as the week comes to a close is US stock indexes (mostly lower) and Energies (mostly higher).
Now we'll see if the US president gets frustrated over the weekend and hits the nuclear launch button.
The Grains sector closed lower, though futures were telling an interesting story heading into the weekend.
Afternoon Summary: With closing bells ringing out across the market landscape, we are reminded once again of the combined effect of the Goldilocks Principle[i] and the Wilhelmi Element[ii] telling us to pay attention to weekly closes. And who knows, maybe this is the last time we get to talk about weekly closes given what the US president said early Friday[iii], meaning there’s a good chance the world comes to an end over the next couple days[iv]. (And if it does, well, it sounds like there will be a new White House press secretary telling us about it.[v]) What I find interesting is given the chaos that has become the hallmark of the United States (Make America Chaotic, or MAC? Perchance the root of the president’s fondness for Big Macs?) gold (GCZ26) was still headed toward a lower weekly close at this writing. On the other hand, all of the wheeling and dealing this past week, including buying diesel from Vlad the Invader, has the spot-month diesel fuel contract up 13.3 cents (2.85%) while WTI crude oil is up $7.40 (8.15%). In other news, both the S&P 500 and Nasdaq stock indexes seem headed for lower weekly closes, though we still have the NBA Rule[vi] to contend with Friday afternoon.
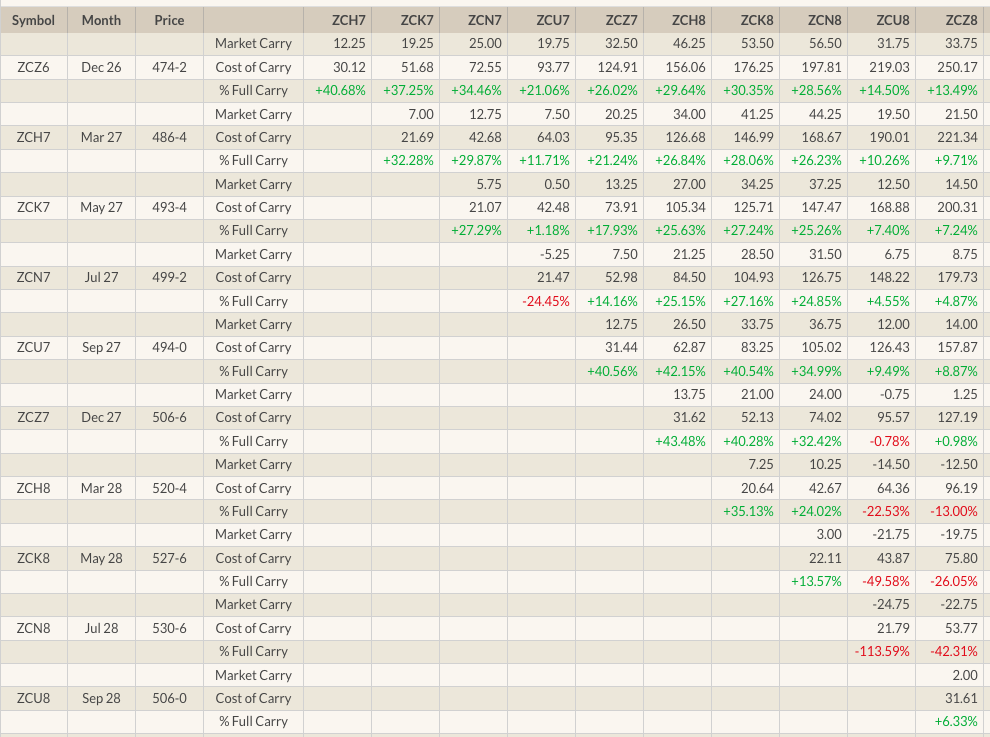
Corn: For those of you interested in the corn market, which is most folks across the United States, Friday was one of those days when it was best to turn off the quote screen and find something else to do. Given I’m known for my generally optimistic outlook (Cough, cough…), I’ll say today’s session wasn’t quite as bearish as last Friday. But then again, we didn’t have the nonsense of a USDA Keno game creating havoc, so there’s that to consider. The December issue (ZCZ26) finished today’s session 3.75 cents in the red after dropping as much as 5.0 cents on trade volume of roughly 190,000 contracts. This put Dec down 5.5 cents for the week after finishing the latest Tuesday-to-Tuesday positioning week with a loss of 25.25 cents. The key to this past week though is futures spreads. The Dec-March finished Friday covering 41% calculated full commercial versus last Friday’s 48%. That is a substantial change reflecting harvest was slowed once again by weather. Now we’ll see what happens with national average basis with Thursday night’s calculation at 39.0 cents under December futures as compared to last Friday’s 40.0 cents under and the previous 5-year low weekly close for this week of 40.25 cents under December.
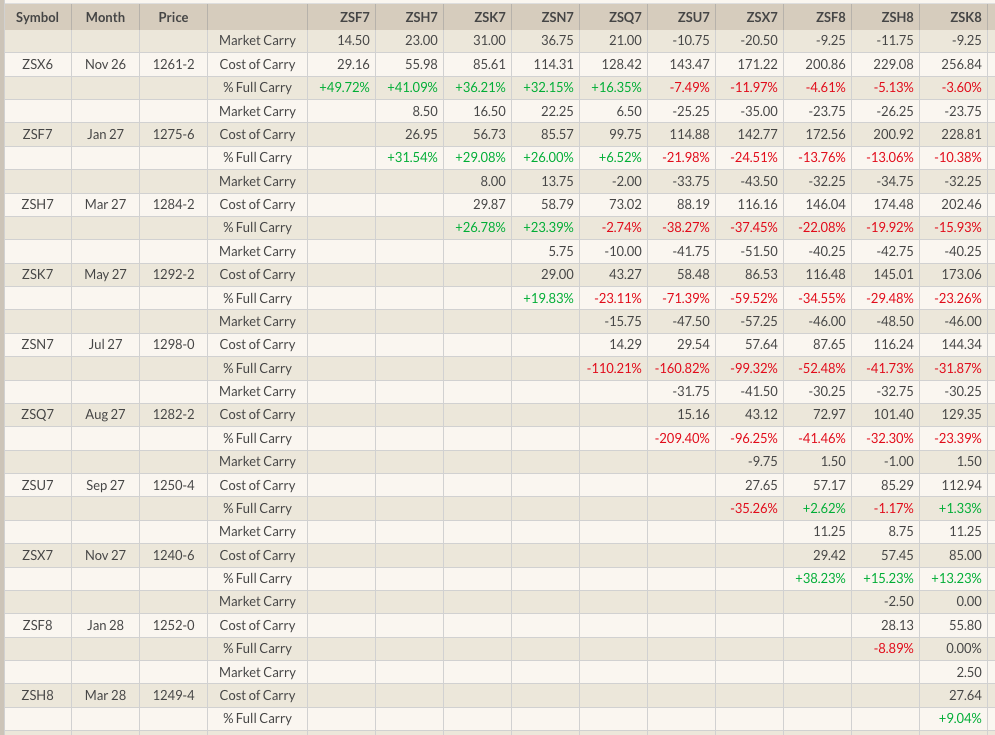
Soybeans: It was an interesting day, and week, in the oilseed sub-sector. As of this writing the spot-month diesel fuel contract (HOX26) is up about 5.75 cents while oilseed markets closed mostly lower. But it isn’t quite what it looks like. December soybean oil finished 0.02 cent in the red after dropping as much as 0.65 cent Friday. This brings to mind the old sports cliché the market didn’t close lower, it just ran out of time. The same could be said for soybeans where the November issue finished 1.75 cents in the red after falling as much as 9.75 cents. This put November down 30.75 cents for the week as it extended the intermediate-term downtrend on its weekly chart. January (ZSF27) was down 2.0 cents for the day and 33.0 cents for the week. And those numbers answer your next question, “What about all the export sales announced this week?” The Nov-January futures spread closed this week covering 50% calculated full commercial carry as compared to last Friday’s 57%. As for national average basis, Thursday’s calculation came in at 59.75 cents under November futures versus last Friday’s 58.0 cents under and the previous 5-year average weekly close for this week of 58.75 cents under November.
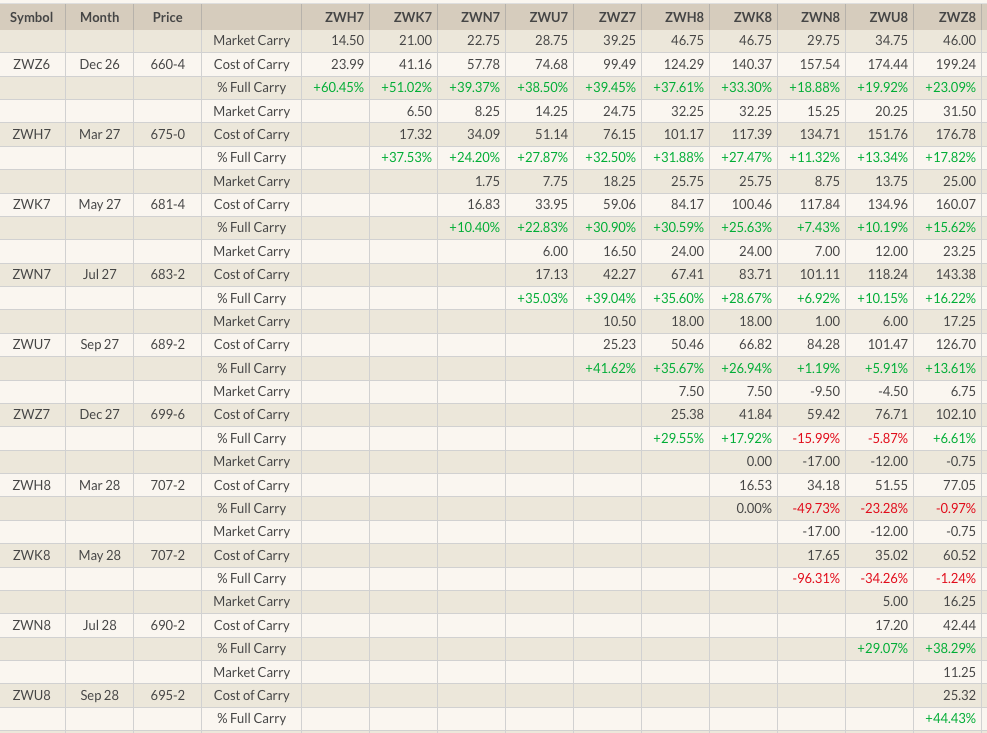
Wheat: And then there’s the wheat sub-sector. Here’s the thing: It’s wheat. And I could end the commentary with that. But I won’t. The Wheat Reality tells us one bushel (or metric ton) of wheat left over is too many because it can be grown across nearly every corner of the globe[vii]. Take a look at the futures spreads and what do we see? The December-March SRW spread finished this week covering 60.5% calculated full commercial carry, slightly more than last Friday’s 59%. Over in HRW the nearby spread covered 48% at today’s close versus last Friday’s 50%. What do all these numbers tell us? First and foremost, the US has more than one bushel (metric ton) of wheat on hand. Is the world going to run out of wheat soon? Well, if the US president gets frustrated with poll numbers this weekend and hits the nuclear launch button, will it matter? But in case the latter doesn’t happen, my answer is no, the world is not going to run out of wheat. For the record Dec SRW (ZWZ26) was down 10.5 cents for the week while Dec HRW (KEZ26) was sitting 15.25 cents in the red. What else do we need to know about the Cockroach of the Grain Sector[viii]?
[i] Daily charts are too hot, monthly charts are too cold, but weekly charts are just right.
[ii] The only price that matters is the close.
[iii] He won’t use nuclear weapons or send ground troops to Iran.
[iv] If we somehow make it to Monday, October 19, I’ll take a moment to remember the 39th Anniversary of Black Monday.
[v] Reportedly the US president has fired Katie Zacharia after five days on the job. Something about lying on the resume and a lack of qualifications. Is anyone surprised? Anyone? Bueller?
[vi] All we have to watch is the last half hour of the session.
[vii] Yes, I know, globes don’t have corners. But you get the idea. Wheat can be grown everywhere. Even in Saudi Arabia.
[viii] Interesting. We also know cockroaches can survive a nuclear blast.
On the date of publication, Darin Newsom did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.