
T&D Holdings (TSE:8795) Could Be 9% Below Fair Value On Payout Plan Hope
T&D Holdings (TSE:8795) moved higher in the latest session, with the share price closing at ¥4,811. Recent returns show a mixed picture over the past week, month, and past 3 months.
Short term momentum for T&D Holdings looks a little choppy, with the 30 day share price return down 3.3% even as the year to date share price return sits at 31.2%. That near term pause comes against a much stronger backdrop, with 1 year total shareholder return at 48.3% and 5 year total shareholder return at about 2.7x. This signals that investors have been steadily repricing the insurer as perceptions of its longer term prospects and risks evolve.
Compare T&D Holdings' sharp longer term rerating with other insurers and financial stocks that score well on fundamentals using our curated list of solid balance sheet and fundamentals (21 results) for ideas beyond this one.
The question now is simple. Does the latest move in T&D Holdings mainly echo real shifts in its insurance business, or is sentiment doing most of the work on the valuation side?
Most Popular Narrative: 9% Undervalued
Compared with the last close at ¥4,811, the most followed narrative for T&D Holdings points to a fair value of ¥5,267, which implies the rerating story is not fully priced in yet.
The current valuation implies the share price does not fully reflect the delivery of higher adjusted profit targets, the 60% payout plan and the cash generation from the growing closed-book and overseas businesses.
See why 1 investors see T&D Holdings as 9% undervalued.
Result: Fair Value of ¥5,267 (UNDERVALUED)
Still, the T&D Holdings story can be knocked off course if surrender and lapse pressures persist or if further rate moves strain the balance sheet.
Find out about the key risks to this T&D Holdings narrative.
Another View: T&D Holdings On Earnings Multiples
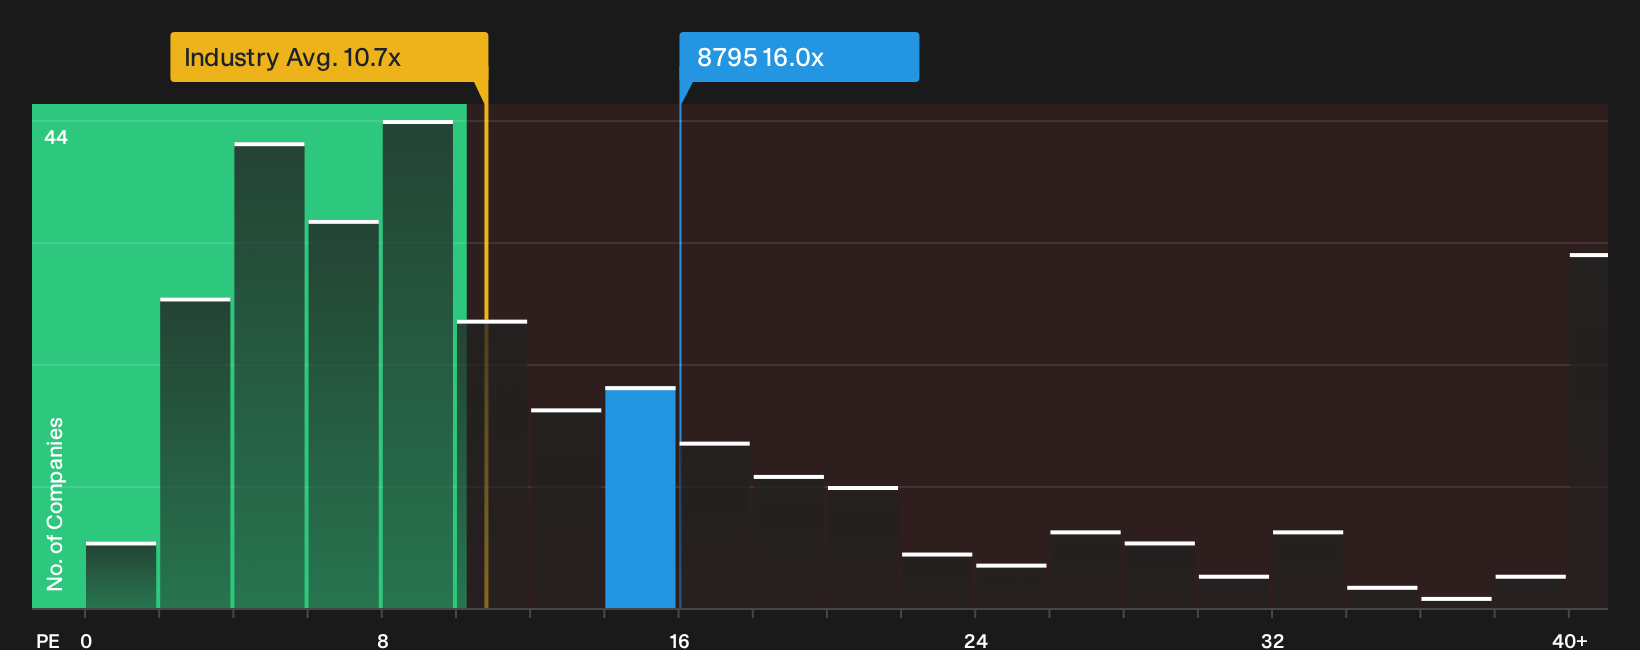
DCF work suggests T&D Holdings has room to rerate, yet the picture changes when earnings multiples are used. The stock trades on a P/E of 16x, above both the Asian insurance peer average of 10.7x and a fair ratio of 15.5x. Is that premium cushioning you, or thinning the margin for error?
For a closer look at how this earnings multiple compares with underlying fundamentals, and how stretched or reasonable that premium might be in practice, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around T&D Holdings is clearly split, with investors weighing both pressure points and bright spots, so move quickly and stress test the data yourself before forming a view. To see a concise rundown of what the crowd currently sees on both sides, check out the 4 key rewards and 1 important warning sign.
Looking for more T&D Holdings sized investment ideas?
If T&D Holdings has sharpened your focus on quality and valuation, do not stop here. Broaden your watchlist now so you are not late to the next move.
- Target resilient balance sheets and steady fundamentals by scanning companies in the list of solid balance sheet and fundamentals (21 results).
- Hunt for pricing gaps where quality and valuation meet by reviewing the 14 high quality undervalued stocks.
- Build a stream of potential cash income and compare yields using the 29 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com