
MasTec (MTZ) Stock Looks Below Fair Value On Its 199% Run
MasTec has given investors a rough ride recently, with the share price down over the past month and year, yet the bigger story is whether today's valuation still lines up with what its earnings can support. With the stock coming off a strong multi year run and fresh headlines around its project pipeline, the key issue now is how much profit power the business is being priced for.
- Over the past 3 years MasTec has delivered a return of 199.4%, which puts a lot of weight on the question of how strongly its earnings can underpin that kind of share price change.
- Recent news highlighting a growing backlog and rising demand in areas like AI infrastructure and defense related projects can support higher revenue expectations, which in turn feeds directly into how investors frame the company's future earnings base.
- Your read on MasTec is one view; the desks covering it have another. See what analysts think MasTec's shares could be worth.
The issue now is whether MasTec's current share price, after its recent pullback and multiyear gains, is justified by the earnings profile that investors are effectively paying for.
If you want to test the same earnings question you are asking of MasTec against a wider set of AI infrastructure contractors and enablers, scan the 55 AI infrastructure stocks.
Is MasTec a Bargain on Earnings?
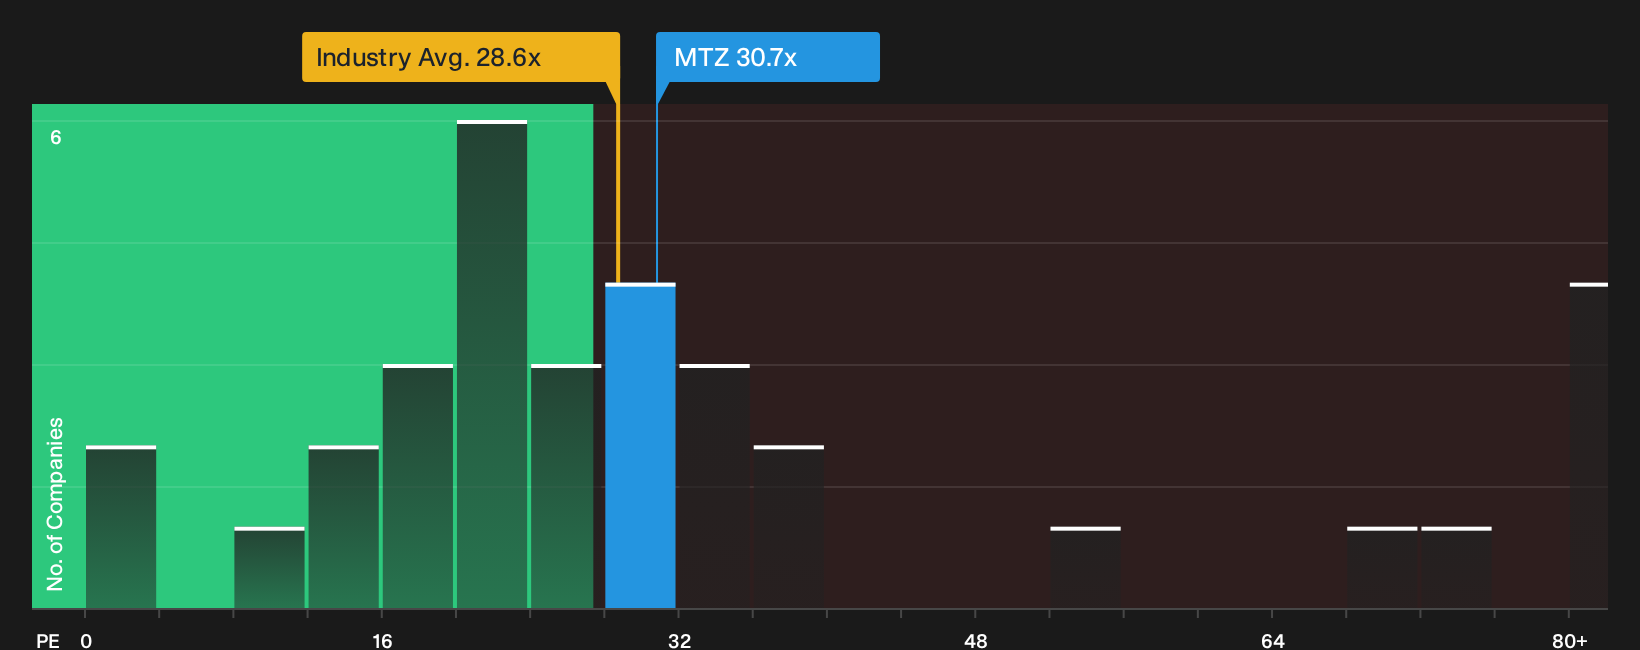
The P/E ratio works well for MasTec because earnings are the main driver behind how investors value large project contractors. On this yardstick, MasTec trades on a P/E of 30.7x, which sits above both the Construction industry average of 28.6x and the peer group at 25.2x. That means you are paying a richer price for each dollar of current earnings than you would for many similar contractors.
Because the recent backlog strength in AI infrastructure and defense projects has lifted expectations, the market is already assigning MasTec a premium multiple. The valuation model that blends the company’s growth profile, margins, size and risk suggests MasTec’s current P/E stands below the level that framework would imply, pointing to the stock as undervalued on this measure despite the premium to sector and peers. To judge whether that discount is justified, you would want to weigh how reliably those future projects can turn into sustained profits at the level implied by the multiple. Explore the numbers behind MasTec's P/E valuation.
The MasTec Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for MasTec leaves off. They spell out what growth, margin and earnings paths would need to hold for the stock to look materially higher or lower than today's price. Each scenario links a fair valuation to a specific mix of potential catalysts and setbacks in MasTec's project pipeline, allowing you to track over time which version of the story seems closest to reality.
One of the top community narratives on MasTec: 39% undervalued
"The main factor that has to go right is that utilities, pipeline operators, and data center customers follow through on multi-year spending plans..."
Discover why this Narrative puts MasTec at 39% undervalued.
One more MasTec check that belongs next to the price tag
There is a final cross check that sits alongside MasTec's current multiple. This is where professional analysts expect the earnings base to sit a few years from now, and how that compares to what the market already prices in. Explore where analysts expect MasTec to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com