
Evolution Mining (ASX:EVN) Posted A Strong September Quarter, Is It Still Below Fair Value?
Evolution Mining (ASX:EVN) has released new operating figures for the September 2026 quarter, reporting production of 154,000 ounces of gold and 18,000 tonnes of copper at an all-in sustaining cost of A$1,653 per ounce.
That production update comes at a time when Evolution Mining’s share price has climbed 19.66% over the past 90 days, even though the 30-day share price return is down 5.05%. The 1-year total shareholder return of 10.79% and very large 3- and 5-year total shareholder returns indicate that long-term holders have experienced strong compounding despite recent short-term volatility around the current A$12.6 price.
Scan how Evolution Mining stacks up against other producers by running the same filter across 36 elite gold producer stocks, shaping the next leg of the sector.
For Evolution Mining, a strong multi year return record now sits beside a choppy near term chart. Is the latest swing mostly sentiment, or does the current share price fairly reflect the underlying business?
Most Popular Narrative: 8% Undervalued
On the most followed view, Evolution Mining screens as modestly undervalued, with a fair value of A$13.65 against the recent A$12.60 close. This puts the emphasis squarely on how copper growth and capital spend shape that gap.
The main requirement is continued delivery on organic growth projects and capital allocation discipline, so that higher sustaining capital, cost inflation and operational constraints do not erode the benefits of the copper and gold portfolio.
See why 41 investors see Evolution Mining as 8% undervalued.
Result: Fair Value of A$13.65 (UNDERVALUED)
Still, this narrative only holds if higher sustaining capital and rising AISC do not eat into Evolution Mining cash generation, and if labour turnover does not restrict output at key sites.
Find out about the key risks to this Evolution Mining narrative.
Another View: What Multiples Say About Evolution Mining
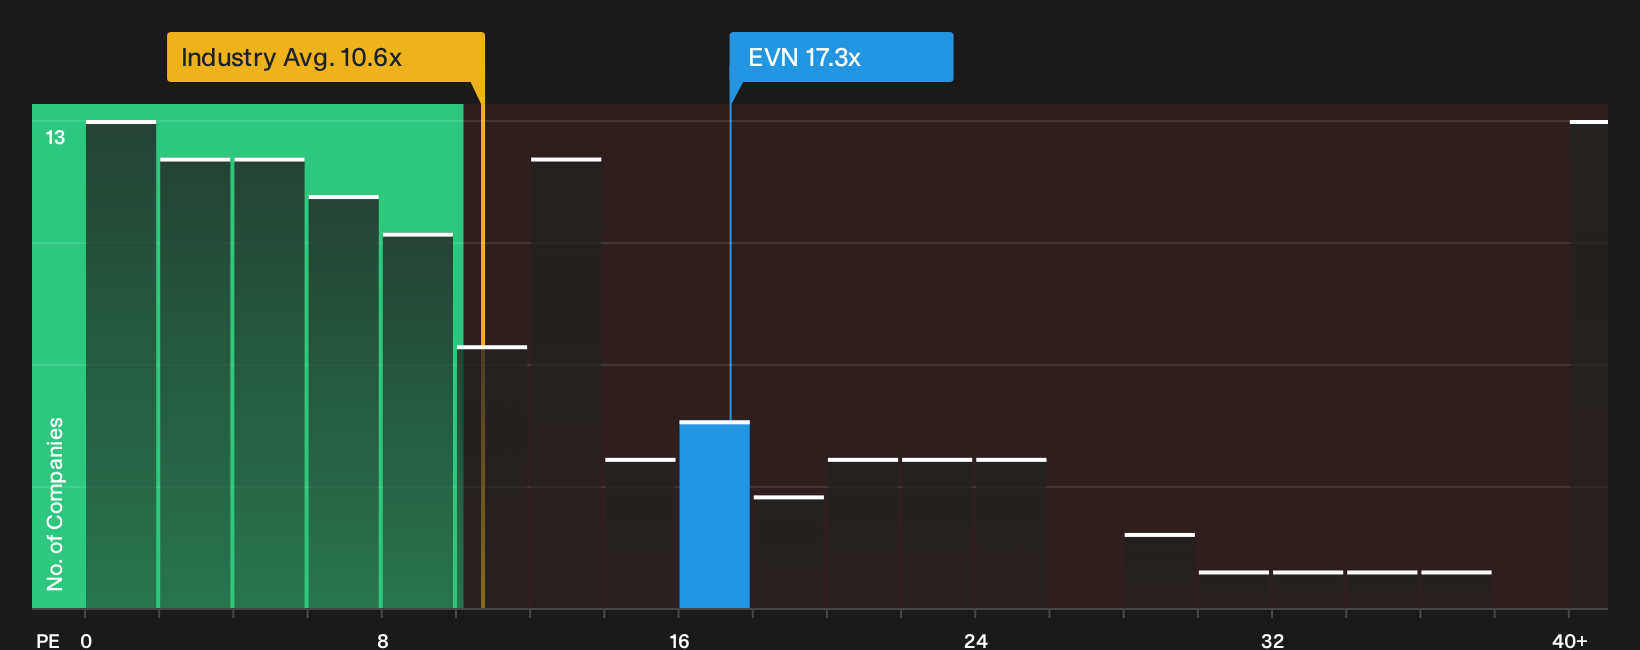
Evolution Mining screens differently when judged on its P/E ratio. At 17.3x earnings, the stock trades well above the Australian Metals and Mining industry on 10.6x, and even slightly above its own fair ratio of 16.9x. That points to limited margin of safety if expectations slip.
For investors comparing Evolution Mining to peers, that premium against the industry yet discount versus the 28.4x peer average raises a simple question. Is the higher price you pay today justified by the quality of assets and copper optionality, or are you leaning too hard on the consensus story? See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Evolution Mining so far. If you want to move quickly and rely on your own judgment, start with the full picture from 2 key rewards and 1 important warning sign
Looking for more Evolution Mining investment ideas?
If Evolution Mining has sharpened your focus, do not stop here. The right watchlist comes from comparing different angles, sectors, and risk profiles across the market.
- Target potential multi-bagger opportunities by scanning 19 elite penny stocks with strong financials that already pair tiny market caps with stronger financial footing.
- Hunt for quality at a discount by reviewing the 4 high quality undervalued stocks that combine solid fundamentals with prices that lag underlying strength.
- Prioritise resilience first by filtering through the 6 resilient stocks with low risk scores so cash, debt, and volatility work in your favour, not against you.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com