
Amalgamated Financial (AMAL) Nears Earnings, Is The 13% Undervaluation Still Convincing?
The upcoming October 22 earnings release for Amalgamated Financial (AMAL) is in focus as investors weigh cautious analyst sentiment, a negative Earnings ESP, and uncertainty around the bank’s ability to outperform expectations.
Recent trading paints a mixed picture for Amalgamated Financial. The share price is at $47.09 after a 1-day share price gain of 1.23%. At the same time, the year-to-date share price return of 47.43% and a 1-year total shareholder return of 89.62% hint that investors have been reassessing both its growth prospects and risk profile over a longer stretch.
Scan how Amalgamated Financial compares to other banks that combine earnings momentum with solid fundamentals by reviewing the hand picked list of solid balance sheet and fundamentals (25 results) in one place.
For Amalgamated Financial, the recent surge in long term returns could reflect a stronger underlying franchise or simply a swing in sentiment. The valuation work now needs to sort those two stories.
Most Popular Narrative: 13% Undervalued
On the most followed view of Amalgamated Financial, a fair value of $54 sits above the latest $47.09 close. This pulls the current setup into focus ahead of earnings and puts the spotlight on what is driving that gap.
Disciplined balance sheet management, with Tier 1 leverage above 9%, high pass rated loan levels and progress toward an 85 or 15 net interest to fee income mix, including core noninterest income of roughly US$10m to US$11m per quarter, positions Amalgamated Financial to keep growing pre tax pre provision earnings even while it manages isolated credit issues.
See why 4 investors see Amalgamated Financial as 13% undervalued.
Result: Fair Value of $54 (UNDERVALUED)
Still, the bullish Amalgamated Financial story can strain quickly if concentrated credit issues demand heavier provisions or if election linked political deposits swing more sharply than expected.
Find out about the key risks to this Amalgamated Financial narrative.
Another View: Amalgamated Financial Through The P/E Lens
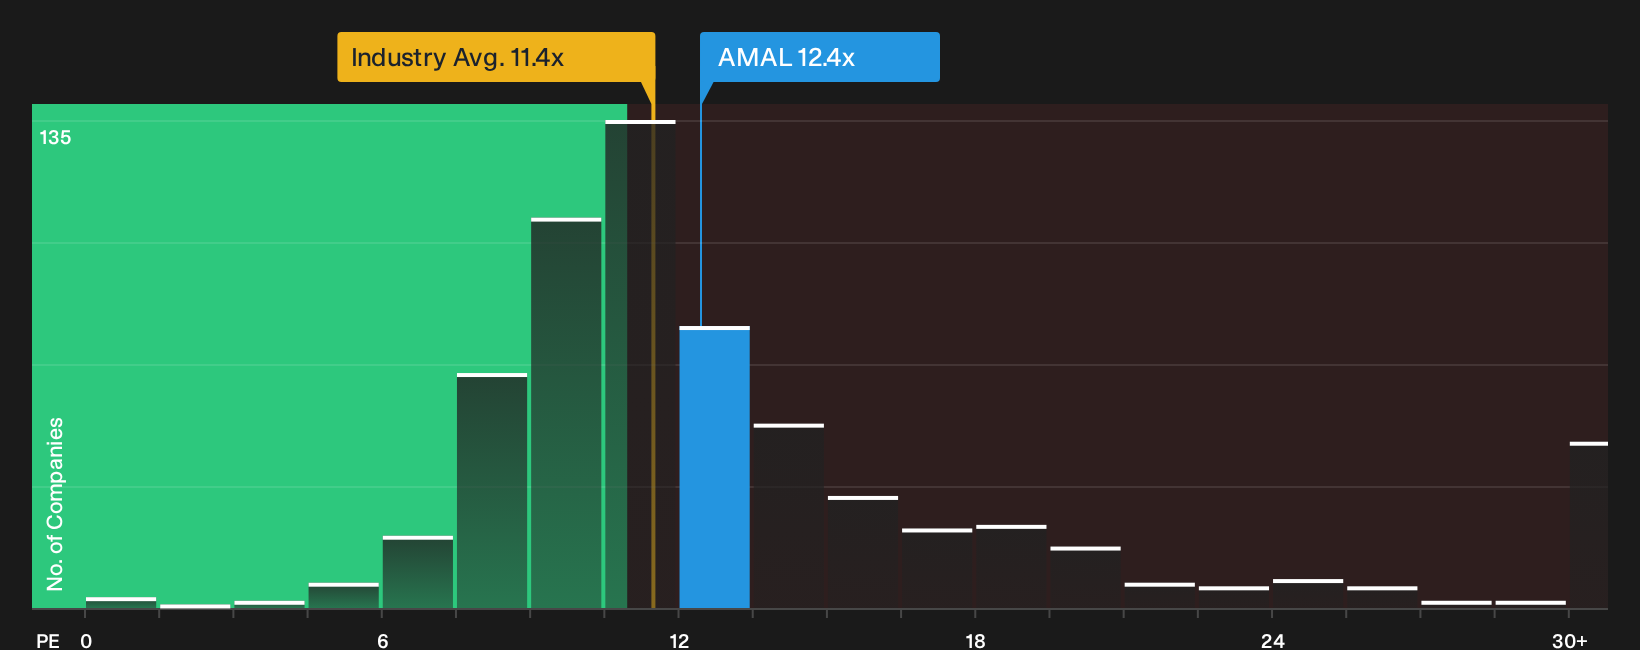
On earnings power, Amalgamated Financial screens as a mixed picture. The stock trades on a P/E of 12.4x, slightly richer than the US Banks group at 11.3x but a touch below close peers at 12.6x. The fair ratio sits at 12.7x, which suggests only a narrow cushion if sentiment cools.
For a deeper look at how this pricing compares with the fair ratio and sector, and what that might indicate for valuation risk, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Amalgamated Financial can pull opinions in different directions, so move quickly, review the underlying data, and weigh both sides for yourself with 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Amalgamated Financial?
If Amalgamated Financial has sharpened your focus, now is the time to widen your watchlist and look for other clear, data backed opportunities using Simply Wall Street’s tools.
- Target income first and shortlist companies with strong yields and robust payout profiles using the 8 dividend fortresses.
- Look for quality at a discount by scanning the 20 high quality undiscovered gems, which pair solid fundamentals with under the radar attention.
- Dial down risk and steady your portfolio by screening for 32 resilient stocks with low risk scores, which still offer compelling business quality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com