
Heidelberg Pharma (XTRA:HPHA) Stock Cools As Q3 Results Keep Losses In Focus
Heidelberg Pharma just dropped its Q3 2026 numbers, and the headline is blunt. Revenue landed at €1.9 million while the biotech swung to a net loss of €5.3 million after a profitable Q2. Yet the stock closed at €2.20, leaving the past 30 days down about 14% and the last week only slightly lower.
That mix of fading price pressure and fresh quarterly losses sets up a sentiment test. Traders are reacting to the red ink. Long term holders are staring at a deeper issue: the ongoing strain on earnings and the balance sheet that still hangs over every rally.
Like the science at Heidelberg Pharma but uneasy about the fresh loss and balance sheet strain? Scan the list of solid balance sheet and fundamentals stocks (203 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): €1.92 million vs. €0.05 million (very large increase from a very low base)
- Net Loss (Q3 2026 vs. Q3 2025): €5.26 million loss vs. €8.46 million loss (loss narrowed)
- Basic EPS (Q3 2026 vs. Q3 2025): €0.12 loss per share vs. €0.18 loss per share (per share loss reduced)
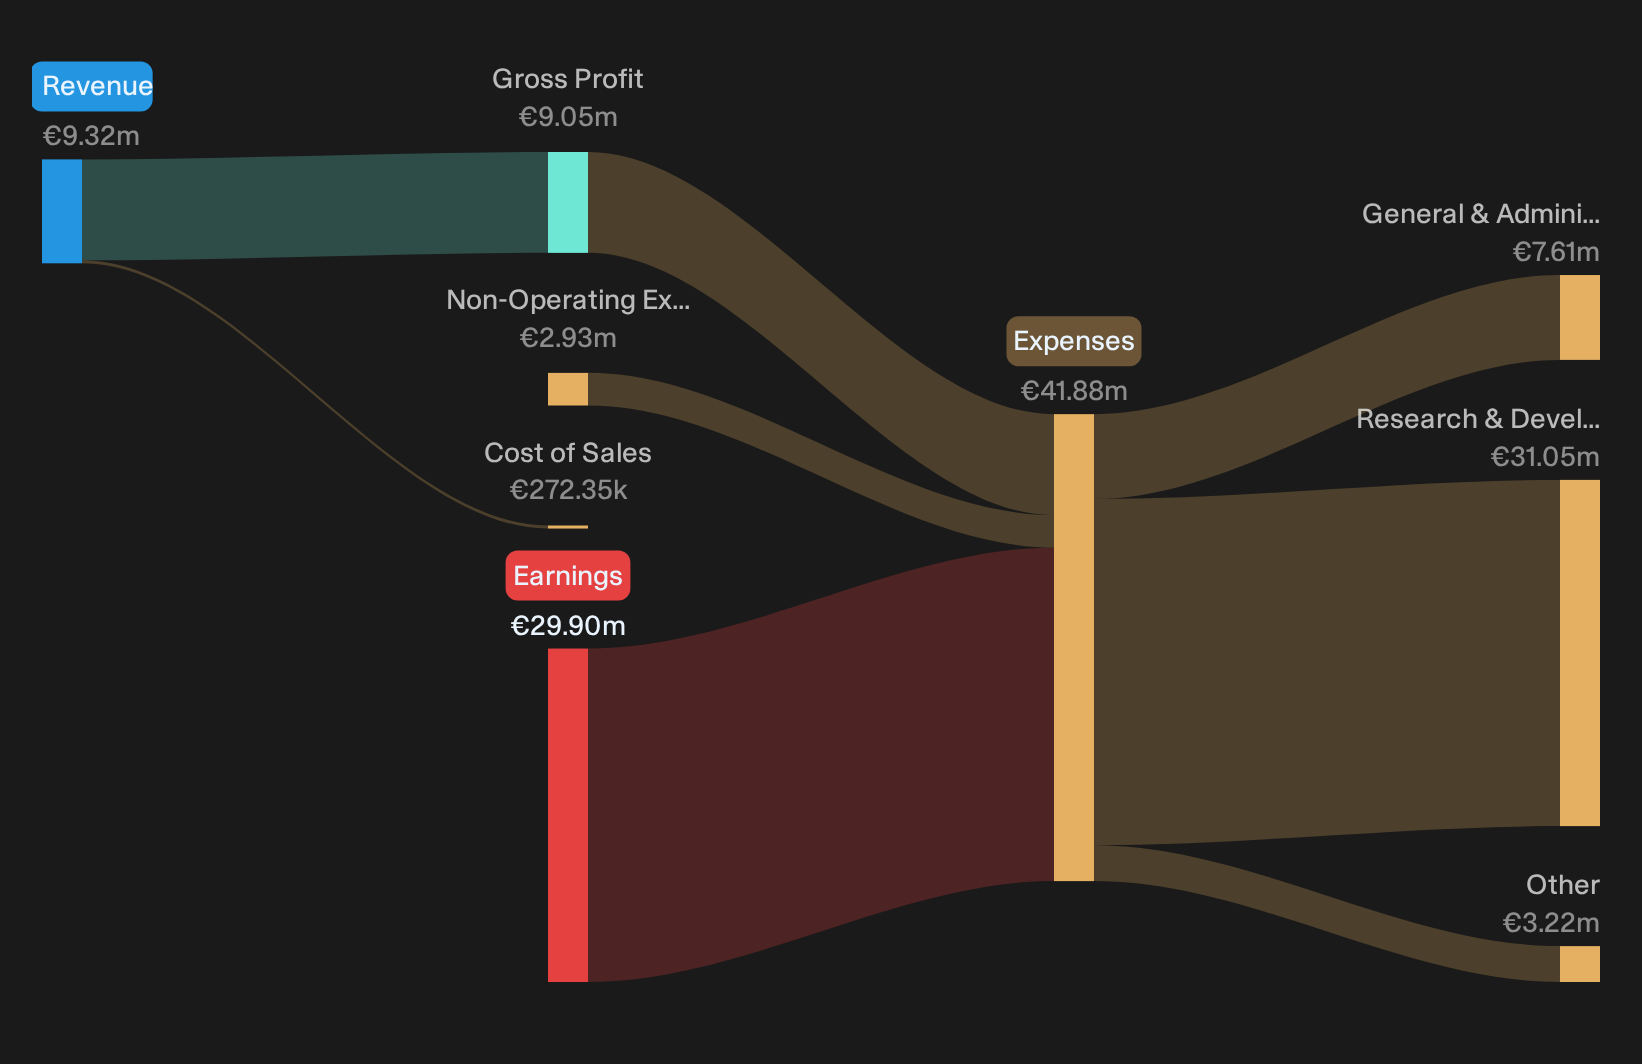
- Trailing 12-Month Revenue (Q3 2026 vs. Q3 2025): €9.32 million vs. €3.04 million (very large increase over the year)
Ask Charlie what keeps Heidelberg Pharma’s losses climbing despite revenue growth.
Heidelberg Pharma bull case meets early milestones
Optimists argue Heidelberg Pharma is quietly building multiple future income streams around ATAC oncology programs.
"Heidelberg Pharma's ATAC technology and multiple pipeline candidates offer potential for new revenue streams and long-term growth in earnings."
Recent numbers line up partly with that idea. Trailing 12 month revenue of €9.32 million is far above the prior €3.04 million, helped by partner activity such as the Huadong milestone. The firm has also moved HDP 101 into a Phase IIa expansion, which matches the narrative of clinical progress that could underpin partnerships rather than immediate profitability.
Bear case on funding risks still has teeth
On the downside, critics focus on concentration in HDP 101 and fragile funding that could strain Heidelberg Pharma if execution slips.
"Financial dependency on milestone payments, such as those from the Healthcare Royalty agreement and potential U.S. FDA approval, introduces uncertainty that could undermine cash flow stability and overall financial health."
Q3 tells that story clearly. Revenue of €1.92 million and a net loss of €5.26 million show operations relying heavily on irregular partner income while expenses stay high. The auditor has already raised going concern doubts, and the share price is down about 14% over 30 days, which aligns with persistent concern about liquidity and milestone timing.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Hunt For Quiet Fundamental Shifts
Heidelberg Pharma highlights how clinical milestones can arrive alongside sizeable reported losses. The real opportunity could be spotting stocks where fundamentals and current market pricing do not quite line up yet.
- Company 1 - 29% below our estimate - expand secured retail and business lending while opening new branches to deepen low cost deposits.
- Company 2 - 19% below our estimate - win high specification power cable projects tied to grid upgrades and data centre electricity demand.
- Company 3 - 33% below our estimate - shift toward higher margin seeds, specialty chemistries and bio based crop protection to support sustainable yield gains.
Those are three of them. See all 193 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com