
Coal Mine Sale Could Be A Game Changer For Sojitz Stock (TSE:2768)
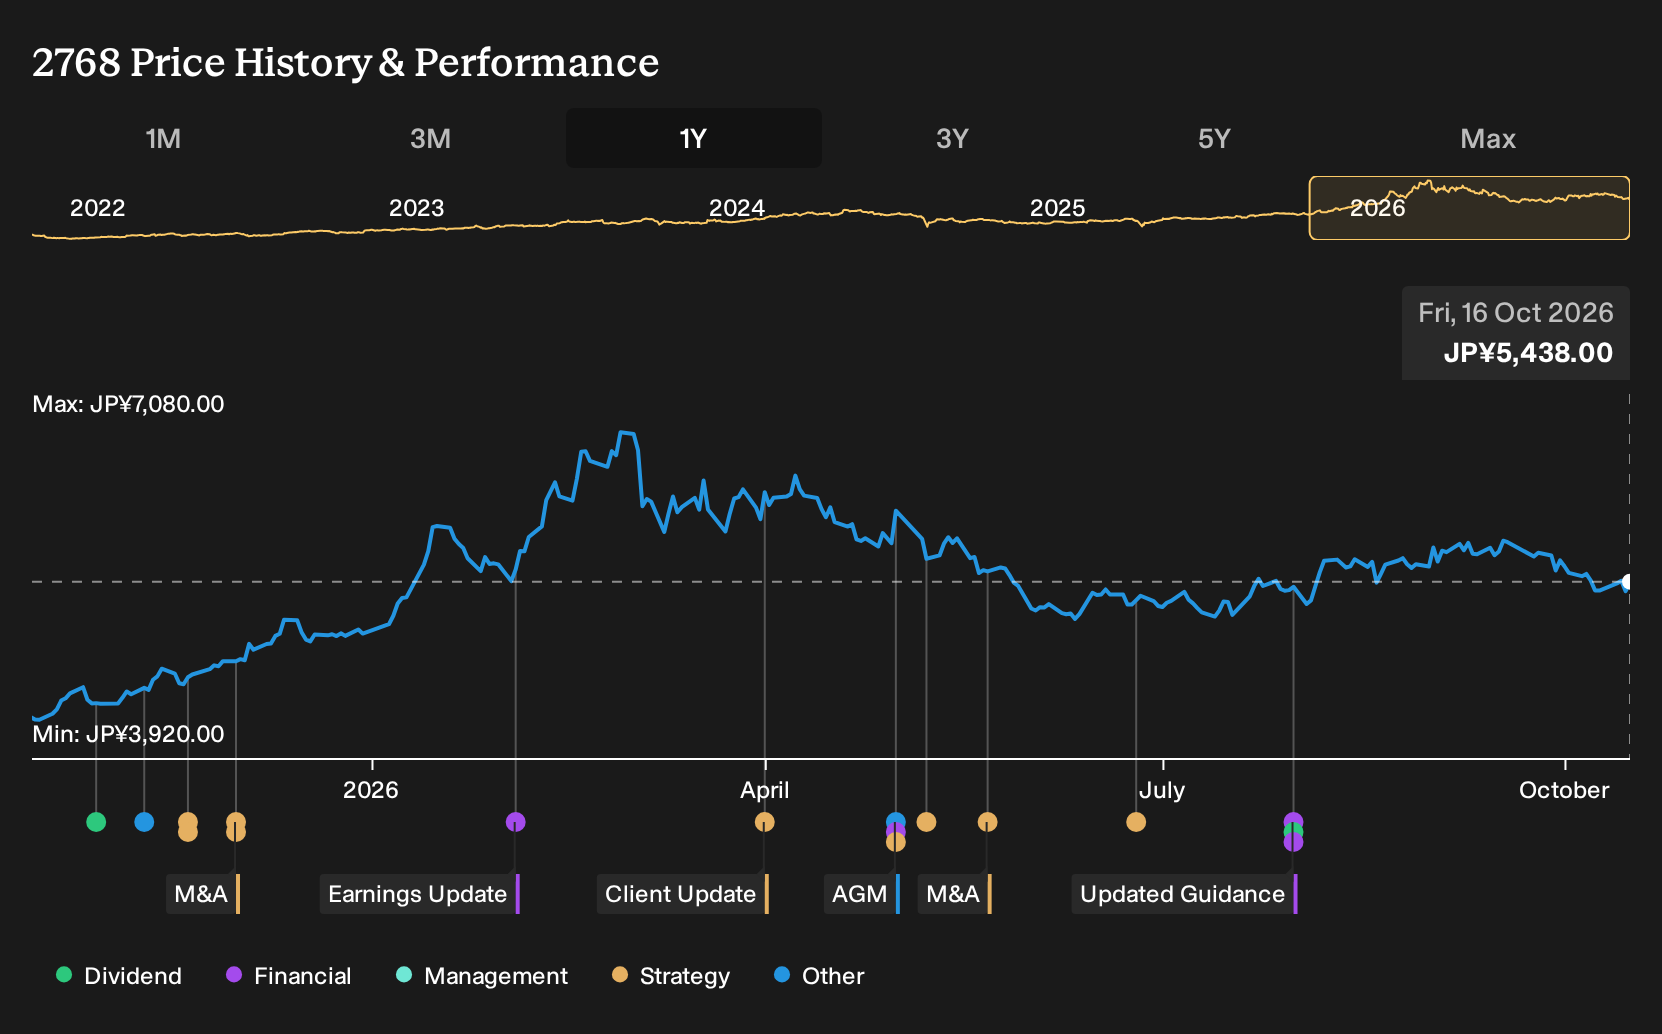
- Sojitz has agreed to sell its entire stake in the Gregory Crinum metallurgical coal mine in Queensland, Australia, as part of its structural reform program and to reduce exposure to Australian coal operations.
- This full exit from Gregory Crinum frees capital from a resource asset under pressure that Sojitz can potentially redirect toward non-resource projects highlighted in its medium-term plan.
- We will now look at how Sojitz's investment narrative could shift as it exits the Gregory Crinum coal mine in Australia.
Scan how Sojitz's coal exit compares with other businesses reshaping their portfolios by running your eye over 22 resilient stocks with low risk scores that aim to keep risk scores on a tighter leash.
Sojitz Investment Narrative Recap
To own Sojitz, you need to be comfortable with a trading and investment group that is still rebalancing away from coal and other restructured units toward infrastructure, energy solutions and chemicals. The Gregory Crinum exit appears aligned with that shift and, on its own, does not significantly change the near term story around earnings mix or cash generation.
The nearer catalyst is how effectively Sojitz redeploys capital into higher quality projects under MTP 2026 while keeping execution tight in segments such as fertilizers and consumer businesses. The main risk is that divestments and underperforming areas such as coal or used car operations continue to weigh on profit and return on equity for longer than planned.
Among recent developments, a key reference point for this coal sale is management's broader portfolio rotation under MTP 2026, including plans to address Australian coking coal exposure and redirect investment toward infrastructure and critical materials. The Gregory Crinum disposal sits within that framework and is best viewed alongside the existing project pipeline.
For shareholders, the focus is on how quickly that freed capital contributes to more stable earnings from areas such as infrastructure concessions, energy solutions and chemicals, and whether this supports Sojitz's targets for profit quality and cash flow. Execution on these projects, together with discipline around debt coverage and dividend sustainability, remains central to the near term balance of risks and potential rewards.
Sojitz Forecasts Behind the Coal Exit
Analyst estimates help frame what Sojitz is trying to achieve as it recycles capital out of assets like Gregory Crinum and into infrastructure, energy solutions and chemicals. The forecasts are not guarantees, but they show how the coal exit sits alongside an expected tilt toward more fee based and contracted earnings over the next few years.
Sojitz's narrative projects revenue of ¥3,166.5 billion and earnings of ¥148.6 billion by 2029. This rests on 1.9% yearly revenue growth and an earnings increase of about ¥35.8 billion from ¥112.8 billion today.
Uncover why Sojitz's fair value indicates a 19% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate Sojitz angle is much more optimistic about earnings from new projects rather than coal exits. The most bullish analysts were sketching out revenue of ¥3,462.0b and earnings of ¥171.2b by 2029 before this Gregory Crinum sale. Use those upbeat assumptions as a contrast and ask how this news might reshape that storyline.
Explore another Sojitz fair value estimate, including one that suggests up to 19% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sojitz research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sojitz. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sojitz's overall financial health at a glance.
Looking for more Sojitz sized investment ideas?
If this Sojitz story has you thinking about position sizing, risk and balance sheets, it can help to scan a wider set of companies with filters that match your own priorities.
- If you want stability to be front and center, start with a list of solid balance sheet and fundamentals (21 results) that can handle tougher conditions without stretching the finances.
- If value is your priority, sift through 14 high quality undervalued stocks where fundamentals and pricing look more closely aligned.
- If you prefer to back future potential before it hits the mainstream, run through 73 high quality undiscovered gems that combine quality metrics with lower profile coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com