
Why J.B. Hunt Transport Services (JBHT) Is Back In Focus
J.B. Hunt Transport Services (JBHT) is back in focus after third quarter results on 15 October, with revenue and earnings slightly ahead of expectations but pressured by higher operating costs and tighter margins.
That mixed third quarter message from J.B. Hunt Transport Services landed in a market that has already pushed the share price up 19.6% year to date. At the same time, the 30 day share price return is down 13.8% and the 90 day share price return is down 19.3%. However, the 1 year total shareholder return of 39.9% signals that longer term holders have still seen strong gains as sentiment now adjusts to higher costs and margin pressure at a US$235.31 share price.
Scan for other freight and logistics stocks reacting to the same cost and margin pressures by reviewing our hand picked list of solid balance sheet and fundamentals (25 results).
The question now is whether J.B. Hunt Transport Services is being repriced for real cost pressure in the business or if sentiment has simply swung too far after a strong 1 year run. This is where valuation comes in next.
Most Popular Narrative: 13% Overvalued
J.B. Hunt Transport Services is trading at $235.31 against a widely followed fair value narrative of $208.61. As a result, the story investors are reacting to focuses on how much of today’s price rests on cost control, capital deployment, and freight mix assumptions.
The assumed bearish price target for J.B. Hunt Transport Services is $208.61, which represents up to two standard deviations below the consensus price target of $282.17. This valuation is based on what can be assumed as the expectations of J.B. Hunt Transport Services's future earnings growth, profit margins and other risk factors from analysts on the more bearish end of the spectrum.
See why 1 investors see J.B. Hunt Transport Services as 13% overvalued.
Result: Fair Value of $208.61 (OVERVALUED)
Still, if J.B. Hunt Transport Services continues reducing structural costs and shippers continue consolidating freight with larger carriers, this bearish narrative could face real pushback.
Find out about the key risks to this J.B. Hunt Transport Services narrative.
Another View: Cash Flows Tell A Different Story
The bearish narrative around J.B. Hunt Transport Services leans heavily on analyst price targets and P/E based signals that frame the stock as 13% overvalued at $235.31 versus a $208.61 fair value. Yet the Simply Wall St DCF model points in the opposite direction, with J.B. Hunt trading about 21.4% below an estimated future cash flow value of $299.20. For an investor weighing narratives, that clash between earnings multiples and cash flow math raises a simple question: which lens deserves more weight when the numbers disagree this clearly?
Look into how the SWS DCF model arrives at its fair value.
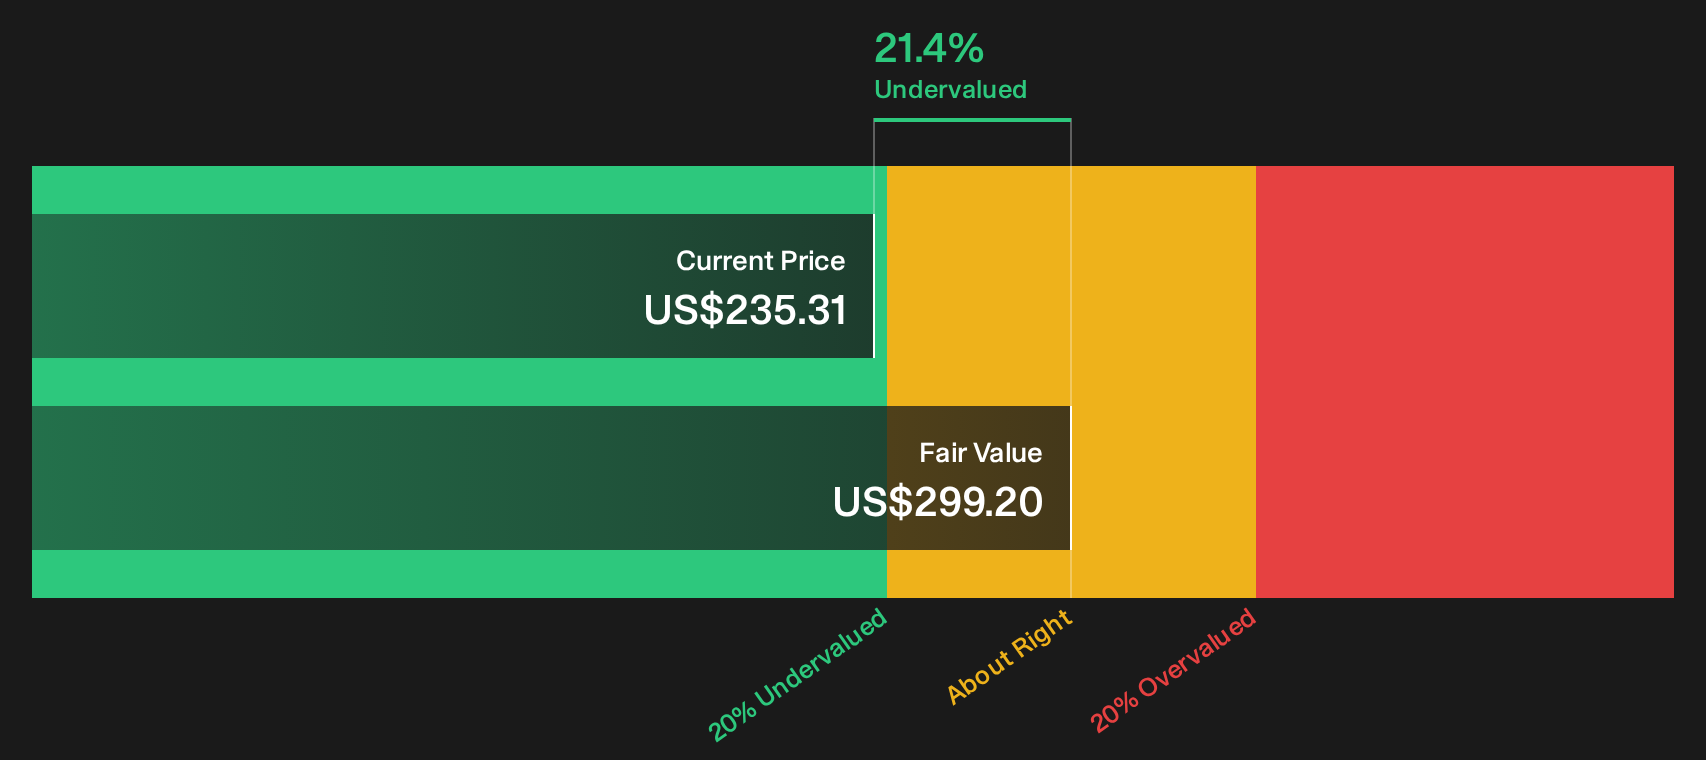
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out J.B. Hunt Transport Services for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on J.B. Hunt Transport Services can leave anyone uncertain. Consider reviewing the data for yourself, including its identified 3 key rewards.
Looking for more investment ideas beyond J.B. Hunt Transport Services?
If J.B. Hunt Transport Services has you thinking harder about pricing and risk, consider broadening your watchlist with other opportunities filtered for quality, income, and resilience.
- Target long term compounding potential by reviewing companies that screen as 33 high quality undervalued stocks with solid fundamentals doing the heavy lifting behind the numbers.
- Strengthen your income stream by checking out a curated group of 8 dividend fortresses that focus on meaningful yield supported by robust cash generation.
- Dial back portfolio stress by assessing 32 resilient stocks with low risk scores that place emphasis on balance sheet strength and more measured volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com