
Amgen (AMGN) Nears Earnings, Is The Stock Pricey?
Why Amgen’s Upcoming Earnings Matter For Investors
Amgen (AMGN) heads into its 3 November 2026 earnings release with expectations for a modest uptick in earnings per share and revenue compared with the same quarter a year ago.
Recent trading has been strong, with Amgen’s 1 month share price return of 15.54% and 90 day share price return of 18.49% lifting the stock to $434.03. A 1 year total shareholder return of 50.80% signals momentum that recent trial wins and demographic tailwinds have helped reinforce.
Seize the momentum around Amgen’s earnings watch and aging-theme therapies by scanning a curated set of 34 healthcare AI stocks that could be next in line for attention.Amgen’s surge has come alongside solid reported revenue and net income growth, which points to business progress. However, a price above the average analyst target hints at sentiment running ahead. How does that mix show up in the valuation?
Most Popular Narrative: 21% Overvalued
Amgen’s last close at $434.03 sits well above the fair value of $359.98 implied by the most followed narrative, which frames today’s price as baking in a demanding obesity-drug success story.
The "Amgen 2027 Bull Case" relies on a classic top-line fallacy: assuming that macro obesity market growth and FDA's CNPV (Commissioner’s National Priority Voucher) tailwinds will automatically trigger a re-rating.
Here is the cold, data-driven reality:
See why 6 investors see Amgen as 21% overvalued.
Result: Fair Value of $359.98 (OVERVALUED)
Still, a clean MariTide launch or slower erosion in legacy drugs like Prolia and Enbrel could quickly challenge the overvaluation case associated with Amgen today.
Find out about the key risks to this Amgen narrative.
Another View On Amgen’s Valuation
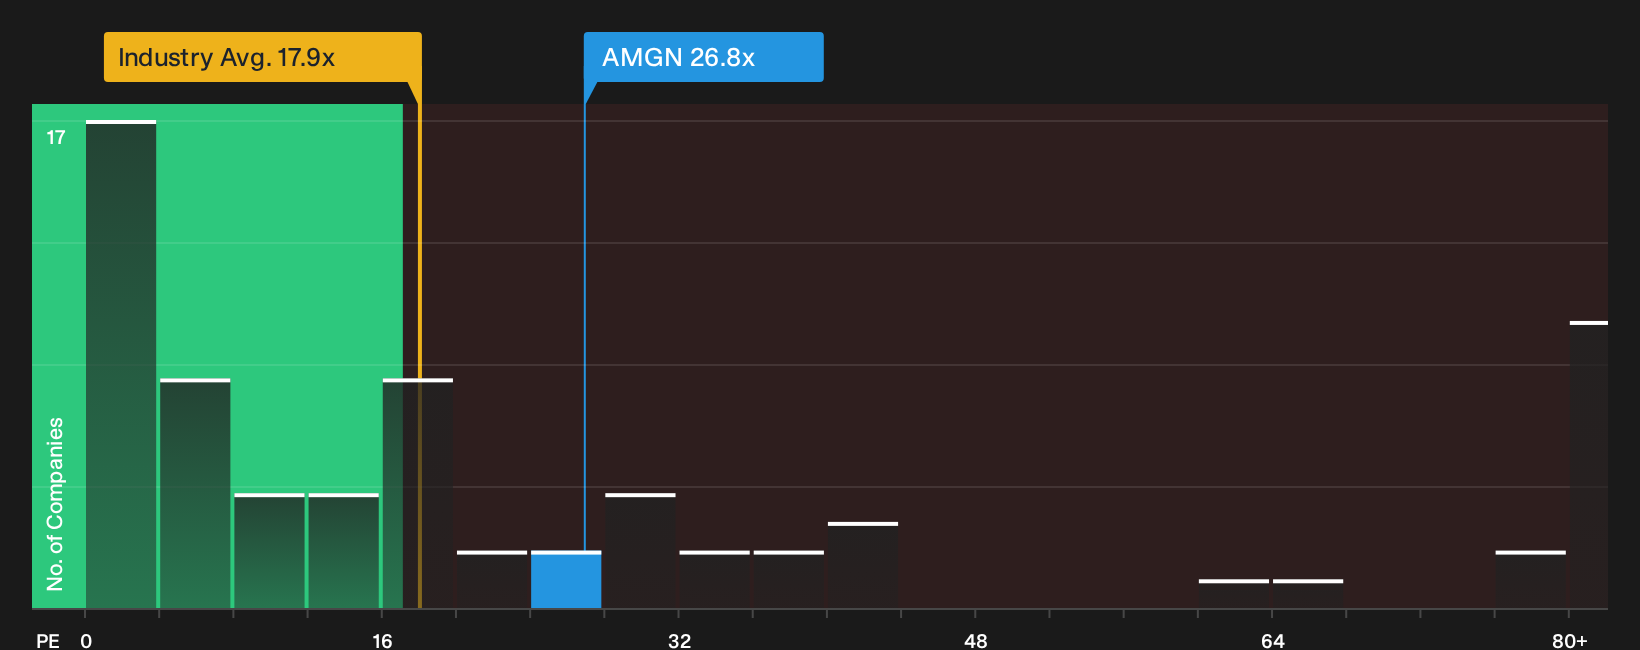
While the leading narrative frames Amgen as 21% overvalued at $434.03 versus a $359.98 fair value, the multiples picture is far less one sided. The stock trades on a P/E of 26.8x, which is below an estimated fair ratio of 31.6x and also below peers at 42.3x.
That mix of richer pricing than the broader US Biotechs industry at 17.9x, yet a discount to both the fair ratio and closer peers, suggests investors are paying up, but not at any price. The real question is which story the market leans into next: the narrative fair value or the earnings-based one.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Amgen’s price and fair value can feel messy, so move fast and look at the full risk and reward picture yourself. The clearest way to weigh both the concern and optimism already in the data is to review the 4 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Amgen?
Do not stop at Amgen when a wider opportunity set is sitting in front of you. Use the Simply Wall Street Screener now or risk missing the next idea that fits your style.
- Target potential mispricings by reviewing a focused set of 33 high quality undervalued stocks that pair quality fundamentals with more modest expectations baked into current prices.
- Strengthen your income playbook by scanning a curated pool of 8 dividend fortresses that aim to combine higher yields with business resilience.
- Dial down portfolio stress by concentrating on a 32 resilient stocks with low risk scores that prioritises resilient balance sheets and steadier risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com