
Leadership Reshuffle Could Be A Game Changer For The Hartford Stock (HIG)
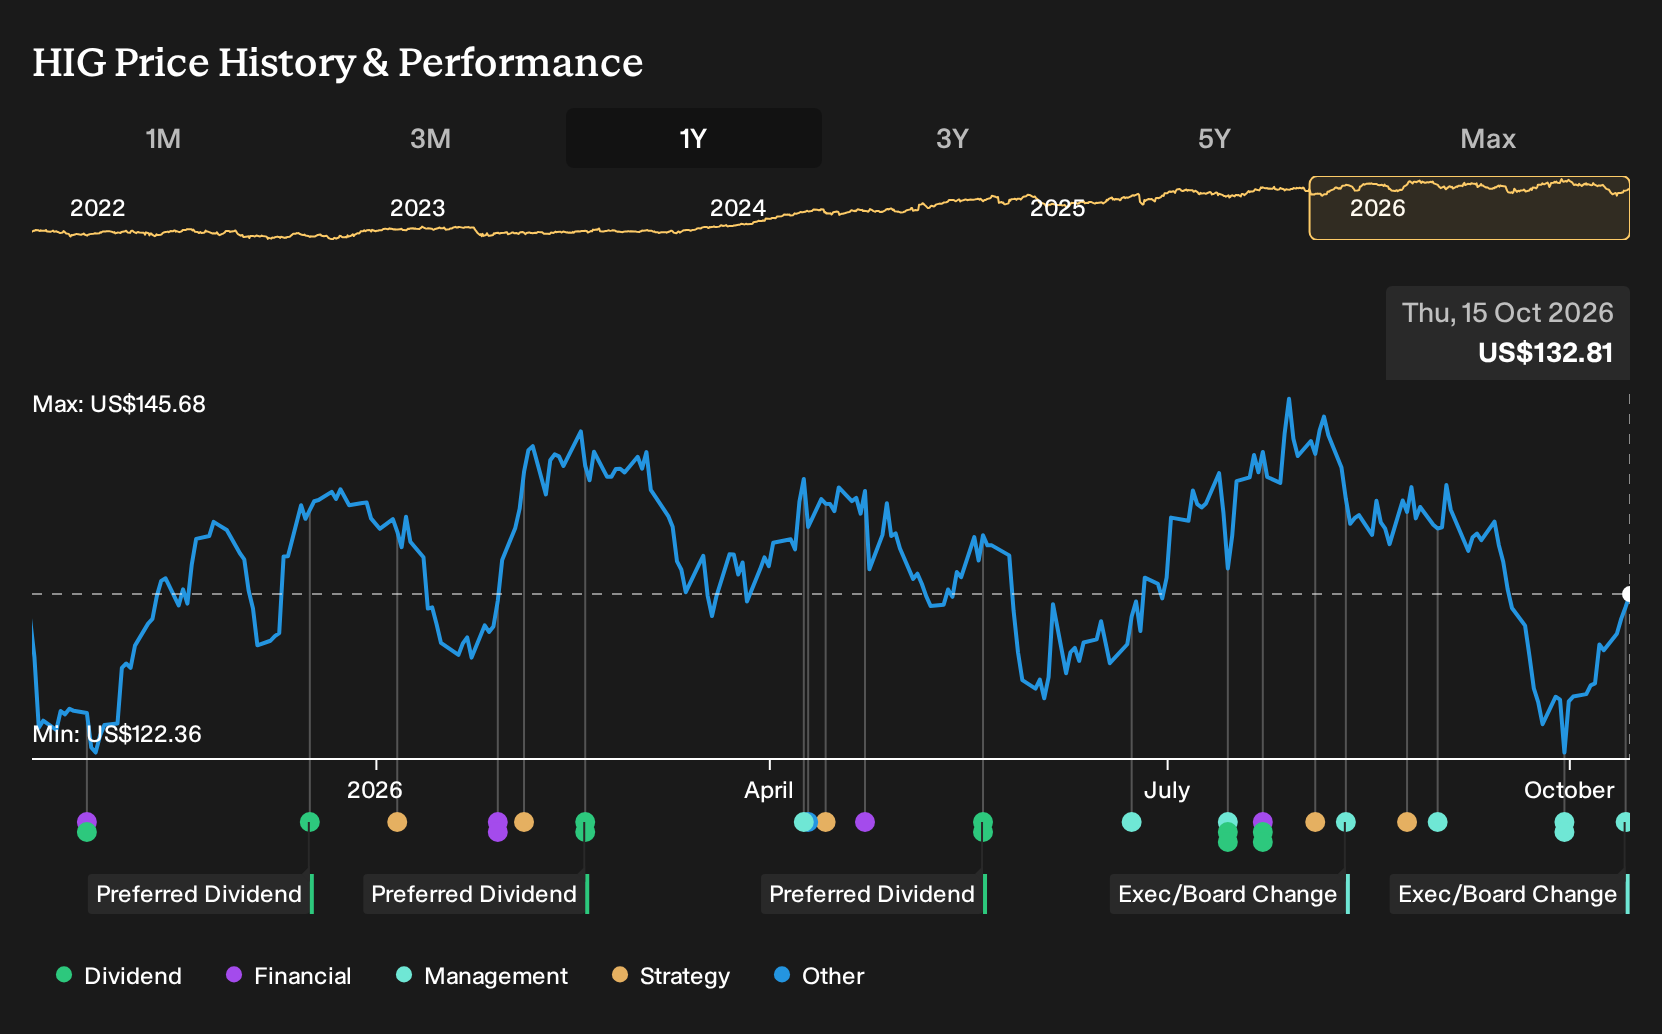
- Hartford Insurance Group reshaped its leadership structure, expanding responsibilities for its chief information officer and chief claims officer, and appointing long-serving finance executive James M. Yanosy as chief risk officer after the prior risk and data leaders decided to leave.
- The move to combine Data and Artificial Intelligence with Technology under CIO Shekar Pannala signals a tighter link between Hartford Insurance Group’s technology spending, risk oversight, and day to day underwriting and claims execution.
- We will now look at how Hartford Insurance Group’s refreshed risk leadership could influence the broader investment narrative around technology execution.
Scan how Hartford Insurance Group’s leadership shift around technology, data and risk compares with peers by filtering for insurers inside our hand picked 32 resilient stocks with low risk scores.
Hartford Insurance Group Investment Narrative Recap
To own Hartford Insurance Group, you really need to believe the core commercial and employee benefits engines can stay disciplined on underwriting while continuing to squeeze more efficiency out of technology and AI. The leadership reshuffle around data, tech and risk looks incremental rather than transformative for those near term goals, so the immediate operating outlook is largely unchanged.
The key short term swing factor still sits in underwriting results, especially catastrophe experience and competitive pressure in Personal Insurance, where pricing and volume tension could offset gains elsewhere. The biggest risk remains a run of large events or tougher regulation that crimps margins while earnings expectations are already pointing to declines over the next few years.
The most relevant development tied to this leadership news is Hartford Insurance Group’s push to extend AI and digital tools in underwriting and claims, with 75% of new small business quotes already processed straight through. Folding Data and AI into Technology under the CIO directly aligns with that operational focus on lower expense ratios and faster decisions.
If execution on this tech stack improves, it could support the existing catalysts around small and midsize commercial customers, E&S binding and Employee Benefits without changing the fundamental risk profile. For investors, the story still hinges on whether this more integrated tech and risk setup turns into consistent underwriting discipline while earnings are forecast to decline and catastrophe and competitive pressures remain active factors.
What The Hartford’s Forecasts Assume
Hartford Insurance Group's narrative projects US$31.0b revenue and US$3.7b earnings by 2029. That profile uses a 1.9% yearly revenue growth rate and implies an earnings decline of US$0.4b from US$4.1b today.
Uncover how Hartford Insurance Group's fair value indicates a 12% potential difference from its current price before the market closes that gap.
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community stretch from US$143 to about US$312 per share, so opinions on Hartford Insurance Group already span more than a 2x range. When you also consider catastrophe risk, regulatory friction in Personal Insurance, and capital moves around buybacks, you get sharply different narratives that are worth exploring side by side.
Explore 4 other Hartford Insurance Group fair value estimates, including one that suggests it could be worth just $143.00.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis and judgment.
- A great starting point for your Hartford Insurance Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hartford Insurance Group. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Hartford Insurance Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Hartford Insurance Group?
If the Hartford Insurance Group story has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you filter for businesses that better match your risk tolerance and income goals.
- For investors who care most about resilience, start with companies that score well on balance sheet strength through the list of solid balance sheet and fundamentals (25 results).
- If you are hunting for potential mispricings with solid fundamentals, cast the net wider using our screener focused on 20 high quality undiscovered gems.
- Income focused investors who want cash payouts front and center can zero in on companies offering 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com