
Where Twist Bioscience Goes After A 370% Climb
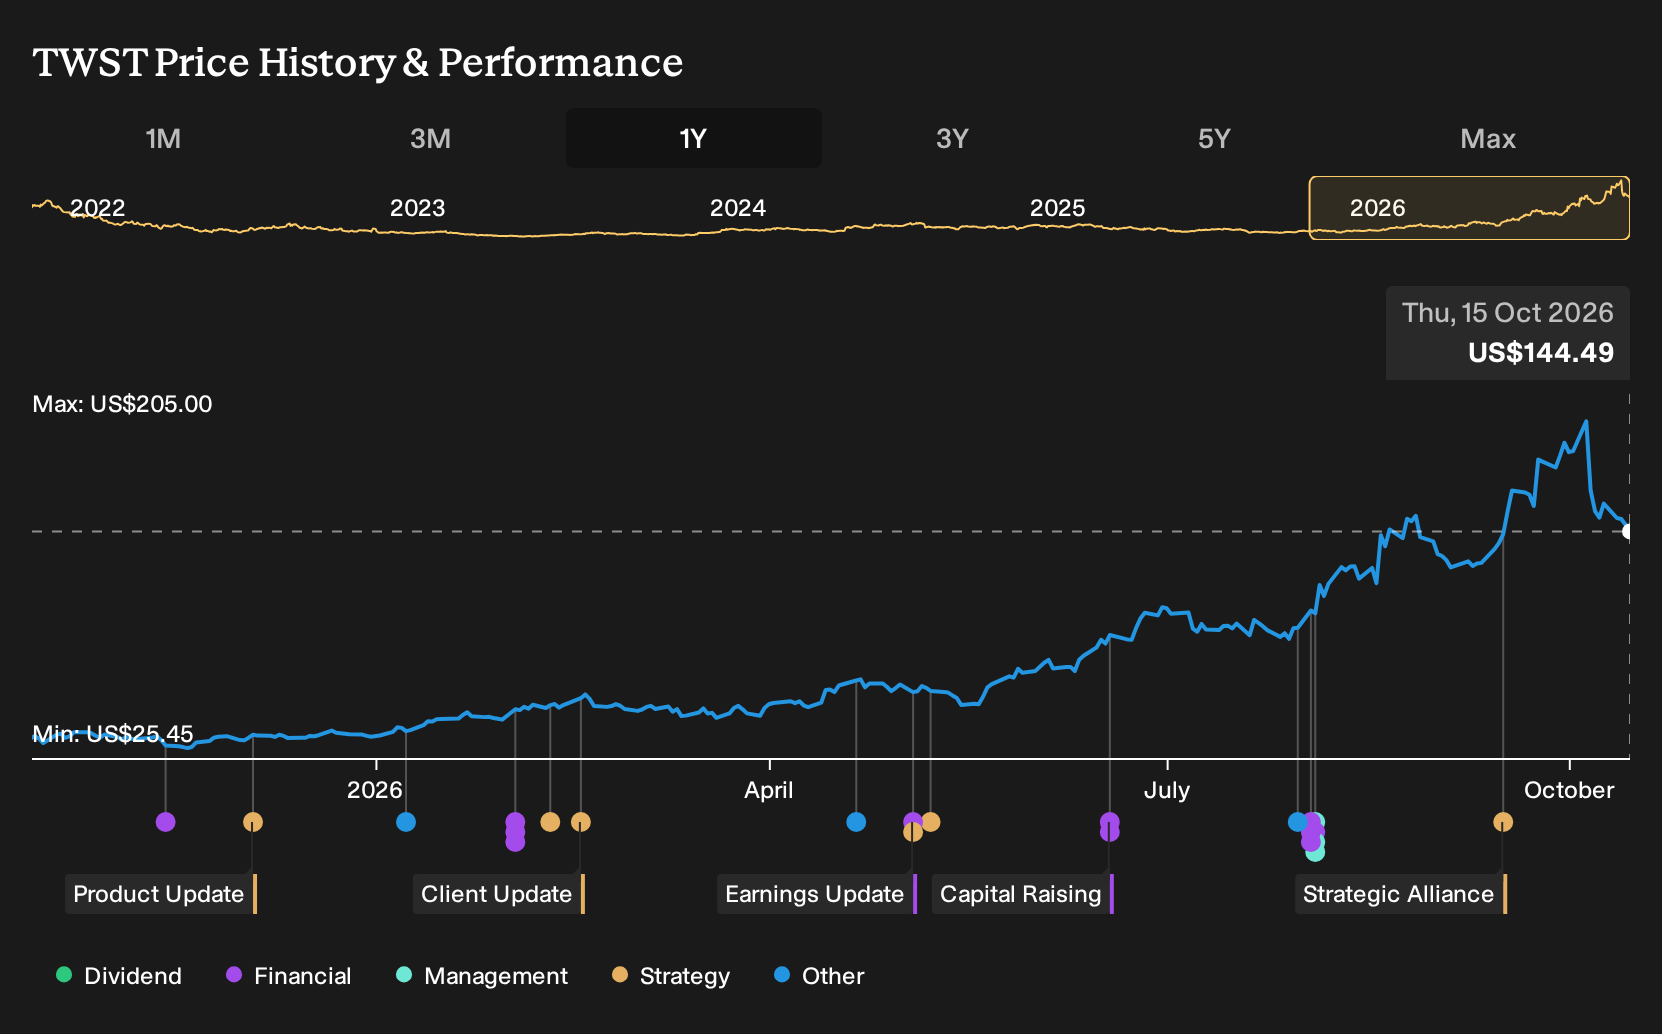
Twist Bioscience spent this year in the headlines for Complex Genes and high profile AI drug discovery deals, yet one contract stands out for sheer ambition. Holding Twist Bioscience over the past year would have returned 369.9%, including dividends. If you had been deciding on 15 October 2025, you would have had to weigh those early arguments about SynBio and NGS demand against widening losses and capital needs. Were those long term bets clear enough at that point to justify that leap?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The move put Twist Bioscience in the middle of this trade. Scan 34 healthcare AI stocks for other companies exposed to it.
The Two Competing Stories Around Twist Bioscience
The shares cost US$32.04 at the start of the period, so anyone looking at Twist Bioscience then had to decide which story felt more plausible.
The bullish narrative put fair value at US$42.14, 32% above the start price, built on an assumption of 16.7% annual revenue growth and profit margins rising to 14.2% over three years.
The bearish view set fair value at US$25 and relied on a 15.4% growth assumption while highlighting customer concentration and DNA synthesis commoditization as key threats to future margins.
What The Results Changed For The Twist Bioscience Story
Twist Bioscience reported Q3 2026 revenue of US$118.4 million versus US$96.1 million in Q3 2025, which leaned toward the bullish case that assumed ongoing SynBio and NGS demand. Profit told a different story. The business moved from net income of US$20.4 million to a loss of US$35.1 million, and net margin fell from 21.2% to 29.6% negative, so the profitability path in the optimistic narrative remained unproven. Overall, the evidence cut both ways.
The key assumption here was that higher sales would eventually support healthier earnings. When you look at another high growth stock, check whether rising revenue is matched by stable or improving net margin and absolute profit in the reported numbers, rather than assuming the operating leverage will arrive on its own.
What Today's Twist Bioscience Price Already Assumes
Twist Bioscience now trades at US$144 after a 369.9% gain over the past year. The selected Narrative views its Fair Value as higher than that level, based on a specific reading of what current AI and NGS momentum could support.
The core pitch is that Twist Bioscience becomes an outsourced wet lab engine for AI drug discovery and MRD workflows. A buyer at today’s price has to judge whether AI driven demand can reliably convert into sustained gross margin expansion and positive adjusted EBITDA after Q4 FY26.
"Twist Bioscience is becoming a key outsourced wet lab layer for AI-driven discovery programmes, with customers using its platform to run tens of thousands of DNA designs and generate millions of assay data points, which can support higher volume therapeutics orders and increase future revenue density per AI customer."
One Narrative disagrees with today's price. → See where this Narrative says Twist Bioscience should trade
Before The Next Story Makes Headlines
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 27% below our estimate - builds specialized chips and connectivity solutions for hyperscale cloud and networking workloads.
- Company 2 - 49% below our estimate - uses a data-driven lending platform to attract small businesses and cross-sell banking services.
- Company 3 - 47% below our estimate - wins complex public infrastructure contracts while addressing increased labor and technology implementation challenges.
Three companies from the same screener. Open the full list of 33 companies trading below our fair value estimates →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com