
Broadridge Financial Solutions (BR) Faces A Valuation Split, Is It Overvalued Or Undervalued?
Broadridge Financial Solutions (BR) has drawn fresh attention after its recent closing share price of US$174.11, prompting investors to reassess what they are paying for its communications and financial technology services.
Recent trading has been choppy for Broadridge Financial Solutions, with the latest 1 day share price return of 3.5% and a 90 day share price gain of 16.1% set against a year to date share price decline of 21.0% and a 1 year total shareholder return that is down 21.3%. This suggests that short term momentum is improving, while longer term performance has been much softer.
See how Broadridge Financial Solutions compares with other potential rebound stories by checking our hand picked list of 33 high quality undervalued stocks, which combine quality fundamentals with room for sentiment to catch up.
Bulls view Broadridge Financial Solutions as a solid US$18.9b backbone of investor communications now trading at a discount, while bears point to the recent drawdown and sluggish long term returns. Which side matches the valuation numbers you are paying for?
Most Popular Narrative: 39% Overvalued
Using the most followed narrative as a guide, Broadridge Financial Solutions screens with a fair value of $125 against the latest close at $174.11. That gap frames the current rebound as a pricing debate rather than a clear-cut bargain.
Broadridge does not get much attention, but it runs something close to a toll booth on the U.S. stock market. It processes proxy materials and shareholder votes for roughly 80% of all U.S. shares outstanding. If you have ever voted your shares or gotten a fund prospectus in the mail, it probably went through Broadridge's pipes.
See why 2 investors see Broadridge Financial Solutions as 39% overvalued.
Result: Fair Value of $125 (OVERVALUED)
Still, that quiet monopoly pitch around Broadridge Financial Solutions could crack if tokenized securities bypass traditional proxy plumbing or if regulation rewrites today’s SEC fee playbook.
Find out about the key risks to this Broadridge Financial Solutions narrative.
Another View: SWS DCF Flags Undervaluation
The crowd narrative pins Broadridge Financial Solutions at $125 fair value, yet the SWS DCF model points in the opposite direction. On that framework, the current $174.11 price screens well below an estimated future cash flow value of $361.80. This implies investors are paying roughly half of that cash flow estimate.
The gap between these two fair value markers raises a simple question. Is the market correctly discounting long term disruption risk, or is the cash flow model capturing strengths the headline narrative is missing? Look into how the SWS DCF model arrives at its fair value.
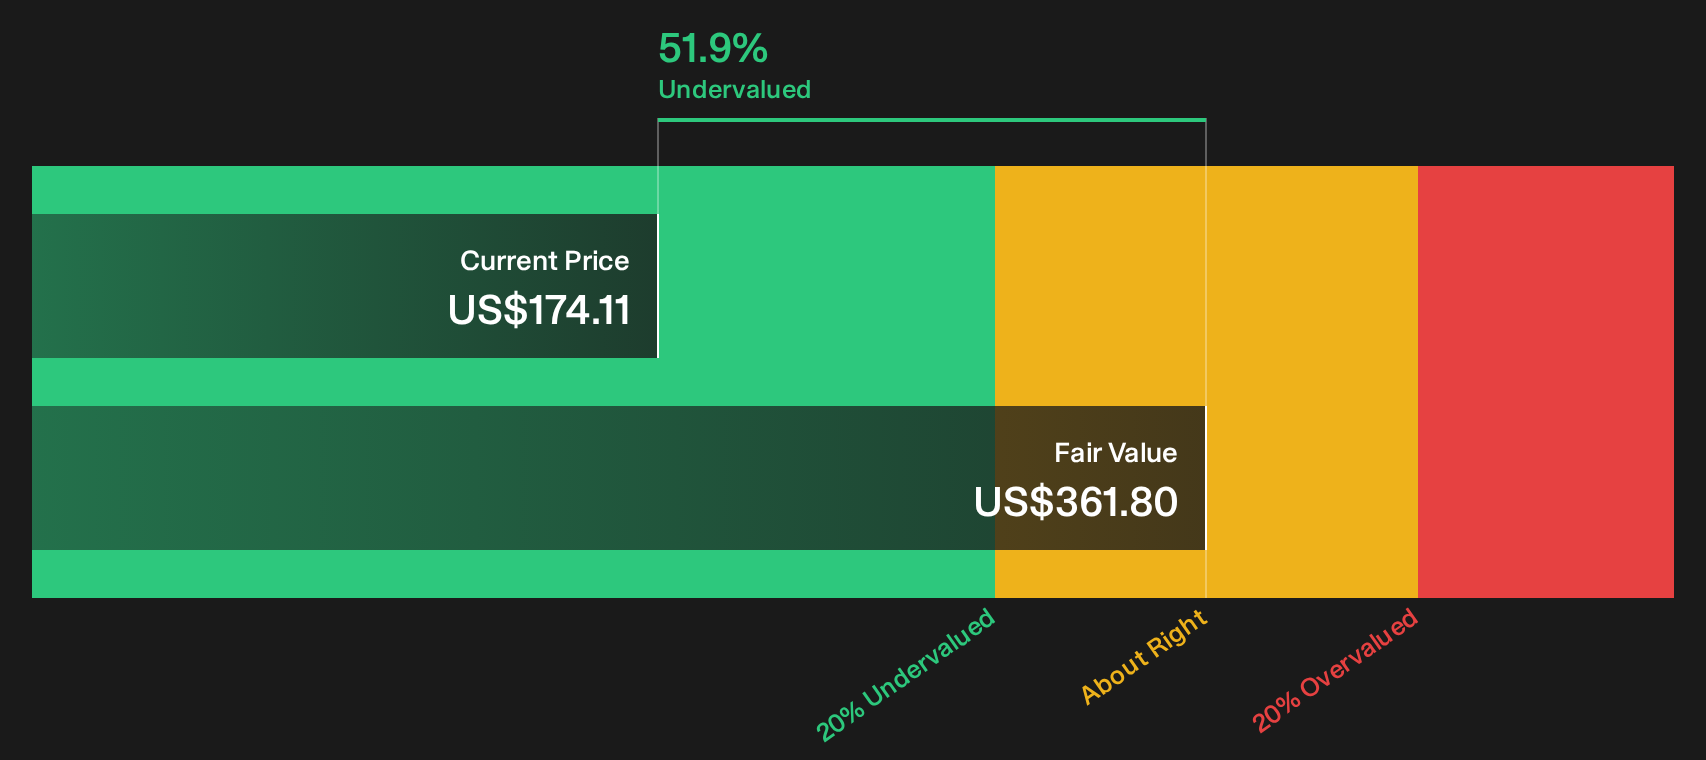
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Broadridge Financial Solutions for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Broadridge Financial Solutions can be energising rather than confusing if you move quickly and test the assumptions against the underlying numbers yourself. To weigh the balance between concern and optimism in a structured way, start with the 5 key rewards and 1 important warning sign.
Looking for more Broadridge style investment ideas?
If you stop with Broadridge Financial Solutions, you miss the broader opportunity set. Put a shortlist together now so the next move is intentional, not rushed.
- Target steadier compounding potential by scanning a curated 32 resilient stocks with low risk scores list that focuses on resilient businesses with stronger risk profiles.
- Hunt for mispriced quality by using the 20 high quality undiscovered gems filter to surface underfollowed companies with fundamentals that may not be fully appreciated yet.
- Prioritise financial resilience with a list of solid balance sheet and fundamentals (25 results) that highlights firms built on stronger balance sheets and healthier underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com