
Should Strong Q3 Revenue Require Action From Ecolab (ECL) Investors?
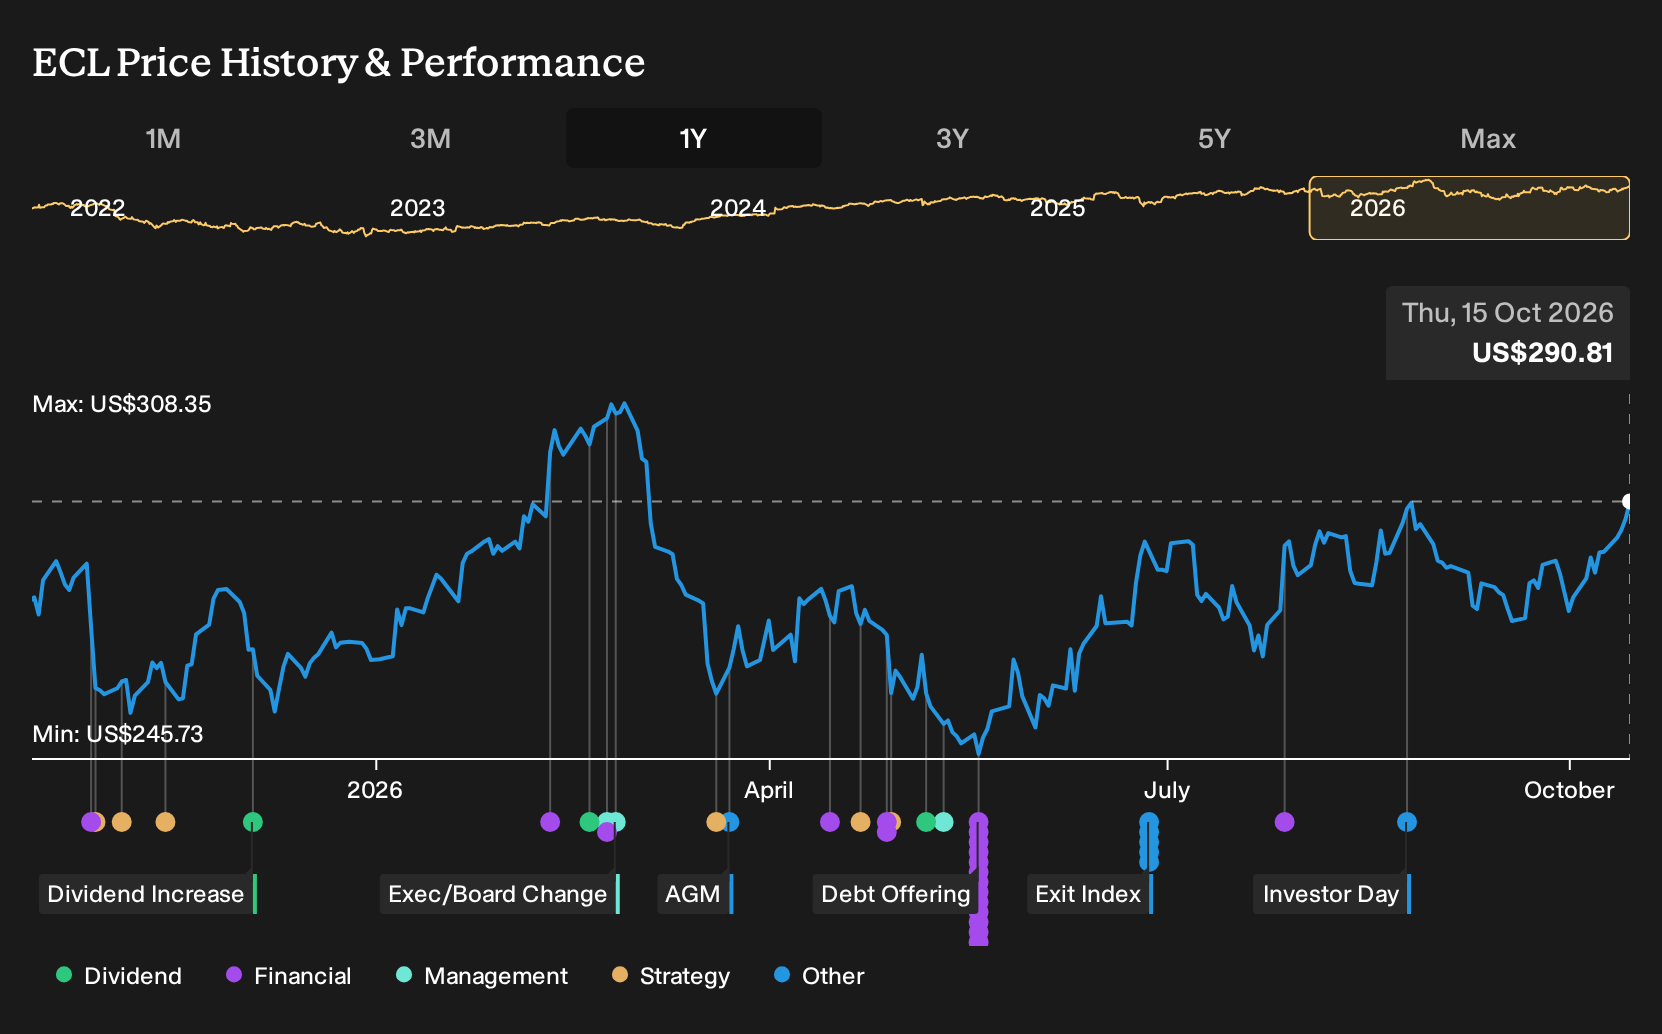
- Ecolab recently benefited from expectations that its Q3 revenue would sit above consensus forecasts, supported by organic growth and value based pricing, with management anticipated to reiterate 2026 adjusted EPS guidance and second half sales targets.
- The company is also seeing progress from its digital investments, as recurring software and service offerings increasingly contribute to operating income and reshape the earnings mix.
- We will now explore how Ecolab's investment narrative could shift as recurring digital revenue becomes a larger part of the story.
See how Ecolab's digital shift compares with other companies quietly rewiring their earnings mix through software and services by reviewing the hand picked 20 high quality undiscovered gems in this theme.
Ecolab Investment Narrative Recap
Ecolab is still a story about execution in its higher margin engines and digital platforms. To be a shareholder, you need to believe the One Ecolab approach, pricing discipline and growth businesses like Global High Tech, Life Sciences, Digital and Pest can keep lifting the earnings mix even while capex runs near 7% of sales. The near term swing factor is whether organic growth and value pricing hold up as some heavy industrial customers stay cautious.
The biggest near risk sits with softer demand in those industrial end markets and higher input costs from tariffs, which could squeeze net margins if pricing loses traction. Elevated spending and the CoolIT integration also weigh on near term free cash flow and earnings per share, so any stumble in digital execution or slower adoption of recurring software and service contracts would matter more than a single quarter’s revenue surprise.
The most relevant recent development is the expectation that Ecolab’s Q3 revenue lands above consensus, supported by organic growth and value based pricing, with management anticipated to reiterate 2026 adjusted EPS guidance and second half sales targets. That combination points to an operating plan still aligned with prior goals rather than a reset, which matters if you are watching for cracks in the thesis.
If those expectations hold, the key catalyst remains the same. Execution on digital offerings like Ecolab Digital and 3D TRASAR, plus the broader shift toward recurring subscription and service income, could gradually support operating income and reduce earnings volatility tied to chemicals and equipment cycles. The risk side is equally clear. Any slowdown in those digital and service lines, or weaker follow through from value based pricing as tariffs and commodities stay high, would pressure the path toward higher margins and returns on invested capital.
Ecolab Earnings Outlook Framed by Analyst Assumptions
Ecolab's narrative projects US$20.7b revenue and US$3.3b earnings by 2029. This is based on analysts assuming 7.2% yearly revenue growth and an earnings increase of about US$1.2b from current earnings of US$2.1b.
Uncover why Ecolab's fair value indicates a 12% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$268 and US$325, so retail views on Ecolab already span a wide price band. Those opinions were formed before the recent Q3 expectations and digital momentum. Recheck the risks around tariffs, industrial demand and capex, then compare several alternative viewpoints.
Explore another Ecolab fair value estimate, including one that suggests as much as 8% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ecolab research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ecolab. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ecolab's overall financial health at a glance.
Looking for more investment ideas beyond Ecolab?
If the Ecolab thesis has sharpened your thinking about quality, risk and earnings mix, you can use that same lens to scan a wider field of potential opportunities with the Simply Wall St Screener.
- If you want a starting point for finding high quality companies that the market may not fully appreciate, review a curated 33 high quality undervalued stocks that match those criteria.
- For investors who care as much about resilience as return potential, filter for 32 resilient stocks with low risk scores that balance fundamental strength with lower overall risk scores.
- If balance sheet strength is non negotiable for you, focus on the list of solid balance sheet and fundamentals (25 results) to see businesses that pair financial stability with sound fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com