
Is Clorox (CLX) Cheap, Or Are Its Earnings Fully Priced?
Clorox has seen its share price and investor sentiment reset over the past few years, and the question now is whether the current valuation is properly grounded in its earnings power. With the stock trading around US$86.20, the real focus is what that price says about the durability and quality of the profits behind this household products business.
- Over the past 5 years the share price has fallen 35.8%, which puts the spotlight squarely on whether the earnings profile still supports the current market valuation.
- The business model leans heavily on branded everyday essentials, so pricing power, input cost control, and cash conversion may support or constrain what investors are prepared to pay for each dollar of profit.
- There is a second opinion on Clorox worth weighing. See what analysts think Clorox's shares could be worth.
The issue now is whether Clorox's earnings are strong and reliable enough to justify the price investors are paying for the stock today.
For context when assessing whether Clorox's earnings support its current price, it can help to compare it with other household names screened for 33 high quality undervalued stocks
Is Clorox Fairly Priced on Earnings?
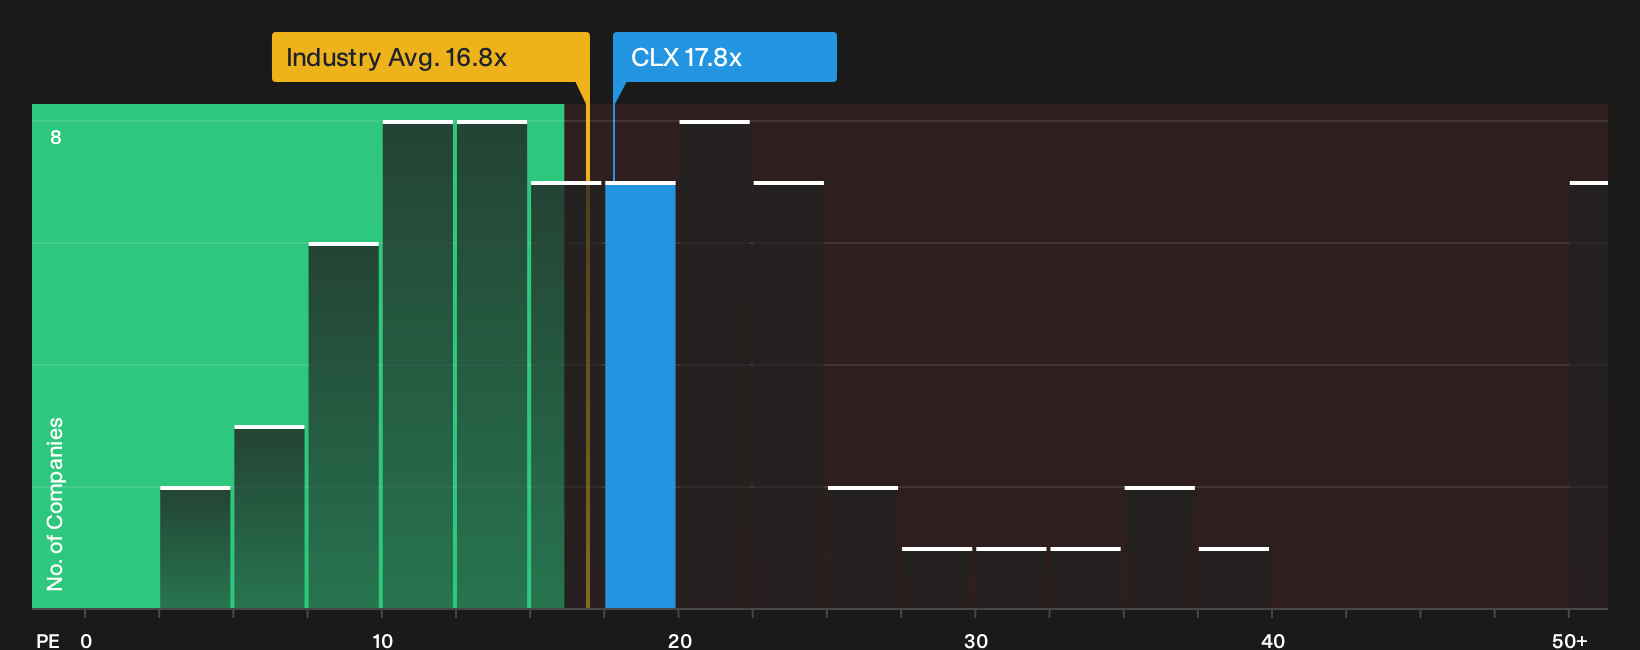
The P/E ratio fits Clorox because this is a mature branded goods business where earnings remain a key anchor for valuation. At roughly 17.8x earnings, Clorox trades below the peer group average of about 20.8x and slightly above the Household Products sector at around 16.8x, which places the stock in a middle band rather than at either extreme relative to similar companies.
The tailored fair P/E implied by the model, which blends Clorox's growth outlook, profitability, size and risk profile, sits close to this current multiple. That indicates the market price is broadly tracking what this framework suggests investors might pay for each dollar of earnings, without a clear signal that the shares are heavily discounted or demanding a large premium. For anyone assessing Clorox, the focus is on whether the quality and resilience of future earnings support remaining near this band or suggest a different multiple over time. Explore the numbers behind Clorox's P/E valuation.
The Clorox Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Clorox leaves off by spelling out which future paths for growth, margins and earnings would need to occur for the stock to be worth materially more or less than today’s price on the Community page. Each scenario links a fair worth estimate to a specific storyline about Clorox's possible catalysts and pressure points, so you can track over time which version feels closest to reality.
Community views on Clorox split between a recovery story tied to health and hygiene scale and a cautionary read on cost pressure and category change.
Bull case: 35% undervalued
"The launch of Clorox Purell ProCare as a unified platform for professional and healthcare customers creates a larger installed dispenser base that can support higher recurring refill revenue..."
Discover why this Narrative puts Clorox at 35% undervalued.
Bear case: 16% overvalued
"Intensifying consumer shift toward sustainable and zero-waste lifestyles, along with growing skepticism about chemical-based cleaning products, threatens to erode Clorox's core category revenues over the long term..."
Explore why this Narrative puts Clorox at 16% overvalued.
Before making a call on Clorox, there is one more piece to check
Price and earnings tell only part of the story for Clorox, because recent research screens have also highlighted specific risk flags that deserve a closer look before you act on any valuation view. Take a closer look at 2 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com