
Green Brick Partners (GRBK) After The Price Cut Is The Stock Fully Valued?
What Triggered Fresh Attention On Green Brick Partners
Argus recently lowered its target price for Green Brick Partners (GRBK), putting fresh attention on a homebuilder that combines land development, construction, and in house financing services for its controlled builders.
The shift in coverage places recent share performance, including a past month decline of about 7.7% and a past 3 months drop near 14.8%, in the context of Green Brick’s broader role across land acquisition, development, and mortgage services.
At a share price of US$61.98, Green Brick Partners has seen short term momentum fade, with the 30 day share price return down 7.66% and the year to date share price return down 1.95%, even though the 5 year total shareholder return of 149.72% remains much stronger.
Scan other homebuilders with sharper recent momentum or different risk profiles by comparing Green Brick Partners to a curated set of list of solid balance sheet and fundamentals (25 results) in the same space.
Green Brick Partners now trades almost exactly in line with the latest analyst target, despite a softer share price and slower recent earnings growth. Is that caution a useful signal or an opening mispriced by the market?
Most Popular Narrative: Fairly Valued
Green Brick Partners closed at $61.98 against a widely followed fair value of $62.00, so the current quote lines up almost exactly with that narrative while earnings pressure and land spending plans keep debate alive around the stock.
The main thing that has to go right is that Green Brick Partners converts its land heavy, self development model and growing mortgage capture into sustainably strong margins and returns, despite weaker backlog and higher discounting.
The numbers imply the share price already reflects a fairly valued, bearish view that balances industry leading profitability and institutional support against earnings declines, backlog pressure and mixed valuation signals.
See why 19 investors see Green Brick Partners as 0% undervalued.
Result: Fair Value of $62 (ABOUT RIGHT)
Still, Green Brick Partners carries clear swing factors, including ongoing pressure from higher buyer incentives and a heavier, lower-priced mix of Trophy Signature Homes.
Find out about the key risks to this Green Brick Partners narrative.
Another View On Green Brick Partners’ Valuation
The earlier discussion framed Green Brick Partners as roughly fairly priced around US$62 based on analyst targets and earnings assumptions. A different lens comes from the SWS DCF model, which puts future cash flow value closer to US$25.92 per share, well below the current US$61.98 quote.
That gap suggests investors paying today’s price are accepting a meaningful cash flow premium. It raises a simple question: Are you more comfortable anchoring on earnings based multiples, or on a cash flow model that signals less headroom?
Look into how the SWS DCF model arrives at its fair value.
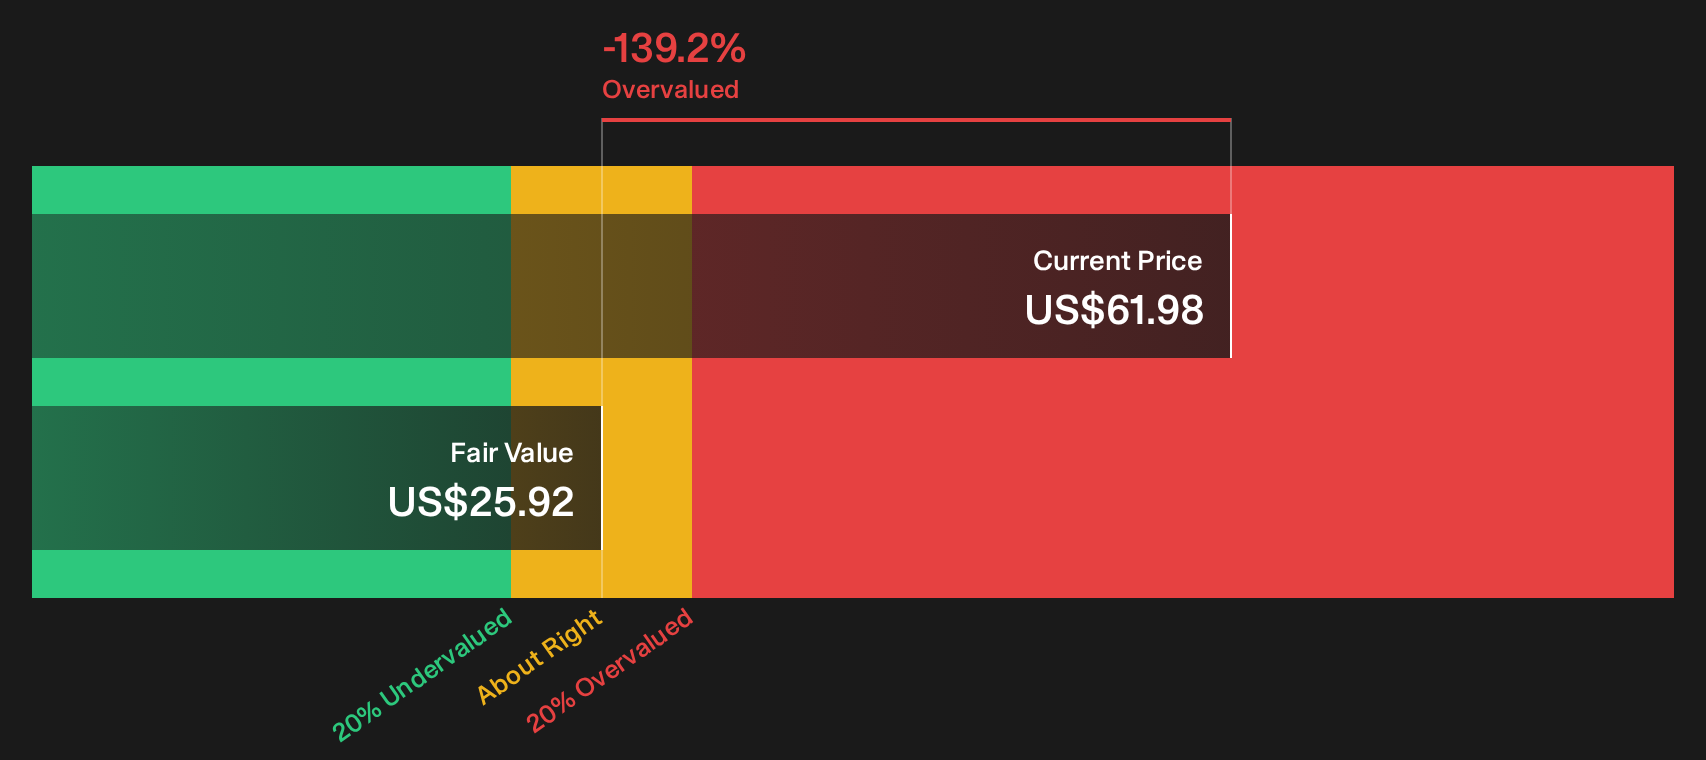
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Green Brick Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of cautious signals and long term resilience around Green Brick Partners feels finely balanced, it may be useful to review the underlying data, weigh both sides, and decide how comfortable you are with the current setup by checking the 2 key rewards and 1 important warning sign.
Looking For More Ideas Beyond Green Brick Partners?
If Green Brick Partners leaves you on the fence, broaden your watchlist with a few focused stock ideas that match different risk and return preferences.
- Target potential upside with tightly filtered opportunities by scanning a curated set of 20 high quality undiscovered gems that pair quality fundamentals with quieter market attention.
- Rebalance your risk by checking 32 resilient stocks with low risk scores that aim for steadier performance profiles backed by more resilient financial characteristics.
- Strengthen your core holdings by reviewing a 8 dividend fortresses that prioritizes higher yields while keeping an eye on balance sheet support for those payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com