
Dividend Hike Could Be A Big Moment For Northwest Natural Holding Stock
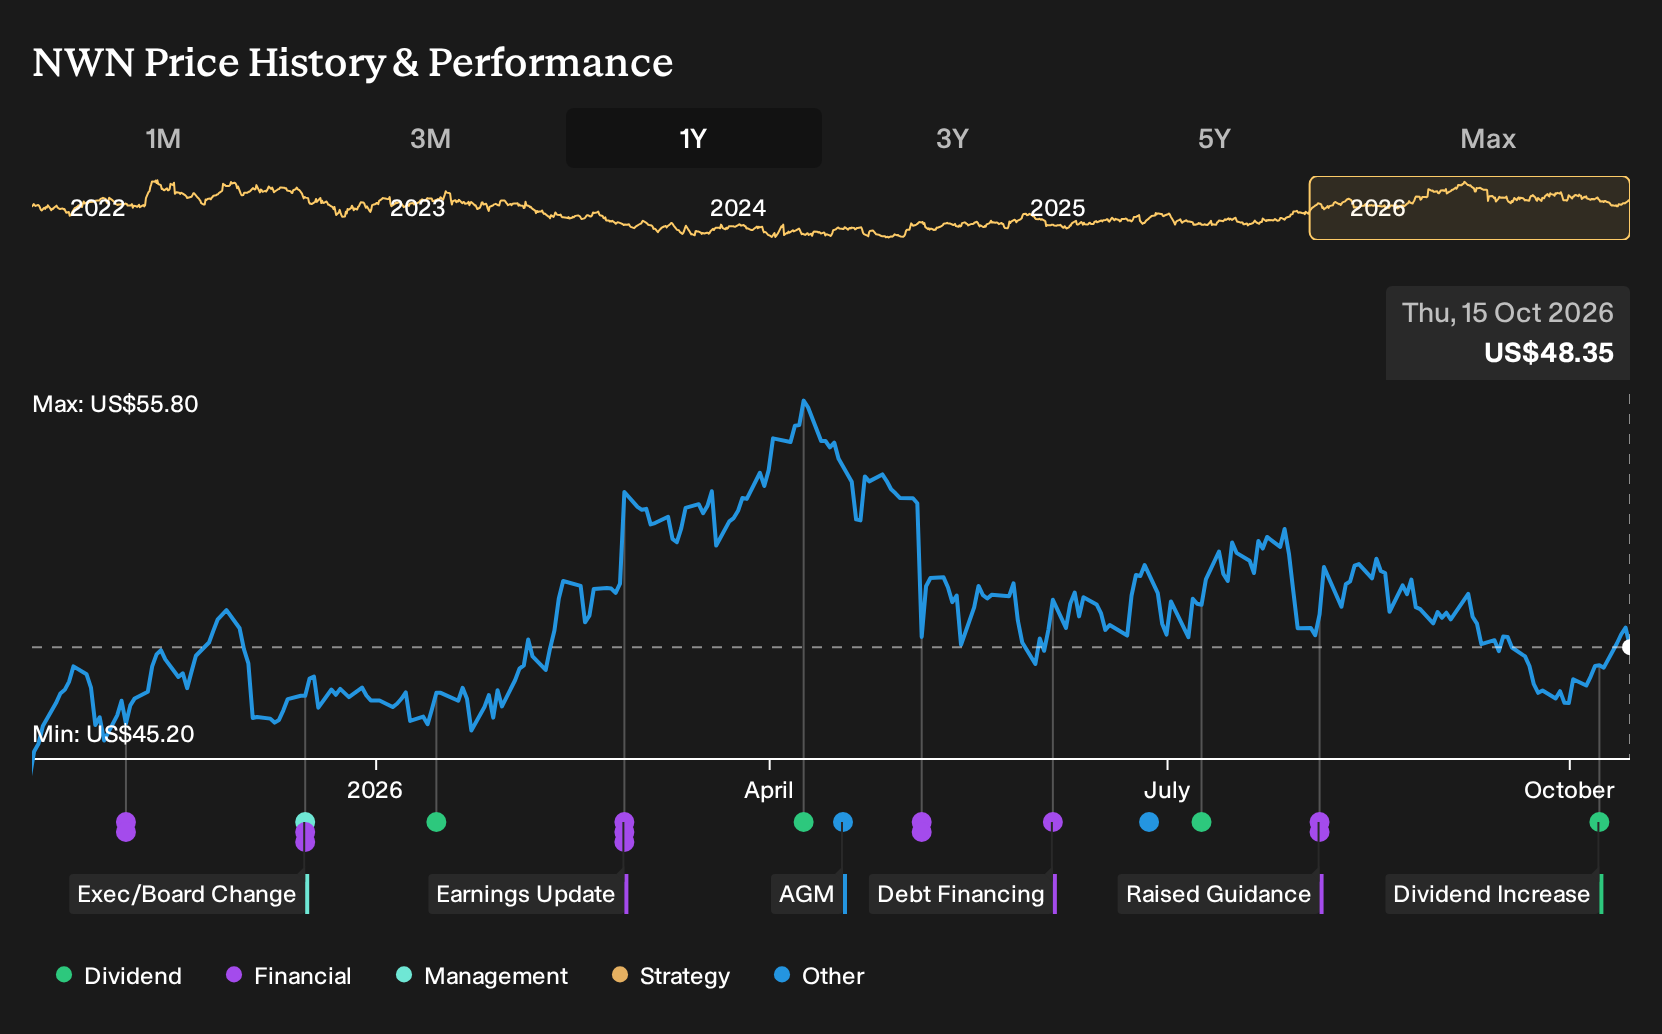
- Northwest Natural Holding’s board approved a quarterly dividend of $0.50 per share, implying an annual rate of $2.00, up from $1.97, with the payment already made on November 13, 2026, to holders of record on October 30, 2026.
- This latest dividend change represents the largest increase since 2012 and extends Northwest Natural Holding’s 71 year streak of raising shareholder payouts.
- We now look at how Northwest Natural Holding’s largest dividend increase since 2012 could influence the broader investment narrative.
Scan beyond Northwest Natural Holding’s dividend move and see how other income-focused stocks stack up in our hand picked 8 dividend fortresses today.
Northwest Natural Holding Investment Narrative Recap
To own Northwest Natural Holding, you need to be comfortable with a regulated utility that leans on gas distribution while steadily building out water and Texas exposure. The key near term swing factor is execution on projects such as SiEnergy’s meter backlog and the MX3 storage expansion, along with constructive rate frameworks in Oregon, Washington, Texas and Arizona. The dividend increase signals confidence, but does not fundamentally change those core drivers.
The biggest risk remains pressure on long term gas usage from electrification, efficiency gains and decarbonization policies in the Pacific Northwest, where much of Northwest Natural Holding earnings are generated. Higher operating, depreciation and interest costs also matter, particularly when free cash flow and interest coverage are already watch points and the dividend is not well covered by free cash flows.
The dividend news ties most directly to the broader capital plan that includes MX3 gas storage and the growing Texas and water businesses. MX3 is fully contracted with 25 year agreements and a fixed 12.5% allowed ROE. Progress toward a notice to proceed is framed as an important earnings catalyst in existing research, even though timing from here is still a key execution hurdle.
For income focused holders, the tension is clear. On one side, Northwest Natural Holding has a long dividend growth record, rising earnings over the past year and a P/E of 16.2x that sits below the wider US market but above many gas utilities. On the other, interest payments are not well covered by earnings and the payout is not backed by free cash flow, so future rate decisions, cost control and project delivery will matter a lot for how sustainable this higher dividend feels over time.
Northwest Natural Holding's narrative projects $1.6b revenue and $162.2 million earnings by 2029. This assumes 6.6% yearly revenue growth and requires earnings to rise by about $36.2 million from $126.0 million today.
Uncover why Northwest Natural Holding's fair value indicates a 19% potential upside to its current price, a discount that could close quickly.
Exploring Other Perspectives
Across three fair value estimates from the Simply Wall St Community, opinions on Northwest Natural Holding cluster between $37.86 and $57.40, which is a wide span for the same stock. Those contributors did not factor in the latest dividend increase, so you may want to weigh their views in the context of electrification risks and potential MX3 or Texas growth catalysts.
Explore 2 other Northwest Natural Holding fair value estimates, including one that suggests as much as 19% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Northwest Natural Holding research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Northwest Natural Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northwest Natural Holding's overall financial health at a glance.
Looking for more Northwest Natural Holding investment ideas?
Once you have a view on Northwest Natural Holding, it can help to widen the lens and compare it with other income and quality focused opportunities using the Simply Wall St Screener.
- For investors who want potential upside with support from strong fundamentals, start with a 20 high quality undiscovered gems that may not yet be widely followed by the market.
- If balance sheet strength is a priority, focus on companies in the list of solid balance sheet and fundamentals (25 results) to see which businesses pair financial resilience with consistent execution.
- When capital preservation comes first, concentrate on the 32 resilient stocks with low risk scores to find stocks that score well on lower risk profiles and steadier performance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com