
Insider Favorites For Growth In October 2026
Over the last 7 days, the United States market has remained flat, yet over the past 12 months, it has risen by an impressive 14%, with earnings forecasted to grow by 17% annually. In this context of steady growth and positive earnings outlooks, identifying companies with high insider ownership can provide valuable insights into potential investment opportunities as insiders often have a deep understanding of their company's prospects.
Top 10 Growth Companies With High Insider Ownership In The United States
| Name | Insider Ownership | Earnings Growth |
| Upstart Holdings (UPST) | 14.0% | 70.2% |
| Standard Nuclear (STDN) | 18.8% | 64.2% |
| Sable Offshore (SOC) | 11.3% | 71.3% |
| Precigen (PGEN) | 11.7% | 54% |
| Nu Holdings (NU) | 22.8% | 22.3% |
| Karman Holdings (KRMN) | 13.6% | 56.4% |
| Himax Technologies (HIMX) | 29.1% | 70.2% |
| Figure Technology Solutions (FIGR) | 21.4% | 32.4% |
| Energy Vault Holdings (NRGV) | 10.5% | 67.3% |
| Almonty Industries (ALM) | 10.8% | 57.6% |
We'll examine a selection from our screener results.
Karman Holdings (KRMN)
Simply Wall St Growth Rating: ★★★★★★
Overview: Karman Holdings Inc., with a market cap of approximately $3.99 billion, operates through its subsidiary to design, test, manufacture, and sell mission-critical systems in the United States.
Operations: KRMN generates revenue of $589.55 million from its operations in the Space and Defense Industry.
Insider Ownership: 13.6%
Return On Equity Forecast: 24% (2029 estimate)
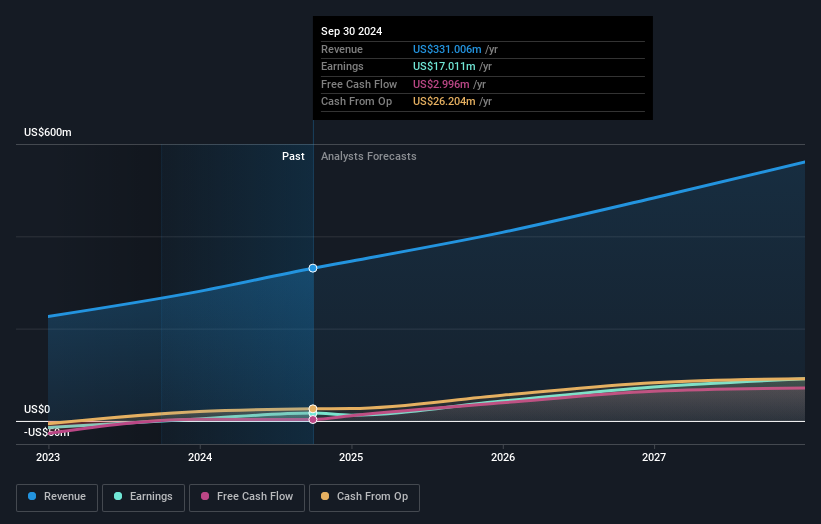
Karman Holdings demonstrates strong growth potential with revenue forecasted to grow at 27.7% annually, outpacing the US market's average. Earnings are expected to rise significantly at 56.4% per year, surpassing market expectations. Recent insider activity shows substantial buying, indicating confidence in the company's trajectory post-IPO. However, despite a high Return on Equity forecast of 23.9%, interest payments remain a concern as they are not well covered by earnings, which could impact financial stability if unaddressed.
- Take a closer look at Karman Holdings' potential here in our earnings growth report.
- Our comprehensive valuation report raises the possibility that Karman Holdings is priced higher than what may be justified by its financials.
Pinterest (PINS)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Pinterest, Inc. operates as a visual search and discovery platform across the United States, Canada, Europe, and internationally with a market cap of approximately $12.32 billion.
Operations: The company generates revenue primarily from its Internet Information Providers segment, totaling approximately $4.56 billion.
Insider Ownership: 11.8%
Return On Equity Forecast: 31% (2029 estimate)
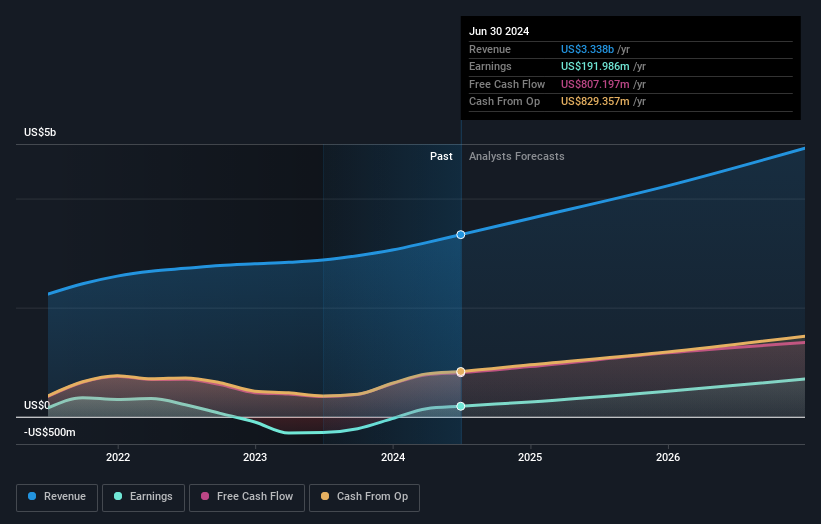
Pinterest's growth outlook is promising, with earnings expected to grow significantly at 29% annually, surpassing the US market average. Despite a recent drop from the FTSE All-World Index and insider selling, its substantial insider ownership can signal confidence in long-term prospects. The company recently secured a $700 million revolving credit facility to bolster financial flexibility and introduced innovative advertising solutions like Visual Search Ads to enhance revenue streams amidst slower forecasted revenue growth compared to the market.
- Dive into the specifics of Pinterest here with our thorough growth forecast report.
- The valuation report we've compiled suggests that Pinterest's current price could be inflated.
Ryan Specialty Holdings (RYAN)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Ryan Specialty Holdings, Inc. is a service provider offering specialty products and solutions for insurance brokers, agents, and carriers across various regions globally with a market cap of $9.72 billion.
Operations: The company generates revenue primarily from its Insurance Brokers segment, amounting to $3.16 billion.
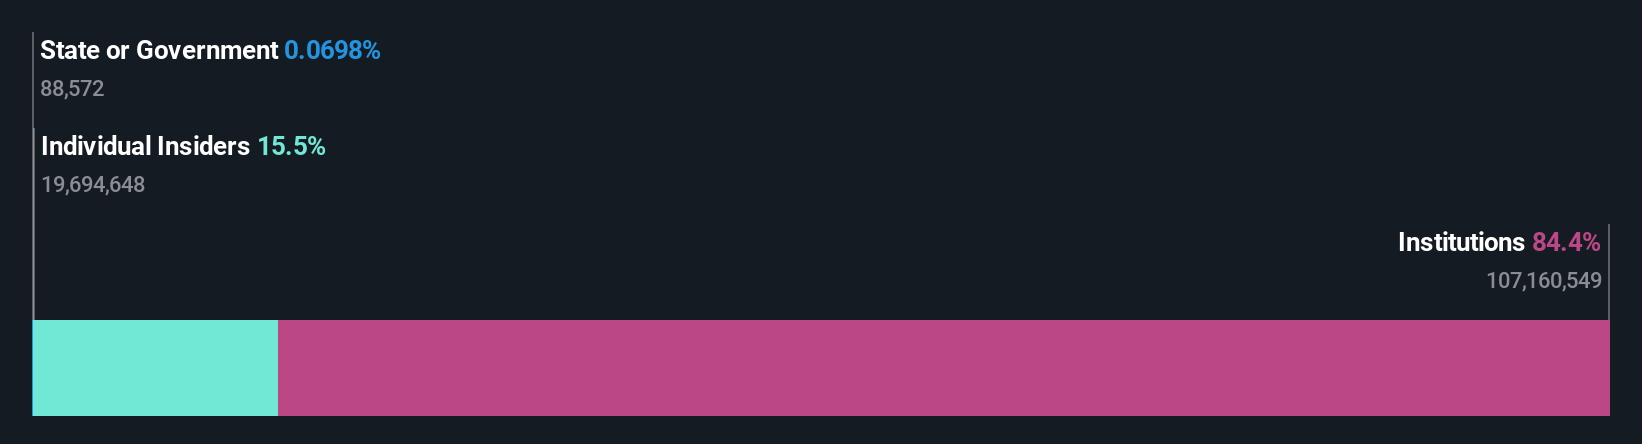
Insider Ownership: 11.8%
Return On Equity Forecast: 85% (2029 estimate)
Ryan Specialty Holdings shows strong growth potential, with earnings forecasted to grow significantly at 49.7% annually, outpacing the US market. Despite slower revenue growth projections at 7.5% per year, the company maintains a robust M&A strategy and high insider ownership, indicating confidence in its long-term prospects. Recent actions include a US$300 million share buyback and consistent dividend payouts, although recent financial results show mixed performance with declining quarterly net income but substantial six-month gains.
- Click to explore a detailed breakdown of our findings in Ryan Specialty Holdings' earnings growth report.
- According our valuation report, there's an indication that Ryan Specialty Holdings' share price might be on the expensive side.
Make It Happen
- Navigate through the entire inventory of 184 Fast Growing US Companies With High Insider Ownership here.
- Ready To Venture Into Other Investment Styles? Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com