
What to Expect From The Williams Companies’ Next Quarterly Earnings Report
The Williams Companies, Inc. (WMB) is a Tulsa, Oklahoma-based energy infrastructure company that specializes in gathering, processing, transporting, and storing natural gas across the United States. With a market capitalization of $89.1 billion, the company operates more than 32,000 miles of pipelines across 24 states and handles approximately one-third of the natural gas consumed in the U.S.
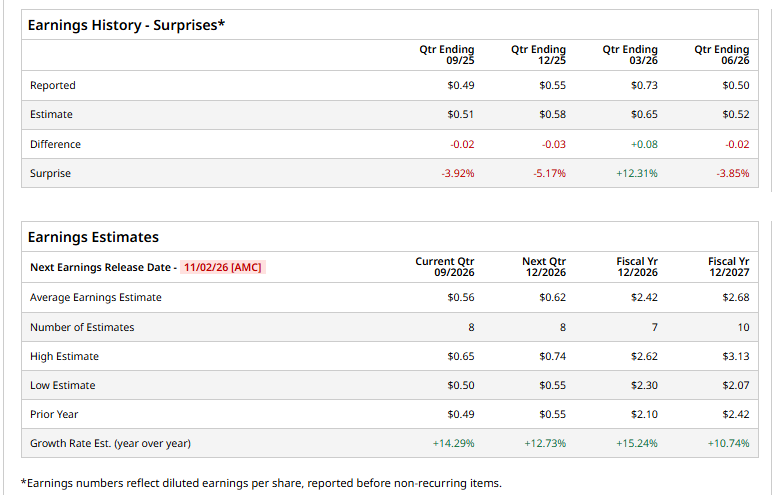
The company is expected to announce its fiscal Q3 earnings for 2026 on Monday, Nov. 2, after the market closes. Ahead of this event, analysts expect this energy infrastructure company to report a profit of $0.56 per share, up 14.3% from $0.49 per share in the year-ago quarter. The company has topped Wall Street’s earnings estimates in only one of the last four quarters, missing them in the other three.
For fiscal 2026, analysts expect WMB to report a profit of $2.42 per share, up 15.2% from $2.10 per share in fiscal 2025. Furthermore, its EPS is expected to grow 10.7% year over year to $2.68 in fiscal 2027.
Shares of WMB have rallied 8.5% over the past 52 weeks, trailing both the S&P 500 Index's ($SPX) 16.1% uptick but trailing the Energy Select Sector SPDR Fund’s (XLE) 54.2% rise over the same time frame.
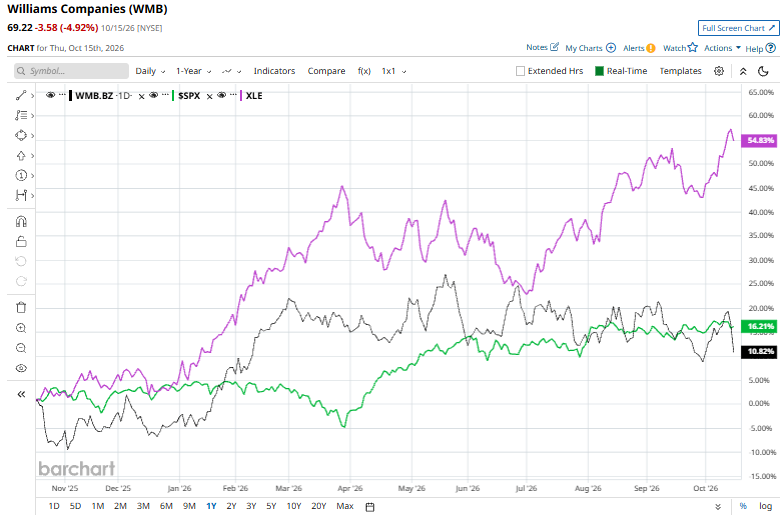
Williams Companies has lagged behind the broader market amid earnings misses, elevated capital spending, and concerns over its growing debt burden. Weak summer natural gas prices have also weighed on producer activity, creating potential headwinds for its volume-driven operations.
However, Williams is doubling down on growth. On Sept. 8, its shares rose 2.3% after the company announced a $2.75 billion public offering of senior notes maturing from 2029 to 2056 at interest rates of 5% to 6.4%. The proceeds will help refinance outstanding commercial paper and fund capital expenditures and other corporate needs, although the additional borrowing underscores balance-sheet concerns.
Earlier, on Sept. 3, the company announced the completion of its approximately $5.5 billion acquisition of Momentum Midstream, including $3.5 billion in cash and debt consideration and $2 billion in Williams’ equity. The deal adds more than 4,000 miles of pipelines, 6 Bcf/d of gathering capacity, and substantial transportation infrastructure in the Haynesville basin. The acquisition strengthens Williams’ natural gas network and positions it to capitalize on growing Gulf Coast demand from LNG exports, power generation, and industrial customers, while creating opportunities for further expansion.
Wall Street analysts are very optimistic about WMB’s stock, with a "Strong Buy" rating overall. Among 24 analysts covering the stock, 20 recommend "Strong Buy," two indicate "Moderate Buy," and two suggest a “Hold.” Its mean price target of $85.68 implies an upswing potential of 23.8% from the current market prices.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.